Business
Here are some reactions of realtors on RBI’s policy outcome on realty sector
The Reserve Bank of India on Wednesday raised the key lending rate or repo rate by 50 basis points to 4.9 per cent to tame rising inflation, which has been now above the central bank’s 6 per cent tolerance level for four months in a row.
Repo rate is the rate at which the central bank lends short-term funds to banks.
In line with the rate hike by the RBI, some banks and non-banking finance companies too had raised their lending rates, which will essentially lead to an increase in EMIs for borrowers.
On Wednesday, RBI decided to increase the existing limits on individual housing loans by cooperative banks.
Accordingly, the limits for Tier I or Tier II urban cooperative banks shall stand revised from Rs 30 lakh or Rs 70 lakh to Rs 60 lakh or Rs 140 lakh, respectively, which essentially means doubling of the limit.
The increased limits will apply for Primary (Urban) Co-operative Banks (UCBs), and Rural Cooperative Banks (RCBs) — State Cooperative Banks and District Central Cooperative Banks.
For RCBs, the limits will increase from Rs 20 lakh to Rs 50 lakh for such banks with assessed net worth less than Rs 100 crore; and from Rs 30 lakh to Rs 75 lakh for other such RCBs.
Besides, considering the growing need for affordable housing and to realise their potential in providing credit facilities to the housing sector, the RBI decided to allow State Co-operative Banks (StCBs) and District Central Co-operative Banks to extend finance to Commercial Real Estate – Residential Housing (CRE-RH) within the existing aggregate housing finance limit of 5 per cent of their total assets.
Following are some of the reactions from real estate experts and developers on the RBI’s measures:
Rohan Pawar, CEO of Pinnacle Group said, during the pandemic, the low interest rate regime had boosted the housing demand, and RBI’s decision to hike the interest rate again by 50 basis points to 4.90 per cent was expected to tackle the tight inflation of the country.
“The increase of rates could adversely affect housing demand because of increased EMIs and lower eligibility on home loans. This will create an impact on the ongoing growth momentum in the sector in addition to increasing input costs. However, we still believe that preference of homebuyers for owning a home will continue to boost demand.”
Niranjan Hiranandani, Vice Chairman of NAREDCO said, taming steep inflation hike is a preordained measure by RBI, given the global economic ballgame. Soaring commodity prices especially with food and energy prices, plummeting currencies, supply side shocks are the foremost reasons for rising input cost.
“It is evident that home loan interest rate hike will impair the home buying rally as pay out in terms of EMI is scheduled to rise. But according to me this crater in demand sentiment is a makeshift move, as home loans are based on floating rate for a long tenure. The EMI constraint will be eased as rates are expected to normalise once the global situation is stabilised.”
The hike in the limit of individual loans by co-operative banks by 100 per cent is a welcome initiative for home buyers who opt for home loans from co-op banks.
Atul Goel, MD of Goel Ganga Group said, the RBI’s step to increase the repo rate has been on the expected lines. To curb inflation, the regulatory bodies in India were required to control liquidity circulation in the economy. For a few months, the inflation rate has been above 6 per cent, which is beyond the RBI’s safe zone.
“If not controlled, the inflationary pressure could destabilise an otherwise bullish Indian economy. Although the recent step will increase the home loan rates, an unstable economy is not conducive to the overall health of the real estate industry. For the industry to operate optimally, it is important that the economy continues to grow in a stable, inclusive, and steady fashion.”
Suren Goyal, Partner at RPS Group said, the group welcomes the step of the apex body to increase the overall repo rates and believes it will help in clamping down inflation and smoothen economic growth.
“A rise in inflation can soften the stance on an otherwise robust real estate industry. Already raw material prices are increasing and an unbridled rate of inflation will further drive the input costs northwards, therefore resulting in cost overruns for the developer fraternity.”
Manoj Gaur, CMD of Gaurs Group and President- CREDAI NCR said it has been a fine balancing act by RBI.
“We understand that the hike in repo rate by 50 basis points will impact interest rates of consumer loans and make home loan dearer right at the time when real estate sector was coming out of the throes of pandemic and affect sales in the short term. However, by reining in inflation it will ultimately benefit the real estate sector that is bogged down by high input costs.”
Amit Modi, President of CREDAI Western UP opined that the increase in the repo rate will hamper the sentiments of the buyers, especially first time home buyers who are heavily reliant on home loans.
“It will be a barrier to the growth trajectory of the revived sales post-Covid. Millions of homebuyers will be sidelined and alienated from the property markets after the hike. It will slow down the pace of sales that has taken a rise in the recent past.”
Pradeep Aggarwal, Chairman of Signature Global (India) said the repo rate hike could be termed as a reformative move, the stated aim was clear in current macro and micro economic conditions.
“There was no other option left but to rein in inflation through monetary control measures. This might slightly influence real estate, but it will not impact consumer confidence or demand. Simultaneously, increasing the 100 per cent limit of individual loans by apex bank for co-operative banks, would surely spread a positive communication among each stakeholder.”
Sanjay Sharma, Director of SKA Group said the repo rate hike comes at the time when there was a renewed buyer interest in every segments of the real estate
“This move will definitely have an impact on buyers’ sentiments but at the same time let’s wish that the step brings the expected relief and benefits the sector that is also reeling from high input costs on account of various factors including inflation.”
Dharmesh Shah, CEO of Hero Homes said that there will also be a certain increase in home loan rates that will backtrack home buyers’ aspirations to invest in property markets and impact residential sales for a short period of time.
Prateek Mittal, Executive Director at Sushma Group said the latest move will definitely help the country as well as benefit the real estate sector that is already battling high input costs on account of various external factors and the consequent increase in fuel cost.
“Though this increase will also impact the buying power of consumers, we feel the impact will be taken in stride.”
According to Sharad Mittal, Director and CEO of Motilal Oswal Real Estate Funds: “Now with mortgage loan rates set to go up, we may notice a slight demand blip in the short term but overall outlook on the sector remains strongly bullish in the long term.”
“In an interesting move, RBI has now allowed rural co-operative banks to lend towards residential housing projects. This will help improve much-needed liquidity in the sector.”


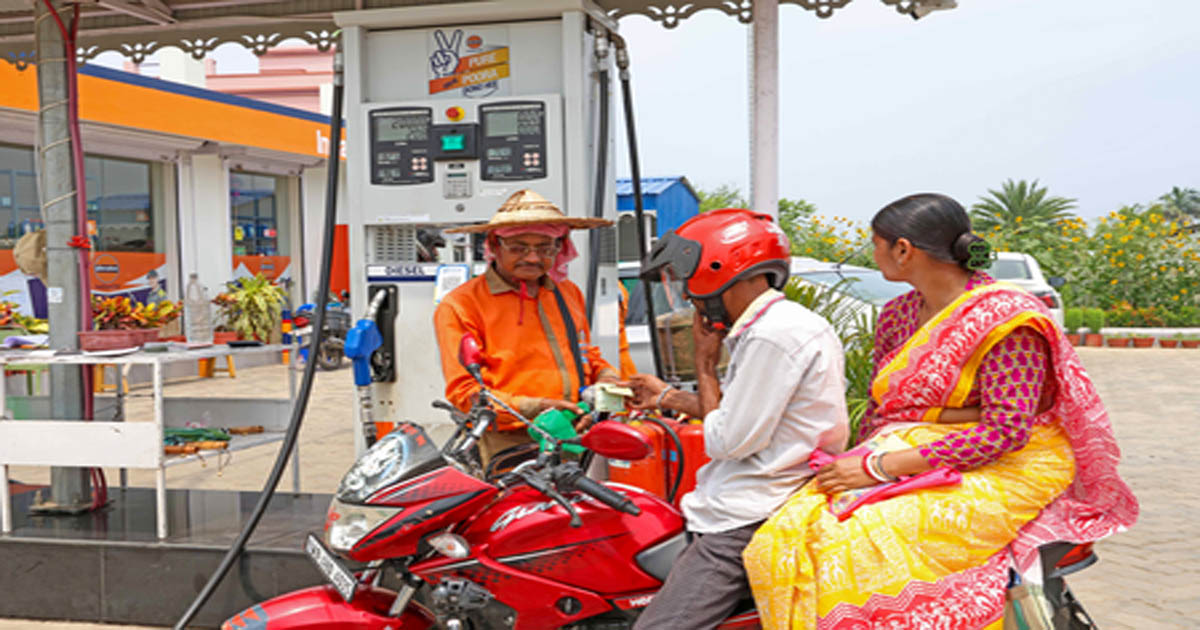
New Delhi, Sep 17: Representatives of the All India Petroleum Dealers Association (AIPDA) met senior officials of the Ministry of Petroleum and Natural Gas on Thursday to discuss their demand for exemption from the merchant discount rate (MDR) on UPI transactions on fuel sales at petrol pumps.
The dealers’ body said in a statement that the issue was discussed with senior officials of the Petroleum Ministry as the additional MDR cost could put pressure on dealer margins, as retail fuel sales are made on prescribed commissions.
The new UPI framework levies an MDR of Rs 5 per transaction on petrol and diesel purchases above Rs 2,000. Such transactions account for around 30-40 per cent of total purchases across retail outlets in the country, according to dealers.
Petroleum Ministry officials sought to explain the rationale behind introducing MDR, which was required to support the development of the next layer of India’s UPI digital infrastructure.
“Petroleum dealers have been at the forefront of adopting digital payments and have worked closely with the government to promote their use across the country,” the AIPDA said.
The association said it expects to continue the dialogue with the government.
“We look forward to continuing the dialogue towards a mutually beneficial solution for consumers, petroleum dealers, and all stakeholders in India’s UPI ecosystem,” the statement said.
Dealers have raised concerns as digital payments have become an important mode of payment at petrol pumps, particularly for higher-value purchases.
Petroleum dealers have sought a complete exemption for fuel retail transactions, citing the nature of their business and the impact of MDR-related costs on their margins.
The Finance Ministry clarified that MDR is neither a tax nor a charge collected by the government or NPCI. It is distributed among payment ecosystem participants, including banks and payment application providers, to support the operation and continued expansion of the UPI ecosystem.
Transactions above Rs 2,000 in essential and thin-margin sectors, including railways, telecommunications, insurance, fuel and agricultural inputs, will attract a flat MDR of Rs 5 per transaction. The flat charge will provide cost certainty for critical public services and businesses operating on narrow margins.
Mumbai, Sep 17: In a major push to reinforce Maharashtra’s fiscal health and support its long-term growth roadmap, Maharashtra Chief Minister Devendra Fadnavis announced the constitution of the Maharashtra Sustainable Public Finance Committee.
Headed by renowned economist and former Union Finance Secretary Dr Vijay Kelkar, the high-level panel, which was announced late Wednesday evening, is tasked with recommending measures to ensure sustainable growth in tax and non-tax revenues.
The decision forms an integral part of the state’s ‘Viksit Maharashtra @ 2047’ vision document, which outlines a strategic roadmap to scale the state’s economy to $1 trillion by 2030 and $5 trillion by 2047—coinciding with the centenary of India’s Independence.
The panel has been tasked with making recommendations to modernise the tax system, plug revenue leakages, and rationalise tax rates, fees, and exemptions; identify untapped revenue streams and maximise returns from public assets and state enterprises; streamline public spending while balancing expanding committed expenditures such as salaries, pensions, interest payments, and welfare schemes; and devise a fiscally responsible roadmap to reduce reliance on borrowings for infrastructure projects and budget deficits.
The Kelkar Committee comprises Prof Karthik Muralidharan (founder-director, CEGIS), Dr Nitin Kareer (former Chief Secretary, Maharashtra), T Rabi Sankar (former Deputy Governor, Reserve Bank of India) and Dr Ashima Goyal (President, The Indian Econometric Society).
The formation of the panel comes at a critical juncture for Maharashtra. While the state actively pursues an investment-led growth strategy across core sectors—including infrastructure, human resource development, water security, urban management, and energy transition—it faces growing fiscal constraints.
Maharashtra government’s Vision document has suggested restructuring the government expenditure policy to align with long-term capital formation, identifying alternative financing models and private capital inflows.
Fiscal deficit targets are capped within standard Fiscal Responsibility and Budget Management (FRBM) boundaries, targeting 2.8 per cent to 3.0 per cent of Gross State Domestic Product (GSDP) while keeping the revenue deficit under 0.7 per cent of GSDP, and implementation is tracked quarterly via a dedicated Vision Management Unit chaired by the chief minister.
Adhering to the targets set under the FRBM Act has proved challenging due to rising welfare commitments and debt servicing costs. Consequently, the government has frequently resorted to market borrowings to fund capital projects and offset short-term liquidity shortfalls.
The newly appointed Kelkar Committee is expected to deliver structural fiscal remedies to reverse this trend and secure long-term financial sustainability for the state.
Business
From GDP to startups: Key numbers tracking India’s economic and infrastructure growth as PM Modi turns 76

New Delhi, Sep 17: As Prime Minister Narendra Modi on Thursday turned 76 with his tenure marked by expansion across India’s economy, financial inclusion, infrastructure and startup ecosystem.
Several key numbers highlight the scale of changes recorded during his time as prime minister. On of them is India’s real gross domestic product (GDP) which grew 7.8 per cent in the April-June quarter of fiscal 2026-27 with manufacturing and services supporting the expansion.
As per government data, real gross value added rose 8.2 per cent, while investment grew 11.9 per cent, household consumption increased 7.1 per cent and exports rose 12 per cent.
Apart from that, India’s nominal GDP is estimated at around $4.15 trillion that underscores the expansion of the world’s major emerging economy despite global trade and geopolitical uncertainties.
In addition, India’s foreign exchange reserves also rose to a record $785.7 billion in the week ended September 4, according to Reserve Bank of India data.
The reserves have increased for 10 consecutive weeks and surged nearly $120 billion over that period. Also, India is the world’s fourth-largest holder of foreign exchange reserves.
Moreover, the number of beneficiaries under the Pradhan Mantri Jan Dhan Yojana stood at 59.21 crore as of September 2, according to the government, while deposits in the accounts totalled Rs 3.17 lakh crore and 41.39 crore RuPay debit cards had been issued.
Women accounted for 32.98 crore accounts, while 46.03 crore beneficiaries were in rural and semi-urban areas, the official data said.
On the infrastructure front, the nation’s national highway network under PM Modi’s leadership has expanded to 146,572 km from 91,287 km in fiscal 2013-14.
The Economic Survey said average annual highway construction rose to 9,704 km during 2014-25, compared with 4,174 km during 2004-14.
Under his guidance, the number of startups recognised by the Department for Promotion of Industry and Internal Trade has risen to more than 2.47 lakh as of August 2026 from 502 in 2016
Meanwhile, Startup India rules have also increased the turnover threshold for startup recognition to Rs 200 crore, while DeepTech startups have a higher ceiling of Rs 300 crore.

Mumbai Cyber Cell arrests 6 members of organized gang in major operation; Beware of cyber fraudsters; Digital arrest has no legal status; DCP Bajrang Bansode

Bengaluru: Family dispute suspected behind deadly attack on Bengal nurse by estranged husband from TN (Ld)

Municipal Commissioner Ashwini Bhide visits Mumbai’s Veermata Jijabai Bhosale Botanical Garden and Zoo to inspect various ongoing projects and initiatives.

Mumbai: Death of tiger Bijli (T2) in Sanjay Gandhi National Park

‘Your leadership has transformed India into a world power’: Netanyahu hails PM Modi on his 76th birthday

Four more Indian nationals rescued in Nepal, 120 cross safely from China: MEA

Gift to President Putin part of PM Modi bid to globally display India’s heritage

Nepal floods: First batch of 106 stranded Maharashtra tourists reaches India; 84 more expected today (Ld)

India, Brazil sign ICT MoU to deepen digital, telecom cooperation

Maharashtra: 17-year-old boy dies by suicide on Raksha Bandhan after emotional social media posts
-

 Crime4 years ago
Class 10 student jumps to death in Jaipur
-

 Maharashtra2 years ago
Mumbai Local Train Update: Central Railway’s New Timetable Comes Into Effect; Check Full List Of Revised Timings & Stations
-

 Maharashtra2 years ago
Mumbai To Go Toll-Free Tonight! Maharashtra Govt Announces Complete Toll Waiver For Light Motor Vehicles At All 5 Entry Points Of City
-

 Maharashtra2 years ago
False photo of Imtiaz Jaleel’s rally, exposing the fooling conspiracy
-

 National News2 years ago
Ministry of Railways rolls out Special Drive 4.0 with focus on digitisation, cleanliness, inclusiveness and grievance redressal
-

 Maharashtra2 years ago
Maharashtra Elections 2024: Mumbai Metro & BEST Services Extended Till Midnight On Voting Day
-

 National News2 years ago
J&K: 4 Jawans Killed, 28 Injured After Bus Carrying BSF Personnel For Poll Duty Falls Into Gorge In Budgam; Terrifying Visuals Surface
-

 Crime2 years ago
Baba Siddique Murder: Mumbai Police Unable To Get Lawrence Bishnoi Custody Due To Home Ministry Order, Says Report