Business
Tough road ahead for India’s Crypto moment
The Cryptocurrency and Regulation of Official Digital Currency Bill 2021, seeking to prohibit all private cryptocurrencies in India, was set to be tabled in the Winter Session of Parliament that began on November 29. But the Bill did not make it to the table — second time in a year — as the chorus around the legality of digital coins and how to safeguard investors’ money grew louder.
Grave concerns have now been raised over the misuse of digital coins on the Dark Web for terror acts and drugs trafficking by militant organisations, and for money laundering and hawala-based transactions — posing serious threat to national security and a big challenge to the security agencies in India.
While the Reserve Bank of India (RBI) wants a blanket ban on cryptocurrencies, the government remains in a confused state of mind.
From “all windows on cryptocurrencies will not be closed” to “no proposal to recognise Bitcoin as currency”, and “regulating cryptocurrency will have to be a collective effort”, Finance Minister Nirmala Sitharaman and her team is yet to make up their mind as to how to deal with this emerging situation, especially at a time when several countries like China, Bangladesh, Russia, Egypt, Morocco, Qatar, Turkey and Vietnam have banned or prohibited/restricted cryptocurrencies.
Will India finally see a fruitful Crypto Bill, after inserting global knowledge into its clauses as being sought by the government, next year?
According to Subhash Chandra Garg, former Finance Secretary of India and a key figure behind drafting the original Bill, crypto businesses and assets (built on the Blockchain cryptography technology in decentralised databases), including stable-coin currencies, are expanding fast in the world.
“India, though not quite deep into developing crypto platforms like Ethereum or in creating crypto-businesses, has acquired a fancy for crypto-assets of different types. This fascination started with Bitcoin and has now expanded to many other crypto-assets (loosely referred to as crypto-currencies),” Garg told IANS.
Garg sees this fascination continuing in 2022 as well.
“Although, if there is a big crash in crypto-asset prices, which is inevitable sooner or later, Indian investors might bolt from crypto-stables, but only after their noses get bruised,” he warned.
Organisations globally were forecast to spend nearly $6.6 billion on Blockchain solutions this year, an increase of more than 50 per cent compared to 2020, according to the International Data Corporation (IDC).
Blockchain spending will continue to see strong growth throughout the 2020-2024 forecast period with a five-year compound annual growth rate (CAGR) of 48 per cent and reaching nearly $19 billion in 2024.
The deployment of Blockchain technology for cross-border settlement will drive significant cost savings for banks, rising from $301 million in 2021 to $10 billion in 2030 — a whopping 3,300 per cent growth in cost savings, according to a report from Juniper Research.
From an industry perspective, banking leads the way in Blockchain spending, followed by process manufacturing and discrete manufacturing and IT services and business services.
Given its pool of tech talent and early adoption, India will have a crucial role to play in the Blockchain-based financial world order.
“Blockchain-cryptography technology is brilliant and full of promise and the businesses and assets being built thereon are quite valuable. However, there is no good way at present to assess the true value of crypto-assets and businesses. Present prices reflect the euphoria of this potential,” Garg noted.
“Indian entrepreneurs might also be able to unscramble this technology by then and start building good crypto-Blockchain technology service businesses. That would be the beginning of true crypto adoption in the country,” he added.
Amid the growing adoption around Blockchain, the cryptocurrency exchanges have recently mushroomed with deep business interests in mind.
According to experts, the government must not only ensure that investors’ money is safe, but also trace millions of dollars that have been routed via crypto exchanges and platforms that the relevant authorities have no clue about.
A media report said in November that over Rs 4,000 crore of illegal transactions via cryptocurrency exchanges have been unearthed by the Enforcement Directorate (ED) in the last one year.
“The crypto craze has reached Tier 2 and 3 towns and non-regulation of this market of Rs 6 lakh crore size is raising questions on the sovereign authority of the Government of India. Non-levy of GST in various layers of its transaction and non-imposition of income tax with penalty is already causing huge loss to the state and Central government’s revenues,” said New Delhi-based cyberlaw expert Virag Gupta.
The Indian government faces a tough road ahead on Crypto in 2022, and taking the right decision will have to be a collective one.


Mumbai, Sep 28: Domestic equity benchmarks opened lower on Monday weighed down by persistent external headwinds with financial, realty and auto stocks leading declines in early trade.
Nifty opened 75.60 points or 0.33 per cent lower at 23,064.90, while Sensex fell more than 150 points or 0.22 per cent to 73,734.83.
Among Nifty stocks, Hindalco Industries, Bajaj Finance, Kotak Mahindra Bank, Grasim Industries and Shriram Finance were top losers declining up to 1.76 per cent.
Broader sectoral weakness was led by realty stocks with Nifty Realty down over 1 per cent. Meanwhile, cement, financial services, private banks, auto and FMCG indices also fell nearly 1 per cent each.
However, Nifty Pharma was among the few gainers which was up inches higher.
Market analysts said domestic economic resilience and improving corporate earnings were being overshadowed by external pressures, including elevated crude oil prices and US bond yields.
“Brent crude at $106 and the US 10-year yield at 5.2 per cent are strong headwinds that are weighing on markets,” the analysts said. Foreign portfolio investors had turned sellers again in September after buying in July and August, according to them.
They further noted that the broader market continued to show momentum as foreign investors appeared to be buying midcap and smallcap stocks despite elevated valuations, while selling largecaps.
For the Nifty, immediate support is seen at 22,900-23,000, while resistance is placed at 23,250-23,300. The index is likely to remain volatile as traders watch these levels for signs of stability, as per market experts.
On the commodities front, international benchmark Brent crude rose more than 2 per cent to $106.69, while US West Texas Intermediate (WTI) crude gained over 1 per cent to $93.82.
In Asia, markets showed a mostly negative trend. Japan’s Nikkei, Hong Kong’s Hang Seng and Jakarta Composite declined up to 2 per cent.
Overnight in the US, Wall Street ended higher, with the S&P 500 up 0.51 per cent and the Nasdaq up 0.48 per cent.
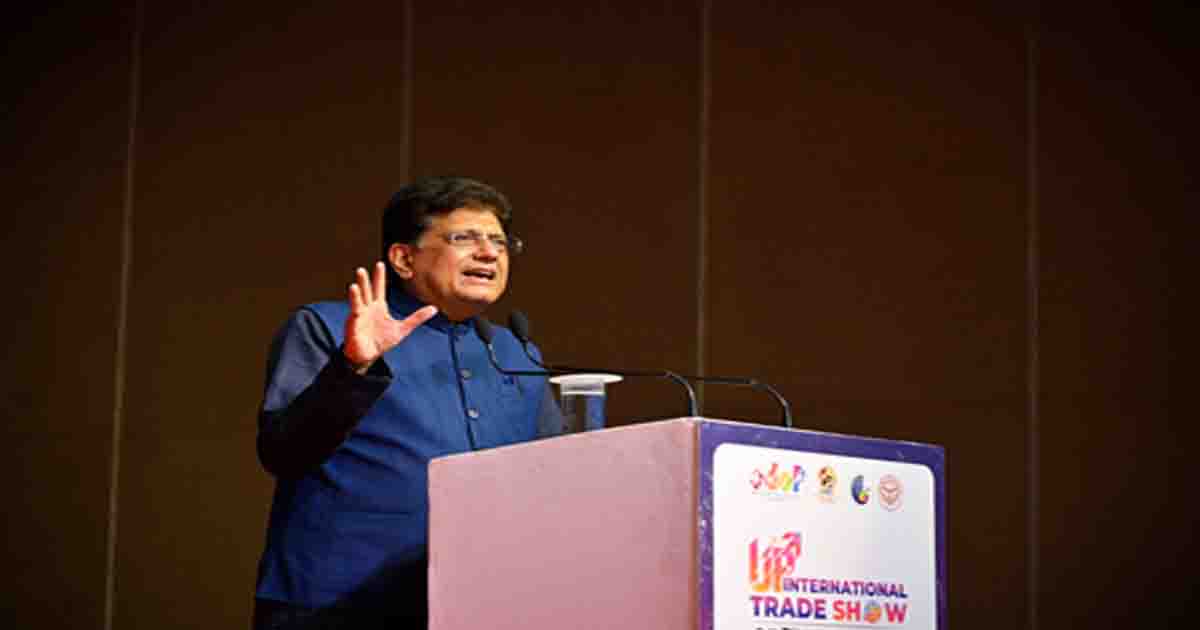
Greater Noida, Sep 27: Union Commerce and Industry Minister Piyush Goyal highlighted that as global markets open up to India through Free Trade Agreements (FTAs), Uttar Pradesh’s annual exports are expected to more than double from Rs 2 lakh crore to Rs 5 lakh crore by 2030.
Addressing the UP International Trade Show in Greater Noida, Goyal said that expanding exports, investments and global market access would contribute to the state’s goal of becoming a $1 trillion economy.
The minister said the expanding global market access through FTAs, investments, tourism and international recognition of Uttar Pradesh’s products and brands would create new opportunities for the state’s entrepreneurs. He called for active participation and cooperation from the state’s trade and industrial community in taking forward this development journey.
He said new investments are expected to flow into India from across the globe and noted that Uttar Pradesh has emerged as a preferred investment destination, supported by favourable industrial policies and proactive industrial schemes. He said major corporations and global investors are arriving across sectors, creating new employment opportunities.
The minister highlighted the role of modern technology, international enterprises, and the evolving craftsmanship and technical skills of Uttar Pradesh’s youth in driving the state’s development. He said international events of this scale provide opportunities for direct access to global markets, enabling Uttar Pradesh’s diverse products, cuisines and services to reach international markets.
Goyal underscored the international participation at the UP International Trade Show, including six partner countries, hundreds of delegates and exhibitors, and buyer-seller meetings. He noted the participation of international stakeholders and the opportunities created for businesses through the event.
He highlighted the development of expressways, modern airports and industrial parks in Uttar Pradesh and noted the state’s growing presence across sectors including defence, semiconductors, electronics and other modern high-technology domains. He also referred to the expansion of a large robotics manufacturing facility in Greater Noida as an example of modern industrial growth and technological development.
The next frontier for Uttar Pradesh’s development lies in expanding exports in global markets, attracting international investments, strengthening tourism and building global recognition for brands from the state, he said, adding that the state is strengthening its foundation for greater global trade and progressing towards its development objectives.
The minister also highlighted the importance of coordination between the Central and state governments, along with the participation of citizens, youth and stakeholders from the trade and industrial sector, in supporting Uttar Pradesh’s continued economic and export growth.
New Delhi, Sep 27: State Bank of India (SBI), Bank of Baroda (BoB), Punjab National Bank (PNB) and several other public sector banks are open on Sunday (September 27), giving customers an opportunity to complete their banking work before a proposed three-day nationwide bank strike from September 28 to September 30.
The special Sunday opening applies to public sector banks (PSBs) and regional rural banks (RRBs), following a direction aimed at ensuring the availability of regular banking services ahead of the proposed strike. Customers who need to visit a branch for important banking work can therefore use the additional working day, subject to the operational arrangements and staffing at individual branches.
The decision to open PSBs and RRBs on Sunday was taken following a meeting held on September 21 between officials from the Finance Ministry, public sector banks, regional rural banks, the Indian Banks’ Association (IBA) and NABARD.
The move assumes significance as September 26 and 27 fall on Saturday and Sunday, respectively. With the proposed bank strike scheduled immediately after the weekend, customers could otherwise have faced several consecutive days with limited access to physical branch services. The Sunday opening has consequently been planned to provide an additional opportunity to complete important banking transactions before the strike.
Among the public sector banks operating today are State Bank of India, Canara Bank, Bank of Baroda, Punjab National Bank, Bank of India, Indian Bank, Union Bank of India, Bank of Maharashtra, UCO Bank, Central Bank of India, Indian Overseas Bank and Punjab & Sind Bank.
The arrangement also covers 28 regional rural banks across the country. These include Andhra Pradesh Grameena Bank, Arunachal Pradesh Rural Bank, Assam Gramin Bank, Bihar Gramin Bank, Chhattisgarh Gramin Bank, Gujarat Gramin Bank, Haryana Gramin Bank, Himachal Pradesh Gramin Bank, Jammu and Kashmir Grameen Bank, Jharkhand Gramin Bank, Karnataka Grameena Bank, Kerala Grameena Bank, Madhya Pradesh Gramin Bank, Maharashtra Gramin Bank, Manipur Rural Bank, Meghalaya Rural Bank, Mizoram Rural Bank, Nagaland Rural Bank, Odisha Grameen Bank, Puducherry Grama Bank, Punjab Gramin Bank, Rajasthan Gramin Bank, Tamil Nadu Grama Bank, Telangana Grameena Bank, Tripura Gramin Bank, Uttar Pradesh Gramin Bank, Uttarakhand Gramin Bank and West Bengal Gramin Bank.
However, the Sunday opening arrangement does not automatically extend to private sector banks.
The special Sunday banking arrangement comes ahead of the proposed three-day nationwide strike called by the United Forum of Bank Unions (UFBU) and other bank unions from September 28 to September 30.

Bengaluru: Elderly man killed in elephant attack; forest department launches search

Three FIRs filed over violent clashes at Kolkata SRFTI campus

Sanjay Raut alleges extortion racket within Maha FDA, demands clean up

SC takes suo motu cognisance of recurring rape, sexual assault cases in Delhi-NCR

JP Nadda hits out at Cong, INDIA bloc over SIR row; accuses Oppn of spreading confusion, anarchy

Four more Indian nationals rescued in Nepal, 120 cross safely from China: MEA

Gift to President Putin part of PM Modi bid to globally display India’s heritage

PM Modi’s warm camaraderie with Putin, Xi on full display at BRICS Summit

7.8 pc GDP growth reflects country’s progress: Maha CM Fadnavis, Dy CM Shinde

BMC takes action against Mumbai Central Orchid City Mall; mall shut down.
-

 Crime4 years ago
Class 10 student jumps to death in Jaipur
-

 Maharashtra2 years ago
Mumbai Local Train Update: Central Railway’s New Timetable Comes Into Effect; Check Full List Of Revised Timings & Stations
-

 Maharashtra2 years ago
Mumbai To Go Toll-Free Tonight! Maharashtra Govt Announces Complete Toll Waiver For Light Motor Vehicles At All 5 Entry Points Of City
-

 Maharashtra2 years ago
False photo of Imtiaz Jaleel’s rally, exposing the fooling conspiracy
-

 National News2 years ago
Ministry of Railways rolls out Special Drive 4.0 with focus on digitisation, cleanliness, inclusiveness and grievance redressal
-

 Maharashtra2 years ago
Maharashtra Elections 2024: Mumbai Metro & BEST Services Extended Till Midnight On Voting Day
-

 National News2 years ago
J&K: 4 Jawans Killed, 28 Injured After Bus Carrying BSF Personnel For Poll Duty Falls Into Gorge In Budgam; Terrifying Visuals Surface
-

 Crime2 years ago
Baba Siddique Murder: Mumbai Police Unable To Get Lawrence Bishnoi Custody Due To Home Ministry Order, Says Report