Business
Budget 2022: Experts exhort Centre to regulate crypto trades
Even as Union Finance minister Nirmala Sitharaman is set to present the annual Budget on February 1, experts have called for regulation of cryptocurrencies and exhorted the government to treat them as capital assets with a “reasonable” tax regime.
While the sector has grown exponentially over the last few years in India with buying, selling of the digital currencies and altcoins and establishing cryptocurrency exchanges being legal, the government is yet to bring in a law that regulates the sector.
The government was expected to introduce a Bill titled “The Cryptocurrency and Regulation of Official Digital Currency Bill, 2021” to regulate cryptocurrencies in the Winter session of the Parliament but did not do so. It is now expected to be tabled in the Parliament during the Budget session that starts on January 1 and ends on April 8.
Pratik Gauri, CEO, and Founder, 5ire said the government has a responsibility to protect people from investments that are sensationalized, and while risk-taking is every investor’s right, a measured hand where investment and holding parties responsible go hand-in-hand.
“Laissez-faire has never worked in populations where every rupee is hard-earned and we are a nation of hard-earners. Even in terms of governance, the Indian government is looking long and hard at accountability. So, taxation and regulation of investment falls under its purview and I think, thus far the government has done a remarkable job of balancing the need to encourage investment for innovation and the restriction on gaining from wild speculation,” he said.
He added that all gains from cryptocurrencies are taxed heavily across the globe and that asking to pay a fair share of taxes on the gains in crypto markets is just part of the puzzle.
Prime Minister Narendra Modi, while virtually addressing a summit of the World Economic Forum on January 17, had called for a synchronized global action to regulate cryptocurrencies. The Reserve Bank of India has publicly favored a ban on private cryptocurrencies. The crypto assets in India are currently estimated at around Rs 45,000 crore with about 15 million investors.
The risk in the widespread adoption of crypto is that poor AML and fraud practices are heavily present in the crypto exchange market. The reasons are multifold: Enhanced Due Diligence (EDD) is not required on crypto exchanges or ATMs at this time.
Raj Kapoor, Founder – India Blockchain Alliance and Chief Growth Officer at Chainsense LTD, said an alignment with the FATF framework would also provide crypto for a clearer framework on performing AML compliance, and to prepare to use this to inform your risk assessment and procedures.
The Customer Due Diligence (CDD) scanner to detect customer identification, especially for scanning high-risk customers would then be in place as well.
Ravi S. Raghavan, Partner, Tax and Private Client Group at Majmudar & Partners says cryptos should be treated as capital assets and reasonable tax regime such as a levy of 18 per cent GST on fee collected by exchanges for enabling buying and selling cryptos; and Investor profits to be either taxed as – short term capital gains (for cryptos held for less than 36 months) at 30 per cent; or long term capital gains tax (for cryptos held for more than 36 months) at 20 per cent that is similar to trading and investment in securities.
“Reporting procedures in income tax returns and whether tax withholdings are applicable (beyond prescribed thresholds) should be explained in the form of an FAQ by the Central Board of Direct Taxes in due course to avoid any tax litigation,” he said.
He added that crypto trading should be considered by the government as speculative transactions and no losses arising from crypto sales be allowed to be carried forward and set off against other business profits or salary income of the concerned taxpayer.
Regulating cryptocurrencies by bringing it under the IT Act will make it a part of the investment choices and while most investors do not have a problem with taxation, they seek clarity and consistency of taxes.
“Anything that is banned never goes away, it just goes underground and the govt misses out on the tax revenues. Also regulating it would ensure that all loopholes are plugged and people don’t feel the need to evade taxes,” Kunal Verma director and creative head of Yunometa Pte limited said.


India’s strong economic growth trajectory and the implementation of the India-EFTA Trade and Economic Partnership Agreement (TEPA) are creating significant opportunities for Norwegian investors, particularly in manufacturing, renewable energy, infrastructure, financial services and the digital economy, according to industry insights.
With GDP growth projected to remain around 6.5 per cent annually through 2030, India is widely expected to become the world’s third-largest economy by the end of the decade, according to EY India report.
Analysts attribute this outlook to strong domestic consumption, rising investments, ongoing infrastructure development and reforms aimed at improving the ease of doing business.
The India-EFTA TEPA, which came into effect in October 2025, is being viewed as a major milestone in India-Norway economic relations.
The agreement seeks to promote trade liberalisation, facilitate investment flows and deepen cooperation in areas such as innovation, sustainability and advanced technologies.
The pact includes investment commitments of $100 billion over 15 years and is expected to support the creation of one million direct jobs in India, aligning with the country’s broader goals of expanding manufacturing capacity and strengthening its position in global value chains.
Industry experts believe the agreement creates a strong framework for Norwegian companies to expand their presence in India by combining Norway’s expertise in technology, sustainability and capital-intensive industries with India’s large market and growth ambitions.
Several sectors have been identified as priority areas for collaboration, including manufacturing, renewable energy, oil and gas, maritime services, seafood processing, information and communication technology (ICT), fintech and financial services. These industries are expected to benefit from increasing bilateral cooperation under the TEPA framework.
The rapid expansion of India’s digital economy and digital payments ecosystem is also creating opportunities for Norwegian companies seeking exposure to one of the world’s largest and fastest-growing consumer markets.
At the same time, India’s policy measures aimed at attracting foreign investment are expected to provide a supportive environment for long-term investors, as per the report.
Business
Delhi protests put business worth Rs 400 crore at daily risk, exposure may reach Rs 4,000 crore in 10 days: CAIT

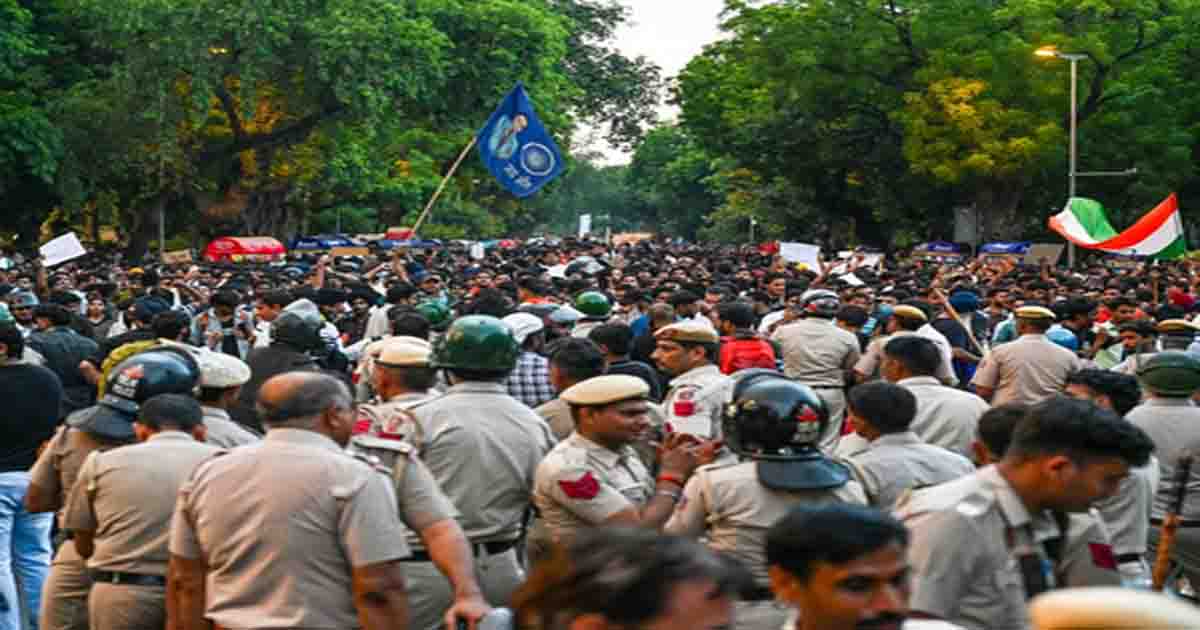
Protests in Delhi could put business transactions worth over Rs 400 crore at risk every day, with the potential exposure reaching Rs 4,000 crore over ten days if disruptions persist, Confederation of All India Traders (CAIT) Secretary General and Chandni Chowk MP Praveen Khandelwal said on Sunday.
Expressing concern over the economic impact of prolonged protests, Khandelwal said disruptions to traffic, transportation, customer movement and market accessibility could significantly affect the capital’s commercial activities, particularly during the crucial festive and wedding season.
He clarified that the figures represent indicative estimates of business activity at risk and not verified actual losses.
According to Khandelwal, Delhi’s estimated average daily business turnover stands at approximately Rs 2,200 crore. Even a 10 per cent decline in business activity could affect transactions worth Rs 220 crore daily, while a 15 per cent decline could put Rs 330 crore at risk. If the disruption reduces business activity by 20 per cent, the amount at risk could rise to Rs 440 crore per day.
Based on these estimates, the cumulative exposure could approach Rs 4,000 crore over ten days if disruptions continue at the higher end of the projected range.
Khandelwal emphasised that while the Constitution guarantees citizens the right to freedom of speech and peaceful assembly, traders must also be able to conduct their businesses and earn their livelihoods without avoidable disruptions.
“Delhi is not merely the national capital; it is one of the country’s most important centres of wholesale distribution, retail trade and commercial activity. Its markets connect manufacturers, distributors, retailers and consumers across India. Any prolonged disruption in Delhi therefore has a cascading impact on supply chains, business transactions and livelihoods far beyond the city,” Khandelwal said.
“The right to protest and the right to trade are both integral to a functioning democracy. Protecting one should not mean disregarding the other. The larger public interest demands a responsible approach in which democratic expression, the rule of law, economic activity and the livelihood of millions of people are all duly respected,” Khandelwal noted.
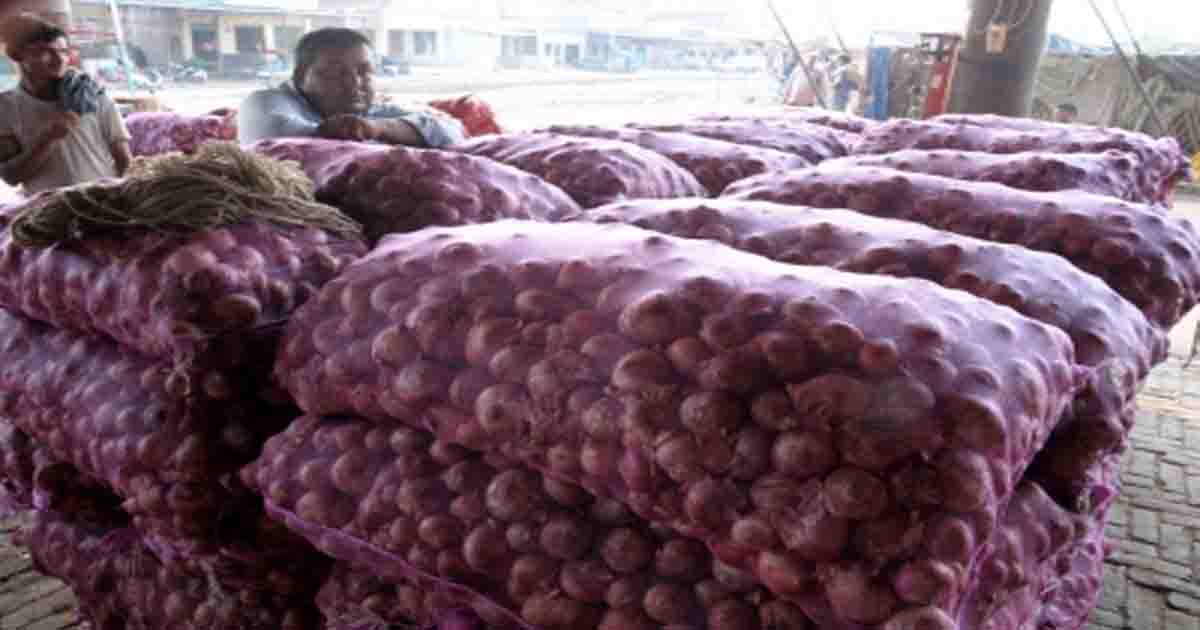
Salespersons at ration shops run by cooperative societies will receive an incentive of Rs 2 for every kilogram of onions sold under an initiative aimed at controlling retail prices and ensuring access to quality produce at reasonable rates.
The incentive was announced in a procedural order issued by Registrar of Cooperative Societies, Latha. It recognises the additional responsibilities undertaken by salespersons handling onion distribution alongside their regular ration shop duties.
According to the order, onions were procured in three phases from the National Agricultural Cooperative Marketing Federation of India (NAFED) and the National Cooperative Consumers’ Federation of India (NCCF). The procurement was undertaken to help check rising onion prices in the open market. The onions are being sold to the public through ration shops operated by cooperative societies.
The arrangement is intended to make quality onions available at fair prices while using the existing cooperative distribution network to reach consumers.
Under the order, the incentive payable to each salesperson will depend on the quantity of onions sold. The prescribed rate is Rs 2 per kilogram, linking payment directly to the volume handled through sales at the participating shops.
The Registrar’s order lists several additional tasks associated with the initiative. These include receiving onion consignments, storing the produce, sorting it, weighing quantities for customers, conducting sales and maintaining the related sales accounts. These responsibilities involve work beyond the routine distribution of ration commodities.
The incentive is intended to encourage salespersons to undertake the additional duties required to carry out onion sales through cooperative outlets. The amount due to eligible salespersons will be credited directly to their bank accounts through the Electronic Clearing Service (ECS), according to the order.
Payments will therefore be made through bank transfers based on the quantity sold. The measure combines consumer relief with an incentive for the staff responsible for implementing the sales programme.
While the procurement and distribution arrangement seeks to contain the impact of higher market prices, the additional payment acknowledges the work involved at the retail level. The order specifies a uniform incentive rate for onion sales conducted through the participating cooperative ration shops.

FairPoint: The protests are loud, but where is the money coming from?

Elephant seriously injures mahout, creates panic in Varanasi Ramnagar; over 200 police personnel deployed

CM Adhikari to meet families of Kolkata stampede victims on October 20-21

CBI questions Urmila Sanawar in connection with Ankita Bhandari murder case

Akshay Kumar meets Uttarakhand CM Pushkar Singh Dhami, talk about film Policy in the state

Rahul, Cong ecosystem want to force regime change: BJP after Neha Bora praises B’desh Gen-Z protest

BJP pays tribute to ex-President Abdul Kalam, recalls his enduring influence on generations of India’s youth

Attack on democratic rights: INDIA Bloc leaders on detentions of anti-ECI protestors

INDIA bloc begins protest march against ECI

Maha Congress stages agitation against Gyanesh Kumar
-

 Crime4 years ago
Class 10 student jumps to death in Jaipur
-

 Maharashtra2 years ago
Mumbai Local Train Update: Central Railway’s New Timetable Comes Into Effect; Check Full List Of Revised Timings & Stations
-

 Maharashtra2 years ago
Mumbai To Go Toll-Free Tonight! Maharashtra Govt Announces Complete Toll Waiver For Light Motor Vehicles At All 5 Entry Points Of City
-

 Maharashtra2 years ago
False photo of Imtiaz Jaleel’s rally, exposing the fooling conspiracy
-

 National News2 years ago
Ministry of Railways rolls out Special Drive 4.0 with focus on digitisation, cleanliness, inclusiveness and grievance redressal
-

 Maharashtra2 years ago
Maharashtra Elections 2024: Mumbai Metro & BEST Services Extended Till Midnight On Voting Day
-

 National News2 years ago
J&K: 4 Jawans Killed, 28 Injured After Bus Carrying BSF Personnel For Poll Duty Falls Into Gorge In Budgam; Terrifying Visuals Surface
-

 Crime2 years ago
Baba Siddique Murder: Mumbai Police Unable To Get Lawrence Bishnoi Custody Due To Home Ministry Order, Says Report