Business
Mukesh Ambani with a net worth of $ 92.7 billion tops 2021 Forbes list of India’s richest

A soaring stock market propelled the combined wealth of members of the 2021 Forbes list of India’s 100 Richest to a record US$775 billion, after adding $257 billion — a 50 per cent rise — in the past 12 months.
In this bumper year, more than 80 per cent of the listees saw their fortunes increase, with 61 adding $1 billion or more.
At the top of the list is Mukesh Ambani, India’s richest person since 2008, with a net worth of $92.7 billion.
Ambani recently outlined plans to pivot into renewable energy with a $10 billion investment by his Reliance Industries.
Close to a fifth of the increase in the collective wealth of India’s 100 richest came from infrastructure tycoon Gautam Adani, who ranks No. 2 for the third year in a row. Adani, who is the biggest gainer in both percentage and dollar terms, nearly tripled his fortune to $74.8 billion from $25.2 billion previously, as shares of all his listed companies soared.
At No. 3 with $31 billion is Shiv Nadar, founder of software giant HCL Technologies, who saw a $10.6 billion boost in his net worth from the country’s buoyant tech sector.
Retailing magnate Radhakishan Damani retained the fourth spot with his net worth nearly doubling to $29.4 billion from $15.4 billion, as his supermarket chain Avenue Supermarts opened 22 new stores in the fiscal year ending March.
India has administered over 870 million Covid-19 vaccine shots to date, thanks partly to Serum Institute of India, founded by vaccine billionaire Cyrus Poonawalla, who moves into the top five with a net worth of $19 billion. His privately held company makes Covishield under license from AstraZeneca and has other Covid-19 vaccines under development.
India’s recovery from a deadly second wave of Covid-19, which broke out earlier this year, restored investor confidence in the world’s sixth-largest economy.
There are six newcomers on this year’s list, with half of them from the booming chemicals sector. They include Ashok Boob (No. 93, $2.3 billion) whose Clean Science and Technology listed in July; Deepak Mehta (No. 97, $2.05 billion) of Deepak Nitrite and Yogesh Kothari (No. 100, $1.94 billion) of Alkyl Amines Chemicals. Arvind Lal (No. 87, $2.55 billion), the executive chairman of diagnostics chain Dr Lal PathLabs, also debuted on the list after a pandemic-induced surge in testing caused shares of his company to double in the past year.
The country’s IPO rush returned property magnate and politician Mangal Prabhat Lodha (No. 42, $4.5 billion) to the ranks, following the April listing of his Macrotech Developers. Among the four other returnees is Prathap Reddy (No. 88, $2.53 billion), whose listed hospital chain Apollo Hospitals Enterprise has been testing and treating Covid-19 patients.
Eleven listees from last year dropped off, given the increased cut-off for gaining entry to this year’s list. The minimum amount required to make this year’s list was $1.94 billion, up from $1.33 billion last year.
Naazneen Karmali, Asia Wealth Editor and India Editor of Forbes Asia, said: “This year’s list reflects India’s resilience and can-do spirit even as Covid-19 extracted a heavy toll on both lives and livelihoods. Hopes of a V-shaped recovery fueled a stock market rally that propelled the fortunes of India’s wealthiest to new heights. With the minimum net worth to make the ranks approaching $2 billion, the top 100 club is getting more exclusive.”


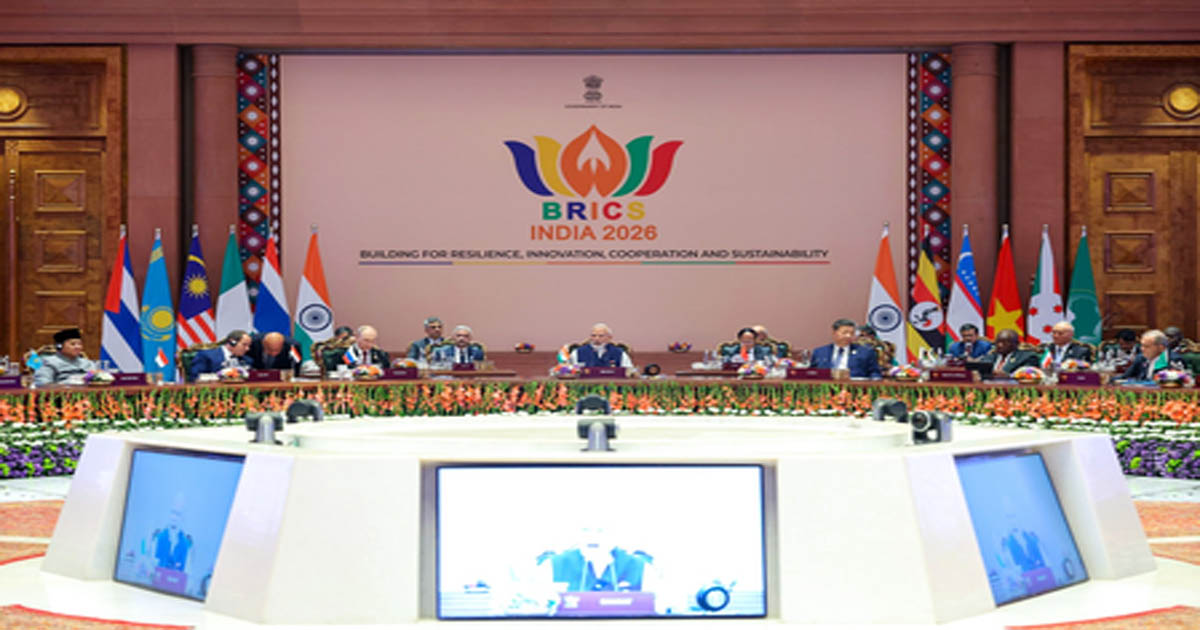
New Delhi, Sep 14: The United Arab Emirates (UAE) and India are broadening a strategic and economic partnership that serves as “an effective model of cooperation within BRICS,” a new report has said.
The partnership is built on a foundation of historic ties, shared interests and major projects that promote trade, investment and logistics connectivity between markets, the report from Gulf Today said.
“The growing UAE-India partnership, reflected in expanding trade, increasingly integrated logistics corridors and cooperation in investment and innovation, provides a practical model of the UAE’s role within BRICS,” the report said.
Further, the partnership also proves UAE’s commitment to exchanging expertise and perspectives and building more integrated and sustainable economic partnerships.
Bilateral trade reached $101.25 billion in FY26, marking the second consecutive year in which trade between the two countries exceeded $100 billion. The UAE and India have set a target to raise bilateral trade to $200 billion by 2032.
The partnership is being advanced through initiatives such as Bharat Mart, the Virtual Trade Corridor and cooperation under the India‑Middle East‑Europe Economic Corridor (IMEC).
“These initiatives are helping strengthen supply chain integration and create new routes for trade and investment flows between the two countries and global markets,” the report noted.
The UAE-India Comprehensive Economic Partnership Agreement (CEPA), operational since 2022 was hailed as the first agreement of its kind concluded by the UAE. The agreement has bolstered the flow of goods, services and investment and expanded opportunities for the private sector in both countries.
United Arab Emirates and China were the largest destinations within BRICS, together accounting for 88.50 per cent of India’s electronics exports to the grouping.
The number of Indian companies registered as active members of Dubai Chamber reached 85,841 by the end of June 2026 after 7,579 new Indian firms joined in the first half of the year, marking a year‑on‑year increase of 15 per cent, another report said.
Mumbai, Sep 14: The Nifty could climb to 26,200 by December 2026, implying an upside of around 12 per cent from current levels, as Bank of America (BofA) Securities has turned constructive on Indian equities after maintaining a cautious stance for nearly two years.
In its latest strategy report, BofA said it had remained cautious on Indian stocks since August 2024 and had identified eight key risks that could keep the market volatile. However, five of those risks have either already played out or have been largely priced into the market, prompting the brokerage to adopt a more positive stance.
BofA said the three remaining risks could create around 7 per cent downside for the Nifty 50 in its bear-case scenario. In its base case, however, the brokerage sees the index reaching 26,200 by December 2026.
According to BofA, the remaining risks are expected to peak by October 2026, potentially creating room for a sustained market recovery from November.
One of the key risks identified earlier was a sharp rise in crude oil prices above $100 a barrel, compared with BofA’s fourth-quarter 2026 estimate of $81 a barrel. The brokerage noted that crude prices have reversed from the $100-a-barrel level seven times over the past seven months.
The rupee was another concern, although BofA said recent inflows of around $136 billion should provide support to the currency and maintained an appreciation bias.
Weak monsoon conditions were also among the risks, with the current rainfall deficit at 13 per cent, close to the 15 per cent worst-case scenario previously projected by the brokerage.
BofA also expects limited further acceleration in aluminium and copper prices. On monetary policy, its economist expects the Reserve Bank of India to raise the policy rate by 25 basis points by December 2026, compared with around 45 basis points currently priced by swap markets.
The three remaining risks include a possible surge in primary market issuances, with around $30 billion expected between September and December and issuance activity likely to peak in October. Another risk is the possibility of 75 basis points of Federal Reserve rate hikes, compared with around 35 basis points currently priced by markets. Over the longer term, BofA also flagged the potential impact of artificial intelligence-led disruption on employment in India.
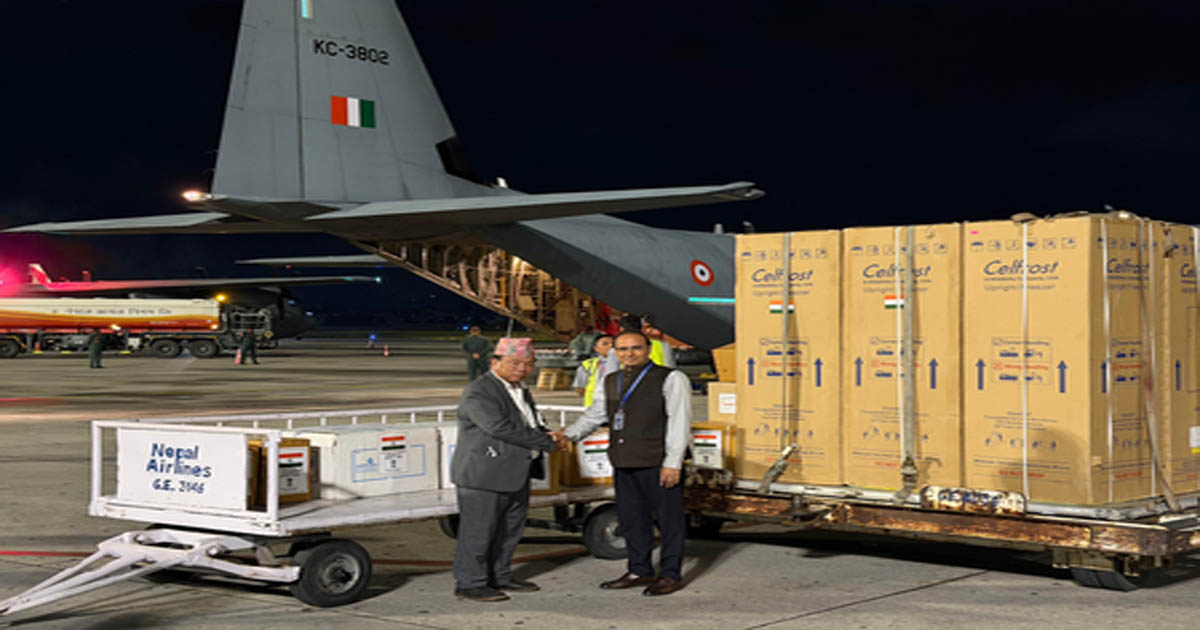
New Delhi, Sep 14: India has approved a proposal to supply power to Nepal for 18 hours a day till December 31 this year, following the extensive damage caused to the Himalayan country’s hydropower projects in the devastating flash floods, an official statement said on Monday.
“The Ministry of Power has accorded approval for the export of power, for 18 hours a day to Nepal Electricity Authority till December 31, 2026,” according to the statement.
Approval has been given for up to 600MW of export through Muzaffarpur-Dhalkebar 400 kV D/c line and up to 54 MW through Tanakpur-Mahendranagar 132 kV S/c line. The quantum of power to be exported from January 2027 will be reviewed in December, 2026, the statement said.
The recent floods have caused significant damage to hydropower infrastructure in Nepal, reducing its domestic power generation capacity and creating an additional requirement for electricity.
The approval will help Nepal meet its power requirements during this difficult period and further strengthen the close and longstanding energy cooperation between India and Nepal, the statement explained.
“India remains committed to supporting Nepal and strengthening bilateral cooperation in the energy sector,” the statement added.
India also intensified its humanitarian assistance to Nepal in the wake of the floods, delivering relief material and deploying personnel to support search, rescue, and forensic operations. Indian Air Force aircraft were used to carry relief and rescue supplies to Kathmandu.
The country also dispatched specialised technical gear, including mud rescue suits, gas detectors, breathing apparatus, inflatable walkways, portable generators, lighting towers, and dewatering pumps. India has provided DNA kits, reagents, and equipment for DNA profiling to aid in victim identification.
Meanwhile, the death toll from flash floods has risen to 1,386, with more bodies recovered from eight affected districts.
The floods, triggered by an ice-rock avalanche near the Nepal-Tibet border on August 26, devastated towns and villages in northern and central Nepal.
According to the National Disaster Risk Reduction and Management Authority, 104 of the recovered bodies have so far been identified and handed over to families. Around 5,130 people are still reported missing.
Security forces continue search and rescue operations. More than 13,700 people have been rescued so far, while 339 people are undergoing treatment in hospitals.

Yemen Houthis claim major missile, drone attack on Saudi air base

PM Modi speaking Hindi globally fills us with pride: CM Fadnavis

Iran says Oman meeting postponed at Saudi Arabia’s request

Meeting between Iran, Gulf states scheduled in Oman postponed

India‑UAE ties grow into a model for BRICS collaboration: Report

Four more Indian nationals rescued in Nepal, 120 cross safely from China: MEA

Nepal floods: First batch of 106 stranded Maharashtra tourists reaches India; 84 more expected today (Ld)

Gift to President Putin part of PM Modi bid to globally display India’s heritage

India, Brazil sign ICT MoU to deepen digital, telecom cooperation

Maharashtra: 17-year-old boy dies by suicide on Raksha Bandhan after emotional social media posts
-

 Crime4 years ago
Class 10 student jumps to death in Jaipur
-

 Maharashtra2 years ago
Mumbai Local Train Update: Central Railway’s New Timetable Comes Into Effect; Check Full List Of Revised Timings & Stations
-

 Maharashtra2 years ago
Mumbai To Go Toll-Free Tonight! Maharashtra Govt Announces Complete Toll Waiver For Light Motor Vehicles At All 5 Entry Points Of City
-

 Maharashtra2 years ago
False photo of Imtiaz Jaleel’s rally, exposing the fooling conspiracy
-

 National News2 years ago
Ministry of Railways rolls out Special Drive 4.0 with focus on digitisation, cleanliness, inclusiveness and grievance redressal
-

 Maharashtra2 years ago
Maharashtra Elections 2024: Mumbai Metro & BEST Services Extended Till Midnight On Voting Day
-

 National News2 years ago
J&K: 4 Jawans Killed, 28 Injured After Bus Carrying BSF Personnel For Poll Duty Falls Into Gorge In Budgam; Terrifying Visuals Surface
-

 Crime2 years ago
Baba Siddique Murder: Mumbai Police Unable To Get Lawrence Bishnoi Custody Due To Home Ministry Order, Says Report