Business
Trade pacts with UAE, Australia will fuel economic growth: Finance Minister
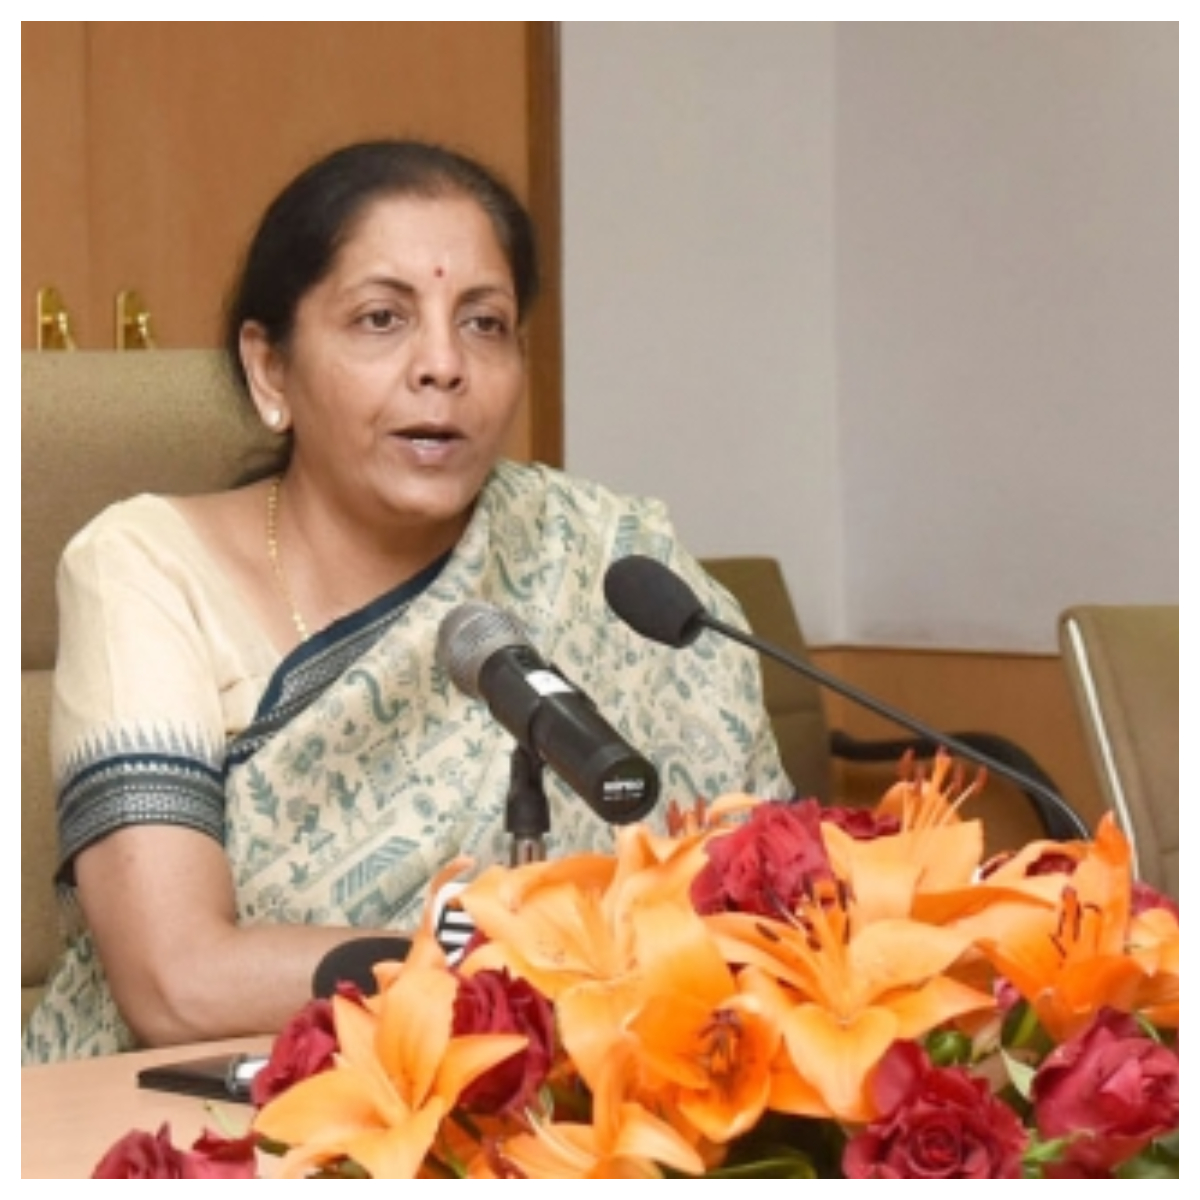
Finance Minister Nirmala Sitharaman said on Tuesday the country’s trade pacts with the UAE and Australia will chart the way for economic growth.
Speaking at the stakeholders’ outreach programme on India-UAE CEPA and India-Australia ECTA here, Sitharaman said awareness events about these pacts are happening across the country.
She also said the Director General of Foreign Trade (DGFT) has been asked to translate the details of the trade pacts in Tamil and share them with the media and stakeholders.
Tamil Nadu has a long-time connection with the leather sector, and the industry has achieved modernisation, Sitharaman said, as she went on to add that Tamil Nadu has been a frontrunner in trade for a long time.
She urged entrepreneurs to know the features of these agreements and make best use of them.
“If you want any support in connection with the agreements, feel free to convey it to us,” she added.
“The industry should equip itself to cater to the changing tastes and preferences of consumers post Covid. Access the available markets that are part of the agreements,” she said.
According to Sitharaman, when Prime Minister Narendra Modi visited the UAE some years back, the Royal family promised $75 billion worth investments in India.
Sitharaman added that a formal agreement has also been signed, and entrepreneurs should scale up their businesses to get share from the investments.
“We are now dependent on one country for APIs (active pharmaceutical ingredients). So enough investments need to be made after much thought. I request the state government to invite raw material makers to invest here. We should not depend on others for our raw materials. Backward and forward industries should be supported by the governments,” she said.
On the trade pact with Australia, Sitharaman said it is for the well-being of the Indo-Pacific economy.
While there are many hurdles because of the Russia-Ukraine war, there are also opportunities since their exports are hit, she said.
Speaking at the event, Union Minister of State for Commerce and Industry, Anupriya Patel, said all efforts are being made to reach out to the stakeholders all over the country to explain the details of the trade agreements.
“The India-UAE trade agreement was concluded in record time. India is the second largest trading partner of the UAE. Several benefits will flow out of the comprehensive agreement between the two countries. There is huge scope and there are so many employment opportunities to be created. Bilateral trade will double in the next five years,” Patel said.
“The India-Australia agreement is a clear signal to the other developed economies to partner with India,” she added.
Union Minister of State for Fisheries, Animal Husbandry & Dairying, L.A Murugan, congratulated the Department of Commerce and Industry for organising the awareness event in Chennai.
“We are making huge exports in the marine sector. For the first time in history, Rs 20,000 crore was announced for fisheries under the Pradhan Mantri Matsya Sampada Yojana (PMMSY) by Nirmala Sitharaman,” he said.
Murugan also said that Rs 7,500 crore was allocated for fisheries infrastructure development by Sitharaman.
Despite the challenges posed by the pandemic, India’s maritime sector registered growth, Murugan said, adding that seafood exports will touch Rs 1 lakh crore before 2025.
Tamil Nadu Minister for MSME, T.M. Anbarasan, Consul General of Australia, Chennai, Sarah Kirlew, industry leaders from various sectors and other stakeholders took part in the event.


There are early indications of foreign institutional investors (FIIs) turning towards India markets amid the AI stock upheavals globally, analysts said on Sunday.
They said it is too early to say that this is a trend reversal, but early signs are positive. During the last four trading days ending on October 30, FIIs were buyers in three days in the cash market.
There are many factors that might have triggered this change in stance.
“One, the US Fed holding rates are a positive for equity markets globally. Second, the valuations in Indian markets, particularly in large caps, have become very attractive. Three, perhaps this is more important, there are clear indications of sustained momentum in economic growth in India,” said Dr. VK Vijayakumar, Chief Investment Strategist, Geojit Investments Ltd.
The surge in credit growth is impressive and indicative of robust growth ahead. Credit grew by 19.1 per cent in September (year-on-year). Credit growth to industry is at 19.5 per cent, and services are at 28.3 per cent.
There are signs of improvement in industrial capex, too. Another factor is the weakening of the AI trade globally. This change in stance of FPIs helped Nifty reclaim the 23,000 level, said the analyst.
Even while selling in large-cap financials, FIIs have been systematically accumulating stocks in pharmaceuticals and healthcare and select digital platform companies.
FIIs have net-sold $59 billion worth Indian equities in the 24 months leading up to September (about $64 billion with October 2026 month-to-date), and rolling 12-month outflows hit a record $40 billion in June 2026.
“FIIs return when oil breaks, and flows then confirm. The US midterms (November 3) and the Iran path decide when,” according to a note by JM Financial Institutional Securities.
FIIs sold a net $14.9 billion in FY25, $21.9 billion in FY26 and $17.7 billion with October 2026 month-to-date. Before this, FIIs had never sold for more than two straight years.
Business
CTI to launch poster campaign in 20 markets around Delhi’s Ramlila Maidan; urges INDIA Bloc to cancel rally

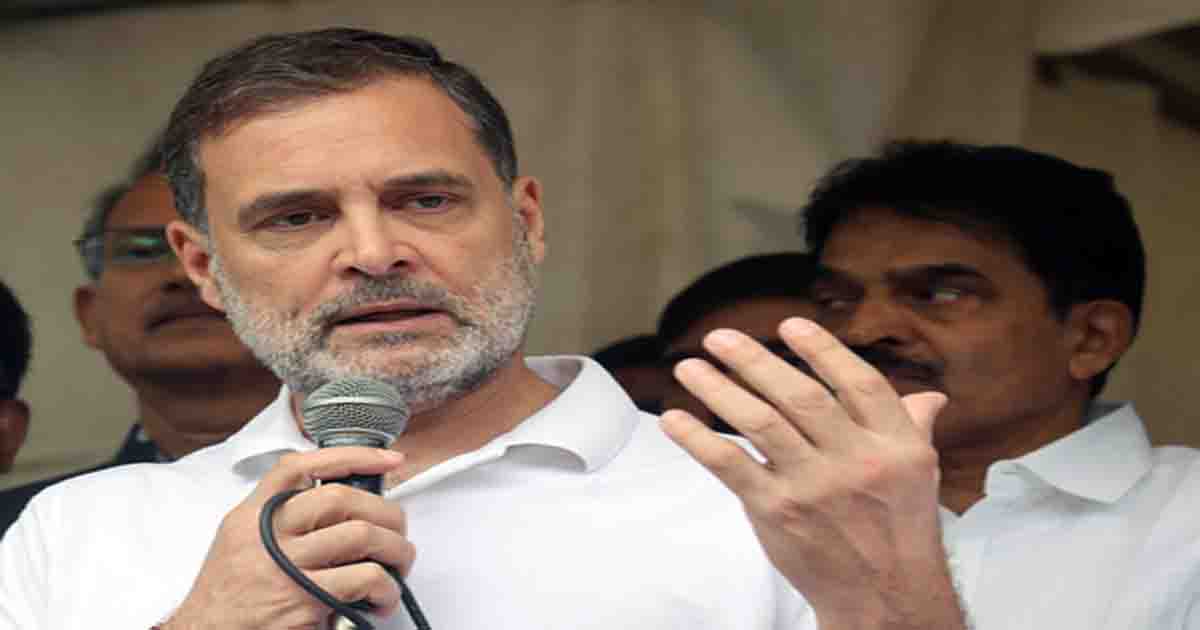
With Diwali approaching, some Delhi traders have expressed concern over the proposed rally at Ramlila Maidan, with the Chamber of Trade and Industry (CTI) on Saturday launching a massive poster campaign urging that business activities in major markets should not be disrupted during the peak festive season and urging the INDIA Bloc to cancel its ‘Chalo Delhi’ rally.
The CTI, an apex body representing traders and entrepreneurs in Delhi, appealed to Leader of the Opposition in the Lok Sabha, Rahul Gandhi, saying that traders’ businesses also run on mutual trust, love and affection with their customers.
“You often say that you run shops of love in the market of hatred. Our shops also run on the basis of mutual trust, love and affection with our customers. Therefore, we humbly request you not to sacrifice our shops of love and business for a rally during the peak season of India’s biggest festival, Diwali,” the CTI said.
CTI has announced that starting on Saturday, these posters will be put up in 20 major wholesale markets within a 5-km radius of Ramlila Maidan.
CTI Chairman Brijesh Goyal said the poster campaign was intended to highlight the concerns of traders whose businesses could be affected by traffic restrictions and congestion around the rally venue.
“You talked about opening ‘shops of love’ during the Bharat Jodo Yatra, but in Delhi, our 300-year-old shops of love are being closed because of the rally,” Goyal said.
He cited businesses ranging from the famous parantha shops of Chandni Chowk and spice traders of Khari Baoli to bangle and bindi sellers in Sadar Bazaar, lehenga shops in Chandni Chowk and other traditional establishments.
“Each shop supports the families of 10 to 20 people,” he added.
The CTI said it would put up posters in major wholesale markets located within a five-km radius of Ramlila Maidan.
These include Chandni Chowk, Sadar Bazaar, Khari Baoli, Bhagirath Palace, Naya Bazaar, Chawri Bazaar, Kashmiri Gate, Daryaganj, Connaught Place, Karol Bagh, Nabi Karim, Paharganj, Ajmeri Gate, Lahori Gate, Janpath, Palika Bazaar, Ballimaran and Kinari Bazaar.
According to the traders’ body, a large gathering at Ramlila Maidan could lead to traffic congestion and restrictions in the surrounding markets.
Goyal said the proposed rally, scheduled just days before Dhanteras, could affect festive business activities.
He expressed concern that the arrival of a large number of people and around 20,000 vehicles could result in traffic jams across central Delhi and disrupt commercial activity.
The CTI claimed that the festive business of 2 million traders and the livelihoods of 7.5 million people dependent on these markets could be affected if restrictions were imposed during the peak Diwali shopping period.
Axis Trustee Services Limited, the trustee for the Additional Tier 1 (AT1) bonds issued by Yes Bank, called upon the private sector lender to reinstate the bonds and take necessary corporate actions within three days, failing which the former would initiate contempt proceedings in Supreme Court against the bank.
The trustee said in a filing that non-compliance will constitute “wilful disobedience by the lender of the Supreme Court’s October 15 judgment”.
Yes Bank said it had responded to the trustee, acknowledging the Supreme Court judgment and reiterating that it was fully committed to acting in accordance with the ruling and applicable law, according to an exchange filing.
The Bank replied to the Trustee that it is cognisant of the matters and is examining the SC Judgment and its implications in detail.
“The Bank will take all such steps and measures as are necessary and permissible under applicable law,” Yes Bank said.
“Should the Bank fail to comply with the said judgment as called upon above within the stipulated period, we shall be constrained to initiate proceedings for contempt before the SC, against the Bank and its directors and officers responsible for compliance with the said judgment, without any further notice, entirely at the Bank’s risk as to costs and consequences,” Axis Trustee said in its letter to Yes Bank.
Bank has merely stated that it is “examining the judgment in detail, including evaluating all available options and suitable actions or steps going forward,” the trustee said, adding that under the guise of evaluating its options, the bank should not withhold compliance with the said judgment.
Yes Bank rejected the allegation in its response letter, clarifying that it had not wilfully disobeyed the court.
“The Bank does not accept the characterisation in your Letter of its conduct as wilful disobedience and the assertions in your Letter are baseless and without merit,” it said.
The Supreme Court had, on October 15, upheld the Bombay High Court’s decision to set aside Yes Bank’s Rs 8,415 crore AT1 bond write-off carried out in March 2020. It ruled that the bank’s administrator had acted outside its authority and the applicable regulatory framework.
Axis Trustee challenged the decision of the then administrator of Yes Bank to write down the AT1 bonds in March 2020 before the Bombay High Court.

Zaheer Iqbal opens up about challenges of playing an obsessive lover in ‘Tu Hai Meri Kiran’

SP leader Azam Khan sent to 14 days of judicial custody in money laundering case

Trump flags Iran targets as talks continue

Congress wishes to run democracy according to the law of Gandhi family, says BJP chief Nitin Nabin

PGIMER Director visits six-year-old girl injured in Panchkula school incident, entire treatment to be provided free

Rahul, Cong ecosystem want to force regime change: BJP after Neha Bora praises B’desh Gen-Z protest

Attack on democratic rights: INDIA Bloc leaders on detentions of anti-ECI protestors

BJP pays tribute to ex-President Abdul Kalam, recalls his enduring influence on generations of India’s youth

INDIA bloc begins protest march against ECI

Online betting: ED conducts searches at 20 premises in Mumbai, Pune, Hyderabad
-

 Crime4 years ago
Class 10 student jumps to death in Jaipur
-

 Maharashtra2 years ago
Mumbai Local Train Update: Central Railway’s New Timetable Comes Into Effect; Check Full List Of Revised Timings & Stations
-

 Maharashtra2 years ago
Mumbai To Go Toll-Free Tonight! Maharashtra Govt Announces Complete Toll Waiver For Light Motor Vehicles At All 5 Entry Points Of City
-

 Maharashtra2 years ago
False photo of Imtiaz Jaleel’s rally, exposing the fooling conspiracy
-

 National News2 years ago
Ministry of Railways rolls out Special Drive 4.0 with focus on digitisation, cleanliness, inclusiveness and grievance redressal
-

 Maharashtra2 years ago
Maharashtra Elections 2024: Mumbai Metro & BEST Services Extended Till Midnight On Voting Day
-

 National News2 years ago
J&K: 4 Jawans Killed, 28 Injured After Bus Carrying BSF Personnel For Poll Duty Falls Into Gorge In Budgam; Terrifying Visuals Surface
-

 Crime2 years ago
Baba Siddique Murder: Mumbai Police Unable To Get Lawrence Bishnoi Custody Due To Home Ministry Order, Says Report