Business
Petrol, diesel prices unchanged for fortnight

Consumers continue to get relief from rising fuel prices as oil marketing companies (OMCs) have kept pump prices of petrol and diesel unchanged post revision of duties by the state governments on Diwali eve.
Accordingly, petrol and diesel prices remained static for the 14th consecutive day on Thursday under the daily price revision mechanism followed by oil marketing companies.
So, the pump price of petrol in Delhi, which fell to Rs 103.97 a litre at 6 a.m. on the Diwali day on November 4 from the previous days’ level of Rs 110.04 a litre, remained at the same level on Thursday. The diesel prices also remained unchanged in the capital at Rs 86.67 a litre.
In the financial capital Mumbai, petrol continued to be priced at Rs 109.98 a litre and diesel Rs 94.14 a litre.
Prices also remained static on Wednesday in Kolkata where the price of petrol reduced by Rs 5.82 to Rs 104.67 per litre and that of diesel by Rs 11.77 to Rs 89.79 per litre in the first week of November.
Petrol price in Chennai also remained at Rs 101.40 per litre and diesel Rs 91.43 per litre.
Across the country as well, the price of the fuel largely remained unchanged on Thursday but the retail rates varied depending on the level of local taxes.
The global crude prices, which has touched a three-year high level of over $85 a barrel on several occasions in the past one month, has softened now to below $ 80 barrel. Rise in the US inventory has pushed down crude prices, but OPEC+ decision on only gradual increase in production in December could raise crude prices further. This could put pressure on oil companies to revise fuel prices upwards again.
Before price cuts and pause, diesel prices have increased 30 out of the last 55 days taking up its retail price by Rs 9.90 per litre in Delhi.
Petrol prices have also risen on 28 of the previous 51 days taking up its pump price by Rs 8.85 per litre.
Since January 1, 2021, petrol and diesel prices have risen by more than Rs 26 a litre before the duty cuts.
The excise duty cut by the Centre on November 3 was the first such exercise since the onset of Covid pandemic. In fact, the government had revised excise duty on petrol and diesel sharply in March and again in May last year to mobilise additional resources for Covid relief measures.
The excise duty was raised by Rs 13 and Rs 16 per litre on petrol and diesel between March 2020 and May 2020 and was standing high at Rs 31.8 on diesel and Rs 32.9 per litre on petrol before finally the Centre decided on duty cut.


Indian equity benchmarks posted a firm recovery, sustaining gains for the second week as investors looked past early inflation worries, especially after the central bank’s special dollar window for oil marketing companies helped the rupee rebound.
Nifty added 2.78 per cent during the week and gained 0.65 per cent on the last trading day to reach 23,146.
At close, Sensex was up 413 points or 0.56 per cent at 74,729. It gained 3.11 per cent during the week.
Market sentiment was dented earlier in the week by consumer inflation hovering near the upper end of the Reserve Bank of India’s tolerance band and a hotter‑than‑expected wholesale price index print that pushed benchmark bond yields to multi‑year highs.
The central bank raised the daily cash reserve ratio maintenance requirement to absorb surplus liquidity, adding to caution. Market confidence, however, improved after the central bank’s special dollar window for oil marketing companies and tighter hedging norms drove a rupee-rebound, analysts said.
“Expectations of a review of LTCG tax and STT, softer crude prices and easing bond yields further revived risk appetite, prompting investors to tilt towards counters with strong Q2FY27 business updates, though the rally remained concentrated in large-caps, with mid-caps posting modest gains and small-caps ending marginally lower,” they added.
“Participants should remain selective, maintain disciplined position sizing and favour a hedged approach amid elevated macroeconomic and earnings-related uncertainty,” the experts said.
Information technology (IT) sector emerged as the standout performer on robust earnings and upbeat management commentary, while healthcare and pharmaceuticals lagged as investors favoured sectors with stronger near-term earnings visibility.
Meanwhile, fast‑moving consumer goods stocks came under pressure amid concerns over margin compression from elevated input costs.
Broad market indices performed largely in line with the benchmark indices as Nifty Midcap100 added 0.58 per cent and Nifty Smallcap100 dipped 0.12 per cent during the week.
In addition, foreign institutional investors (FIIs) turned net buyers of Rs 11.66 billion in Indian equities on Friday after overall selling eased sharply this week as market sentiment improved.
FIIs remained net sellers for the ninth straight week but their weekly selling moderated to Rs 89.91 billion from Rs 302.94 billion the previous week. On the other hand, domestic institutional investors (DIIs) stayed net buyers for a ninth consecutive week at Rs 78.13 billion, though they were net sellers of Rs 36.61 billion on Friday.
The sustainability of the recovery will hinge on earnings growth broadening beyond IT with revenue and margin delivery across financials, consumption and industrials under close scrutiny, analysts said.
Investors are keen on India’s October PMI that will offer insight into domestic demand momentum, while US jobless claims and Japan’s inflation print will shape global rate expectations.
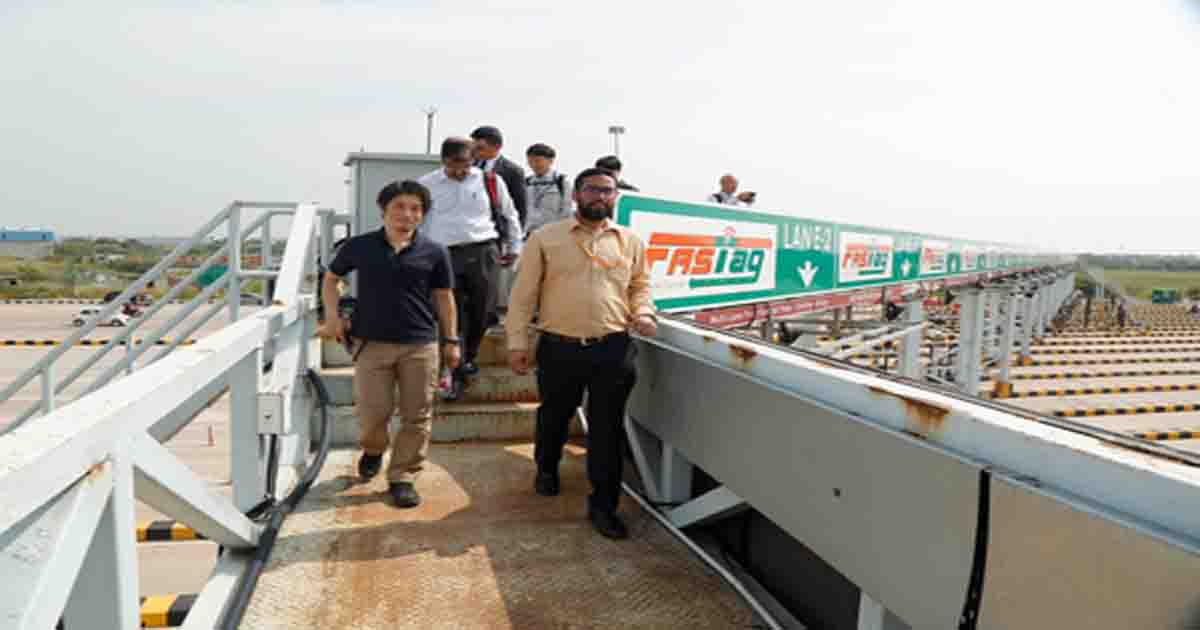
A Japanese delegation visited the Multi-Lane Free Flow (MLFF) tolling system in Mundka-Bakkarwala on Friday on the sidelines of the 12th India–Japan Joint Working Group Meeting on Roads and Road Transportation.
The MLFF system provided insights into India’s technology-driven initiatives for seamless and efficient highway travel.
At the MLFFs, the National Highways Authority of India (NHAI) uses a combination of RFID-based FASTag electronic toll collection, automatic number plate recognition (ANPR) and AI analytics to allow vehicles to pass through charging points without stopping, slowing down or remaining in a designated lane.
MLFFs have already been installed at Choryasi in Gujarat, Mundka in Delhi, Gharaunda in Haryana and Daulatpura and Manoharpura in Rajasthan.
While 12 further locations have been awarded for conversion, tenders have also been launched covering an additional 104 toll plazas around the country.
The MLFF at Choryasi on the Surat–Bharuch section of NH-48 was the first to become operational.
The one at Mundka on Delhi’s Urban Extension Road-II was the second.
The expansion plan represents a significant shift from India’s traditional barrier-based toll plazas.
Rather than moving immediately to satellite-based toll collection, the Indian government has opted to build on the country’s established FASTag system and combine it with ANPR and AI.
Expert committees had recommended further consideration of GPS-based barrier-free tolling because of security, privacy and operational control issues, the Ministry of Road Transport and Highways has indicated.
FASTag and ANPR/AI was thus selected as the technology for the current MLFF programme.
The session of the India–Japan Joint Working Group on Roads and Road Transportation Sector was successfully held at Bharat Mandapam in New Delhi.
Discussions focused on advanced construction technologies, bridge and tunnel engineering, sustainable infrastructure and digital innovations, fostering the exchange of technical expertise and best practices.
“The meeting reaffirmed both nations’ commitment to safe, sustainable and technology-driven road infrastructure, aligned with the vision of Viksit Bharat @ 2047,” the Ministry said in a statement.
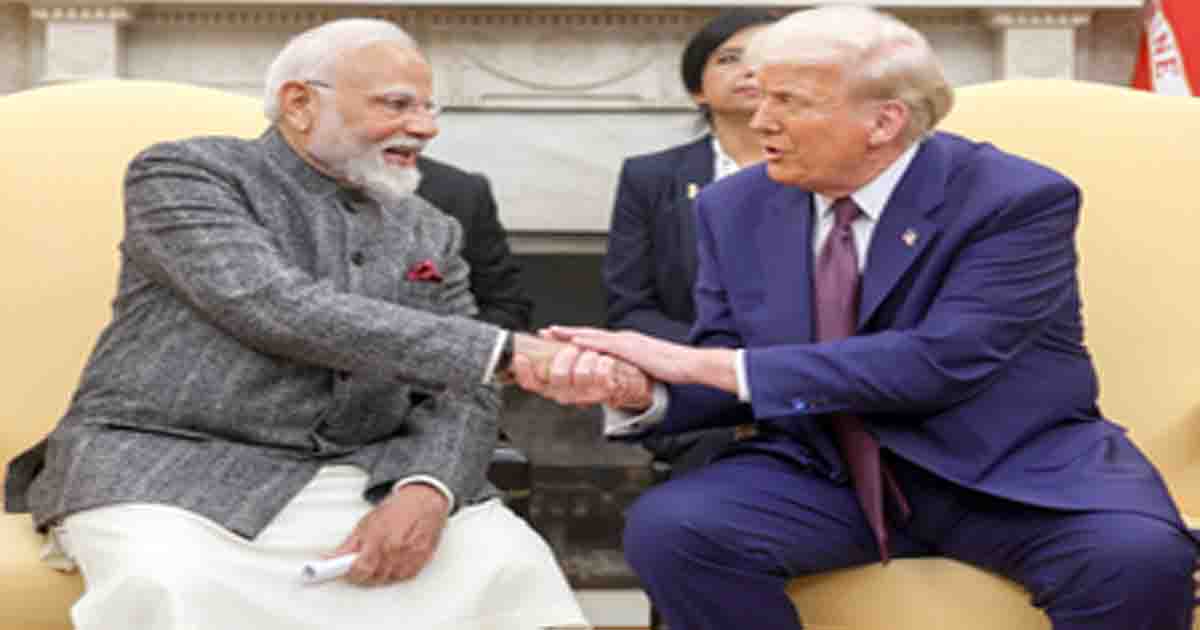
Washington, Oct 16: A long-awaited trade agreement between India and the United States is almost complete, with only one or two per cent of negotiations remaining, a senior US official said, signalling that the two countries are approaching a breakthrough after months of high-level discussions.
The official said the biggest issues had already been resolved and that negotiations were continuing at the highest political levels, including between President Donald Trump and Prime Minister Narendra Modi.
“The biggest items have been settled. I mean …., it’s pretty much done. We have that one, one or two per cent left,” the official told reporters during a State Department briefing on Friday.
The remarks came ahead of Secretary of State Marco Rubio’s scheduled visit to India, where he will hold discussions with Indian government officials and leading business executives in Mumbai and Jamnagar.
The official said the two governments remained in constant contact over the proposed agreement.
“We are actively engaged every single week,” the official said, adding that high-level discussions on the trade deal were taking place regularly.
The official cited recent diplomatic engagements involving US Trade Representative Jamieson Greer, India’s Commerce Minister Piyush Goyal and conversations between Trump and PM Modi as evidence of the momentum behind the negotiations.
However, the official also identified a significant complication that had delayed the agreement.
An earlier understanding had been linked to the International Emergency Economic Powers Act, or IEEPA, but the legal framework had to be reconsidered after the law was struck down, according to the official.
The development forced negotiators to revisit elements of the proposed agreement and contributed to several additional months of discussions.
Despite those complications, the official expressed optimism that the remaining differences could be resolved soon.
Rubio is scheduled to travel first to Uzbekistan for meetings with Central Asian leaders before proceeding to India.
In Mumbai, he will meet Indian government counterparts and senior executives from some of the country’s largest companies.
The official said the decision to visit Mumbai rather than New Delhi reflected the administration’s growing emphasis on commercial diplomacy and Indian investment in the United States.
Rubio will also travel to Jamnagar.
The official said Washington was seeking closer engagement with India across information technology, pharmaceuticals, defence cooperation and other sectors.
Further visits by senior American Cabinet officials are also anticipated next year as both governments seek to expand bilateral engagement.

Samajwadi Party, education two banks of river who can’t meet: UP CM Yogi Adityanath

Tanker attacked northeast of Saudi Arabia: UKMTO

MP: Mild earthquake tremors felt in Singrauli

Maha CM calls emerging technologies key to India’s youth

Iran IRGC says supertanker exploded after hitting mine in Hormuz Strait

Rahul, Cong ecosystem want to force regime change: BJP after Neha Bora praises B’desh Gen-Z protest

BJP pays tribute to ex-President Abdul Kalam, recalls his enduring influence on generations of India’s youth

INDIA bloc begins protest march against ECI

Maha Congress stages agitation against Gyanesh Kumar

Complaint against Netflix & Mukesh Chhabra for inappropriate language on ‘India’s Got Latent 2’
-

 Crime4 years ago
Class 10 student jumps to death in Jaipur
-

 Maharashtra2 years ago
Mumbai Local Train Update: Central Railway’s New Timetable Comes Into Effect; Check Full List Of Revised Timings & Stations
-

 Maharashtra2 years ago
Mumbai To Go Toll-Free Tonight! Maharashtra Govt Announces Complete Toll Waiver For Light Motor Vehicles At All 5 Entry Points Of City
-

 Maharashtra2 years ago
False photo of Imtiaz Jaleel’s rally, exposing the fooling conspiracy
-

 National News2 years ago
Ministry of Railways rolls out Special Drive 4.0 with focus on digitisation, cleanliness, inclusiveness and grievance redressal
-

 Maharashtra2 years ago
Maharashtra Elections 2024: Mumbai Metro & BEST Services Extended Till Midnight On Voting Day
-

 National News2 years ago
J&K: 4 Jawans Killed, 28 Injured After Bus Carrying BSF Personnel For Poll Duty Falls Into Gorge In Budgam; Terrifying Visuals Surface
-

 Crime2 years ago
Baba Siddique Murder: Mumbai Police Unable To Get Lawrence Bishnoi Custody Due To Home Ministry Order, Says Report