Business
Fresh customs, banking reforms on cards towards ‘Viksit Bharat’: FM Sitharaman
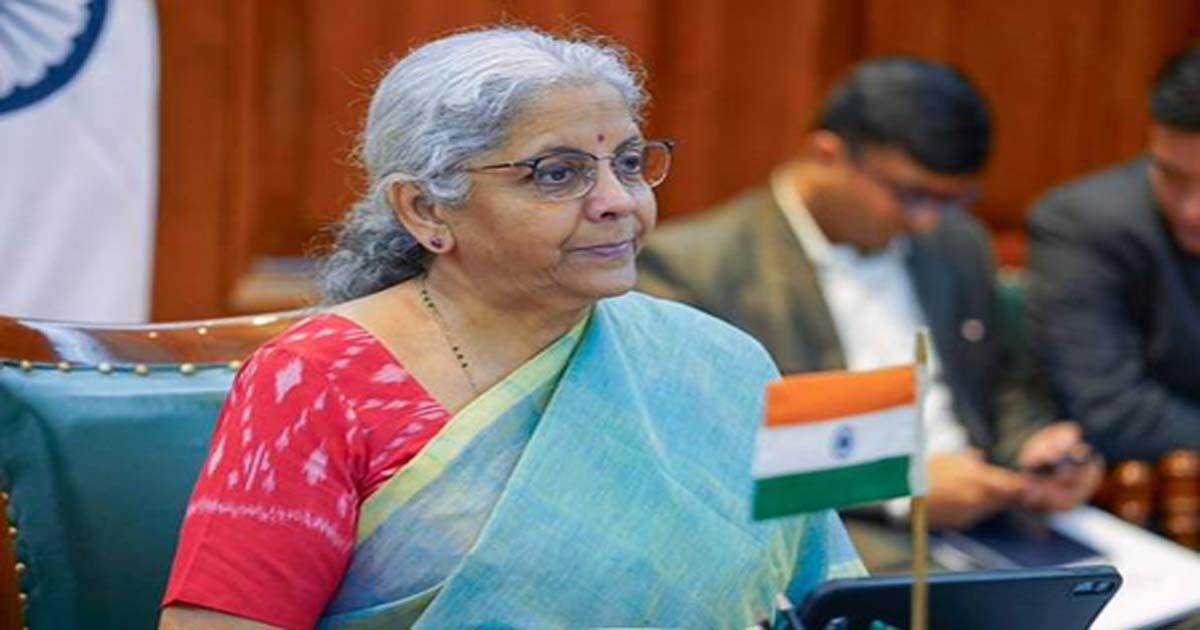
Asheville, Sep 1: India is preparing further customs and banking reforms, including risk-based import screening and a high-level review of the banking sector’s role towards building a developed India, Union Minister for Finance & Corporate Affairs Nirmala Sitharaman said.
In an exclusive interview with media on the sidelines of the G20 Finance Ministers’ meeting here, FM Sitharaman said the next phase would build on changes already made in direct and indirect taxation.
“We’ve done quite a few things about the direct and indirect taxes. Customs, we’ve done some, we’ll have to do more. We’ll be taking those up,” she said.
The government is working to make the movement of imported goods through Indian ports more seamless, the Finance Minister said.
A key proposal involves deploying scanners and concentrating checks on high-risk importers. Other consignments could then be cleared automatically, reducing delays for businesses and easing congestion at ports.
“We are trying to bring in scanners and have high-risk importers alone go through them, and the rest of them can be cleared automatically,” FM Sitharaman said.
“A lot of reforms in the customs area,” she added.
The approach would allow customs authorities to focus their scrutiny on higher-risk imports while facilitating faster clearances in other cases.
However, FM Sitharaman did not provide a timetable for introducing the scanners or implementing the proposed automatic clearance system.
The government has also appointed a high-level committee to examine the banking sector and its future role in achieving India’s development goals.
“The banks, of course, we’ve appointed a high-level committee to look into banking for Viksit Bharat,” she told media.
“That committee will also give its report,” she added, without indicating when its recommendations would be submitted.
Asked about the next stage of the government’s wider reform programme, FM Sitharaman said changes would be taken up as requirements emerged.
“Well, we take it as we go along,” according to her.
The Finance Minister said the Centre had worked with state governments to improve the business environment and reduce the compliance burden on citizens and companies.
“I think together with the states, I will also credit the states, many of them who have come forward to make doing business a bit easier,” she said.
“We, as you know, have reduced a lot of compliance burden on the citizens, whether it is by reforming the Acts, by simplifying the regulations, and also by removing archaic laws,” she added.
More than 1,000 laws had been removed and about 40,000 regulations simplified, according to the Finance Minister.
The government was also maintaining regular consultations with industry, businesses and trade while pursuing bilateral trade and investor protection agreements.
“Constantly, we are engaging with the industry, with businesses, with trade,” FM Sitharaman said.
“Also, the way in which bilateral trade agreements are being signed, we are now pushing ahead with investor protection agreements as well,” she added.
FM Sitharaman said confidence in the Indian banking system was reflected in foreign deposits and investments made by Indians living overseas. The indicators showed a positive story about trust in Indian banks and the country’s macroeconomic position, she said.
The proposed reforms come as India reported 7.8 per cent growth in the first quarter of the 2026-27 financial year. Manufacturing grew by 9.2 per cent, while the financial and professional services sector expanded by 12.1 per cent.
FM Sitharaman also cited the expansion of UPI, NPCI systems and QR-code payments as factors helping small and medium-sized businesses gain access to global markets. She said reforms across government departments and the financial sector had brought out the robustness of the Indian economy.


Kathmandu, Oct 15: Nepal and the International Bank for Reconstruction and Development (IBRD), part of the World Bank Group, have signed a mandate agreement to explore the development of a catastrophe bond that could help the Himalayan nation secure rapid access to funds in the event of a major natural disaster.
The agreement marks the beginning of a collaboration to assess the feasibility and potential structure of a catastrophe bond, under which Nepal could transfer part of its disaster risk to international capital markets and strengthen its financial preparedness for natural disasters, the World Bank said in a statement.
Under the agreement, the World Bank Group Treasury will work with the Nepal government and market participants to evaluate the proposed transaction.
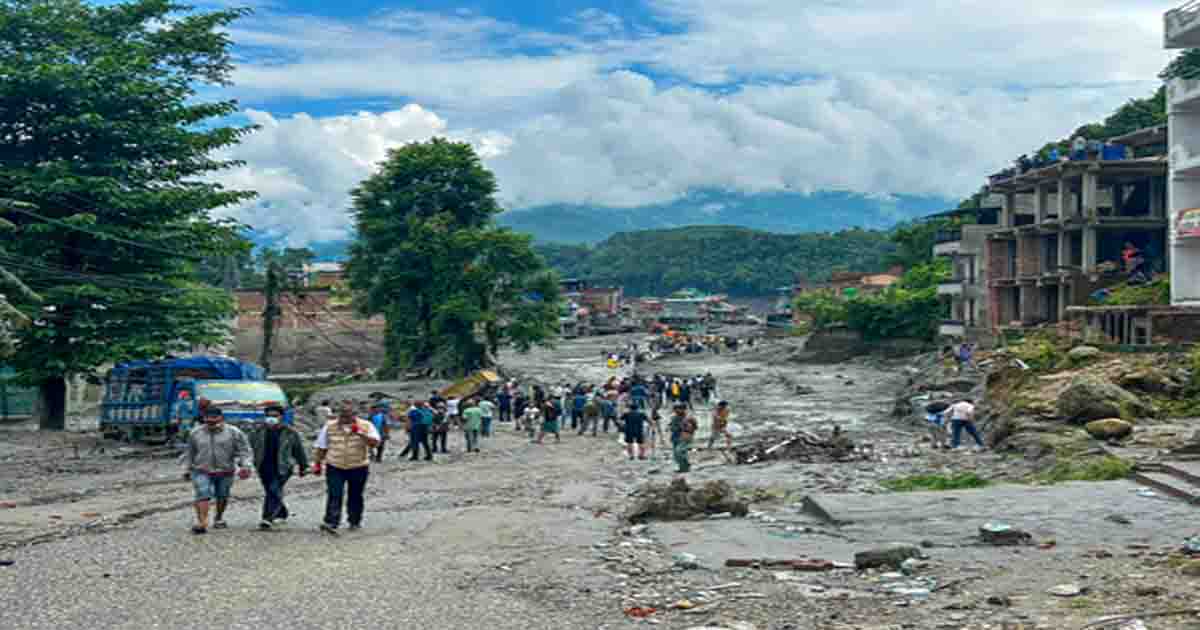
The initiative comes as Nepal seeks to strengthen its capacity to prepare for, withstand and recover from natural disasters in the wake of devastating floods in the Bhotekoshi and downstream Trishuli river basins on August 26. The floods have killed nearly 1,500 people, while more than 5,000 remain unaccounted for, according to the National Disaster Risk Reduction and Management Authority.
Triggered by an avalanche near the Nepal-China border that blocked the river’s flow, the floods swept away several human settlements, a dozen hydropower projects, a solar plant, and several roads and bridges. Physical damage is estimated at 1.66 billion US dollars, according to the World Bank’s Global Rapid Post-Disaster Damage Estimation report.
According to the World Bank, Nepal is highly vulnerable to earthquakes, floods, landslides and other climate-related hazards, which can cause extensive damage to infrastructure, disrupt economic activities and place considerable pressure on public finances.
A catastrophe bond is a financial instrument that allows governments or other entities to transfer specific disaster risks to investors. Depending on the terms of the bond, investors may lose some or all of their principal if a specified disaster occurs, allowing the funds to be used to support the affected entity.
“Such instruments can provide an alternative source of disaster financing, potentially enabling governments to access funds more quickly than relying solely on budget reallocations or post-disaster assistance,” the World Bank said.
The initiative is part of the World Bank Group’s established catastrophe bond programme, which has helped countries access international capital markets to transfer disaster risks and secure financial protection against natural hazards.
The World Bank helps countries increase their financial resilience to disasters by supporting disaster risk financing programmes and offering contingent financing and insurance solutions.
It also assists countries in designing, developing and implementing comprehensive disaster risk financing strategies.
“A risk financing strategy helps clients determine a balance between retaining risk, for example, through a contingent financing product, and transferring risk, for example, through an insurance product,” the World Bank said.
A range of financial products can be used to address the financial risks of disasters, and the optimal mix of approaches depends on the types of risks faced by a country and the frequency and severity of disaster events, it said.
Developing countries are particularly vulnerable to the economic and fiscal consequences of disasters because of factors such as gaps in insurance coverage, inadequate infrastructure resilience, and the concentration of populations and economic activities in exposed areas.
“Following a major disaster, governments often have to redirect budgetary resources towards emergency response, relief and reconstruction, potentially affecting other development priorities,” the World Bank said.
New Delhi, Oct 15: The Indian rupee is likely to remain in an appreciating territory even as global markets remain engulfed in turbulence, while the government and the Reserve Bank of India (RBI) may need to consider further policy steps to shore up resilience, a report said on Thursday.
The report from SBI Research forecasted inflation to peak at around 6.8 per cent in November 2026. It predicted that India’s 10-year yield will likely touch 7.6 per cent which will aid in price discovery in the future as well.
“The USD/INR forward implied yield opened at 4.60 per cent, around 42 bps higher than yesterday’s close,” the report noted.
Higher hedging costs make dollar funding more expensive and could encourage corporates to shift towards INR-denominated borrowing, supporting demand for the rupee, it added.
“The RBI has done a stupendous job and now the government must step up in reducing structural frictions on the taxation front, European Central Bank policy, ODI and AI policy,” the report noted.
The RBI could adopt a calibrated tightening approach through an asymmetric corridor adjustment, raising the MSF rate by 50 bps from 5.75 per cent to 6.25 per cent in the interim.
This could be followed by a 25 bps repo rate hike in December, taking the repo rate to 5.75 per cent and the MSF rate to 6.50 per cent, it forecasted.
Global financial markets are likely to remain volatile amid persistent geopolitical uncertainties, elevated US yields and evolving inflation dynamics.
The RBI has taken salutary steps to stabilise market conditions and can act up to a point, but further measures by the government on the taxation front, particularly concerning G-secs and ECBs clarity on AI policy, could help deepen domestic borrowing avenues and support capital flows.
Business
Govt signs Rs 4,106 crore contracts for communication satellite for IAF, heavyweight torpedoes for Navy

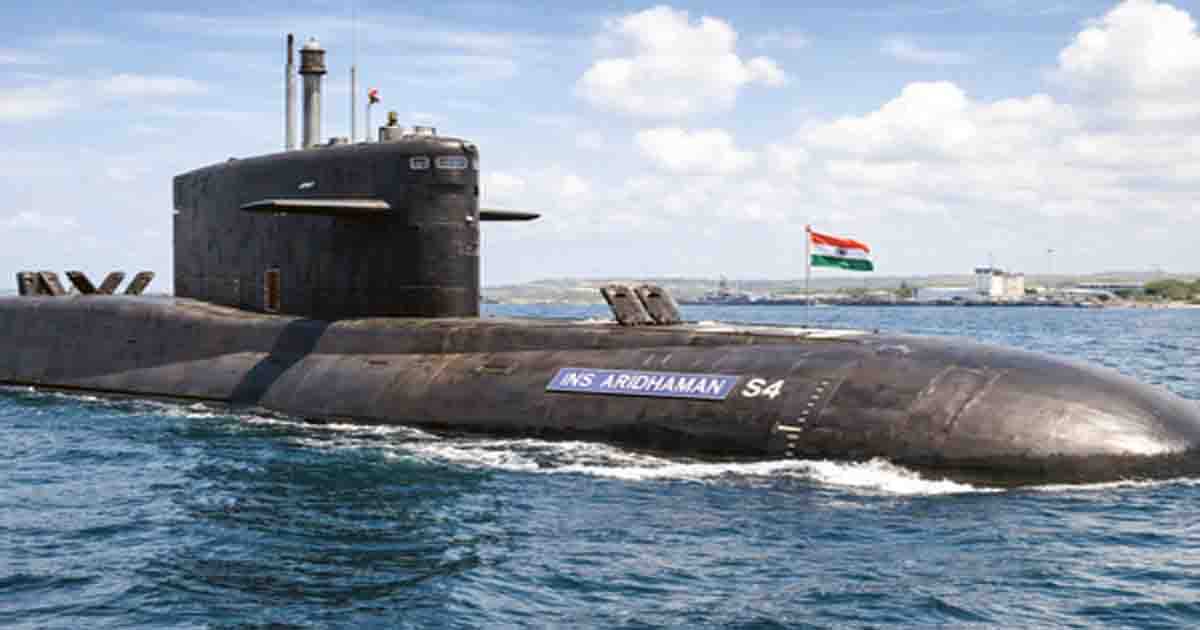
New Delhi, Oct 15: The Ministry of Defence on Thursday said it has signed contracts worth Rs 4,106 crore for the acquisition of a dedicated communication satellite capability for the Indian Air Force, and Varunastra heavy-weight torpedoes for the Indian Navy.
Both contracts mark a significant step towards advancing the development of domestic defence manufacturing capabilities while promoting self-reliance in critical technologies in line with the government’s ‘Aatmanirbhar Bharat’ and ‘Make-in-India’ vision.
The contract for the GSAT-7C satellite, valued at Rs 2,563 crore, was signed with New Space India Limited, Bengaluru.
According to an official statement, this indigenously designed, developed and manufactured satellite will enhance the secure, resilient and seamless communication capabilities for the assets of the Indian Air Force, thereby strengthening operational effectiveness.
Meanwhile, the contract for Varunastra, worth Rs 1,543 crore, was signed with Bharat Dynamics Limited, Hyderabad.
Varunastra is an indigenous ship-launched anti-submarine torpedo developed by the Naval Science and Technological Laboratory.
“Equipped with advanced manoeuvring capabilities, it is capable of engaging enemy submarines at long ranges, thereby enhancing the anti-submarine warfare capability of the Indian Navy,” said the statement.
Earlier this month, the Ministry of Defence signed a Rs 661.50 crore deal with BrahMos Aerospace Private Limited for the procurement of BrahMos fire control system and launchers for Indian Navy ships under the Buy (Indian-IDDM) category.
With a minimum of 68 per cent indigenous content, the project encourages active participation of various Indian industries, including MSMEs (micro, small and medium enterprises) in the supply chain. The project will generate employment over a period of three years.
It also bolsters India’s maritime security architecture and defence capabilities and marks a critical milestone in the ongoing efforts to indigenise advanced military technology, according to the Defence Ministry statement.
The BrahMos System fitted on board various frontline warships is the Indian Navy’s primary Surface-to-Surface Missile (SSM) system for maritime strike operations. The weapon system is capable of targeting land and sea targets from extended ranges with pinpoint accuracy at supersonic speed.

Building collapses in Varanasi due to firecracker explosion, two rescued

Take child sexual abuse material circulation on social media seriously, SC tells Centre

Kerala: 5,991 road accident deaths occurred on national highways in three years

SC refers Rajpal Yadav cheque bounce cases to mediation for amicable settlement

NEET-PG 2026: SC issues notice on plea seeking candidate-wise disclosure of questions, options, and answers

Mumbai Cyber Cell arrests 6 members of organized gang in major operation; Beware of cyber fraudsters; Digital arrest has no legal status; DCP Bajrang Bansode

INDIA bloc begins protest march against ECI

Maha Congress stages agitation against Gyanesh Kumar

Rahul, Cong ecosystem want to force regime change: BJP after Neha Bora praises B’desh Gen-Z protest

Complaint against Netflix & Mukesh Chhabra for inappropriate language on ‘India’s Got Latent 2’
-

 Crime4 years ago
Class 10 student jumps to death in Jaipur
-

 Maharashtra2 years ago
Mumbai Local Train Update: Central Railway’s New Timetable Comes Into Effect; Check Full List Of Revised Timings & Stations
-

 Maharashtra2 years ago
Mumbai To Go Toll-Free Tonight! Maharashtra Govt Announces Complete Toll Waiver For Light Motor Vehicles At All 5 Entry Points Of City
-

 Maharashtra2 years ago
False photo of Imtiaz Jaleel’s rally, exposing the fooling conspiracy
-

 National News2 years ago
Ministry of Railways rolls out Special Drive 4.0 with focus on digitisation, cleanliness, inclusiveness and grievance redressal
-

 Maharashtra2 years ago
Maharashtra Elections 2024: Mumbai Metro & BEST Services Extended Till Midnight On Voting Day
-

 National News2 years ago
J&K: 4 Jawans Killed, 28 Injured After Bus Carrying BSF Personnel For Poll Duty Falls Into Gorge In Budgam; Terrifying Visuals Surface
-

 Crime2 years ago
Baba Siddique Murder: Mumbai Police Unable To Get Lawrence Bishnoi Custody Due To Home Ministry Order, Says Report