Business
Economic slowdown: Sitharaman calls for ‘proactive collective efforts’ by G-20

Finance Minister Nirmala Sitharaman has called for “proactive collective efforts” by the G-20 group of the world’s top economies to deal with the current slowdown in the growth momentum of the global economy.
Addressing fellow ministers and central bank heads of the G-20 member countries, the minister attributed the slowdown to “prolonged inflation, supply chain disruption, volatility in energy markets and investor uncertainty”, according to a series of Twitter posts by the Ministry of Finance.
Sitharaman, who is in Washington DC for the Spring Meetings of the World Bank Group (which includes the International Monetary Fund), said G-20 “is well placed to catalyse international policy coordination to deal with macroeconomic consequences and called for proactive collective efforts towards protecting economies”, according to the Finance Ministry.
The 2022 April Spring Meetings are taking place amidst a significant slowdown in the global economy, whose recovery from the adverse effects of the Covid-19 pandemic was rudely halted by the Russian invasion of Ukraine and the economic upheaval it has caused.
The IMF estimates that the “global growth will slow down from an estimated 6.1 per cent in 2021 to 3.6 per cent in 2022 and 2023. These are 0.8 and 0.2 percentage points lower for 2022 and 2023 projections in the January World Economic Outlook Update. Beyond 2023, global growth is forecast to decline to about 3.3 per cent over the medium term. This projection is based on the assumption that the conflict will remain confined to Ukraine further sanctions on Russia exempt the energy sector (although the impact of European countries’ decisions to wean themselves off Russian energy and embargoes announced through March 31, 2022, are factored into the baseline), and the pandemic’s health and economic impacts abate over the course of 2022”.
India’s growth projections have also been cut by both the fund and the World Bank. The fund said India will grow by 8.2 per cent in 2022, down 0.8 percentage points from 9 per cent as projected in January, which in itself was down 0.5 percentage points form its previous projection. The World Bank has projected 8 per cent growth for the Indian economy in 2022 in a report released last week.
The Finance Minister is holding meetings on the sidelines of the World Bank Group events, with counterparts from around the world and corporate leaders.
Sitharaman and US commerce secretary Gina Raimondo discussed “ways to strengthen economic cooperation in the bilateral and global contexts”, the ministry said in a tweet. She also met counterparts from the Netherlands and Suriname.
The Finance Minister pitched India to the US semiconductor industry in a meeting with John Neuffer, president and CEO of the Semiconductor Industry Association. She informed Neuffer of the “initiatives & policies rolled out by the Government of India (GoI) to attract & support foreign investment in semiconductor industry, including development of sustainable semiconductor and display ecosystem with an outlay of $10 billion, in India”, the ministry said.
Neuffer was described as being “upbeat” about the initiatives taken by GoI to promote investment in Semiconductor ecosystem and appreciated India’s commitment to become a reliable player in the global supply chain.


Mumbai, Sep 18: Domestic equity markets opened higher on Friday tracking positive global cues and amid buying in metal, real estate and cement sectors stocks.
Sensex opened at 74,575.24, up 260 points or 0.35 per cent, while Nifty rose 64 points or 0.28 per cent to 23,334.70.
Among sectoral indices, Nifty Metal gained the most and rose 0.76 per cent in early trade, followed by Nifty Realty which gained 0.74 per cent. Nifty Cement was up 0.55 per cent and Media trading 0.47 per cent higher.
Meanwhile, healthcare, auto, banking, pharma, energy and FMCG indices were also trading higher.
On the other hand, Nifty IT declined more than 1 per cent, while Nifty MidSmall IT & Telecom fell 0.40 per cent.
From the Nifty index, Tata Motors Passenger Vehicles, TCS, Infosys, Tech Mahindra and HCL Technologies were top losers and declined up to declined up to 3 per cent in morning trade.
Analysts said resilience in the US market despite elevated bond yields and expectations of strong corporate earnings have supported global equities.
“The underlying strength of the economy is supporting the market which continues to be buoyant, and this strength of the mother market is supporting markets elsewhere,” they said.
On the domestic front, experts said the ongoing boom in the primary market has shifted investor attention towards IPOs and listing gains, leaving some large-cap stocks in the secondary market depressed.
“For long-term investors, this is an opportunity. Leading banks, capital goods majors, select automobiles and pharmaceutical stocks provide buying opportunities,” according to them.
Technically, the broader market structure remains weak, while the RSI at 29.95 indicates oversold momentum.
“Immediate support for the Nifty is placed at 23,000-23,150, while resistance is seen at 23,350-23,450. A decisive move beyond the resistance zone could signal a stronger recovery, while a break below support may keep the corrective trend intact,” the analysts said.
In addition, foreign institutional investors (FIIs) remained net sellers on Thursday, offloading equities worth Rs 3,208 crore, according to provisional exchange data. While domestic institutional investors (DIIs) continued to provide support and bought equities worth Rs 3,617 crore.
Additionally, global cues remained positive.
Overnight on Thursday US markets ended higher as the S&P 500 closed 1.14 per cent higher and the tech-heavy Nasdaq rose 1.69 per cent.
In Asian markets, Japan’s Nikkei was up nearly 2 per cent, while Hong Kong’s Hang Seng gained almost 1 per cent. South Korea’s KOSPI surged more than 2 per cent.
On the commodities front, international benchmark Brent crude declined 1 per cent to $103.61 per barrel, while US West Texas Intermediate (WTI) was around $101 a barrel, down 0.77 per cent.
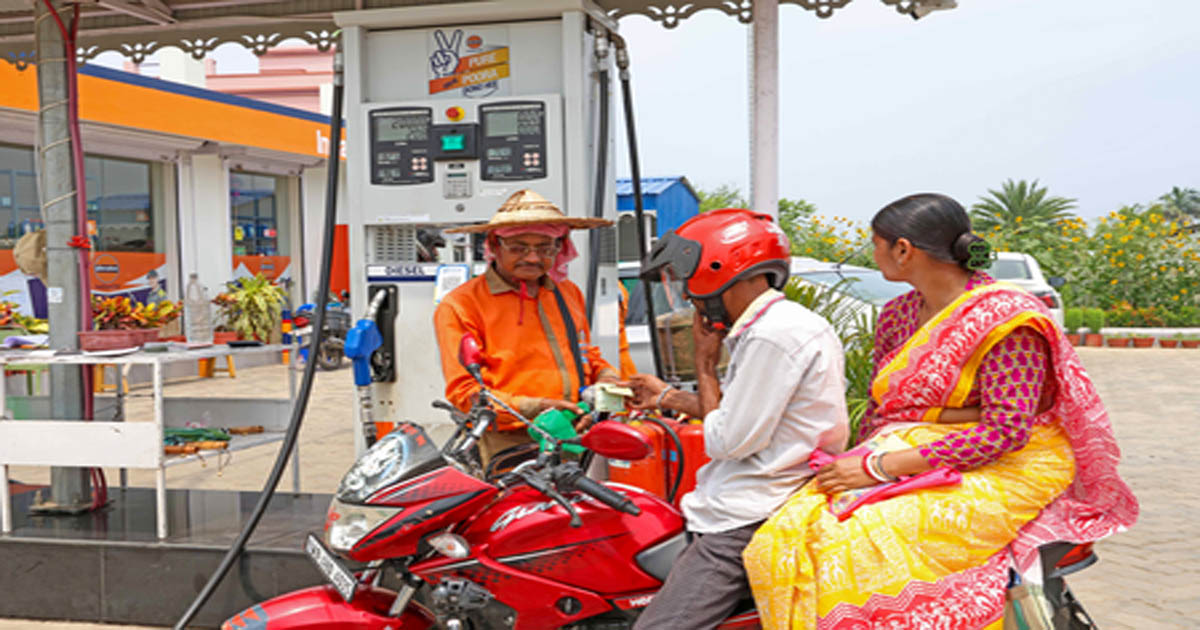
New Delhi, Sep 17: Representatives of the All India Petroleum Dealers Association (AIPDA) met senior officials of the Ministry of Petroleum and Natural Gas on Thursday to discuss their demand for exemption from the merchant discount rate (MDR) on UPI transactions on fuel sales at petrol pumps.
The dealers’ body said in a statement that the issue was discussed with senior officials of the Petroleum Ministry as the additional MDR cost could put pressure on dealer margins, as retail fuel sales are made on prescribed commissions.
The new UPI framework levies an MDR of Rs 5 per transaction on petrol and diesel purchases above Rs 2,000. Such transactions account for around 30-40 per cent of total purchases across retail outlets in the country, according to dealers.
Petroleum Ministry officials sought to explain the rationale behind introducing MDR, which was required to support the development of the next layer of India’s UPI digital infrastructure.
“Petroleum dealers have been at the forefront of adopting digital payments and have worked closely with the government to promote their use across the country,” the AIPDA said.
The association said it expects to continue the dialogue with the government.
“We look forward to continuing the dialogue towards a mutually beneficial solution for consumers, petroleum dealers, and all stakeholders in India’s UPI ecosystem,” the statement said.
Dealers have raised concerns as digital payments have become an important mode of payment at petrol pumps, particularly for higher-value purchases.
Petroleum dealers have sought a complete exemption for fuel retail transactions, citing the nature of their business and the impact of MDR-related costs on their margins.
The Finance Ministry clarified that MDR is neither a tax nor a charge collected by the government or NPCI. It is distributed among payment ecosystem participants, including banks and payment application providers, to support the operation and continued expansion of the UPI ecosystem.
Transactions above Rs 2,000 in essential and thin-margin sectors, including railways, telecommunications, insurance, fuel and agricultural inputs, will attract a flat MDR of Rs 5 per transaction. The flat charge will provide cost certainty for critical public services and businesses operating on narrow margins.
Mumbai, Sep 17: In a major push to reinforce Maharashtra’s fiscal health and support its long-term growth roadmap, Maharashtra Chief Minister Devendra Fadnavis announced the constitution of the Maharashtra Sustainable Public Finance Committee.
Headed by renowned economist and former Union Finance Secretary Dr Vijay Kelkar, the high-level panel, which was announced late Wednesday evening, is tasked with recommending measures to ensure sustainable growth in tax and non-tax revenues.
The decision forms an integral part of the state’s ‘Viksit Maharashtra @ 2047’ vision document, which outlines a strategic roadmap to scale the state’s economy to $1 trillion by 2030 and $5 trillion by 2047—coinciding with the centenary of India’s Independence.
The panel has been tasked with making recommendations to modernise the tax system, plug revenue leakages, and rationalise tax rates, fees, and exemptions; identify untapped revenue streams and maximise returns from public assets and state enterprises; streamline public spending while balancing expanding committed expenditures such as salaries, pensions, interest payments, and welfare schemes; and devise a fiscally responsible roadmap to reduce reliance on borrowings for infrastructure projects and budget deficits.
The Kelkar Committee comprises Prof Karthik Muralidharan (founder-director, CEGIS), Dr Nitin Kareer (former Chief Secretary, Maharashtra), T Rabi Sankar (former Deputy Governor, Reserve Bank of India) and Dr Ashima Goyal (President, The Indian Econometric Society).
The formation of the panel comes at a critical juncture for Maharashtra. While the state actively pursues an investment-led growth strategy across core sectors—including infrastructure, human resource development, water security, urban management, and energy transition—it faces growing fiscal constraints.
Maharashtra government’s Vision document has suggested restructuring the government expenditure policy to align with long-term capital formation, identifying alternative financing models and private capital inflows.
Fiscal deficit targets are capped within standard Fiscal Responsibility and Budget Management (FRBM) boundaries, targeting 2.8 per cent to 3.0 per cent of Gross State Domestic Product (GSDP) while keeping the revenue deficit under 0.7 per cent of GSDP, and implementation is tracked quarterly via a dedicated Vision Management Unit chaired by the chief minister.
Adhering to the targets set under the FRBM Act has proved challenging due to rising welfare commitments and debt servicing costs. Consequently, the government has frequently resorted to market borrowings to fund capital projects and offset short-term liquidity shortfalls.
The newly appointed Kelkar Committee is expected to deliver structural fiscal remedies to reverse this trend and secure long-term financial sustainability for the state.

16-year-old girl gang-raped and killed in Delhi, body found in field

Indian markets open higher tracking positive global cues; metal, realty stocks lead

Mumbai Cyber Cell arrests 6 members of organized gang in major operation; Beware of cyber fraudsters; Digital arrest has no legal status; DCP Bajrang Bansode

Bengaluru: Family dispute suspected behind deadly attack on Bengal nurse by estranged husband from TN (Ld)

Municipal Commissioner Ashwini Bhide visits Mumbai’s Veermata Jijabai Bhosale Botanical Garden and Zoo to inspect various ongoing projects and initiatives.

Four more Indian nationals rescued in Nepal, 120 cross safely from China: MEA

Gift to President Putin part of PM Modi bid to globally display India’s heritage

Nepal floods: First batch of 106 stranded Maharashtra tourists reaches India; 84 more expected today (Ld)

India, Brazil sign ICT MoU to deepen digital, telecom cooperation

Maharashtra: 17-year-old boy dies by suicide on Raksha Bandhan after emotional social media posts
-

 Crime4 years ago
Class 10 student jumps to death in Jaipur
-

 Maharashtra2 years ago
Mumbai Local Train Update: Central Railway’s New Timetable Comes Into Effect; Check Full List Of Revised Timings & Stations
-

 Maharashtra2 years ago
Mumbai To Go Toll-Free Tonight! Maharashtra Govt Announces Complete Toll Waiver For Light Motor Vehicles At All 5 Entry Points Of City
-

 Maharashtra2 years ago
False photo of Imtiaz Jaleel’s rally, exposing the fooling conspiracy
-

 National News2 years ago
Ministry of Railways rolls out Special Drive 4.0 with focus on digitisation, cleanliness, inclusiveness and grievance redressal
-

 Maharashtra2 years ago
Maharashtra Elections 2024: Mumbai Metro & BEST Services Extended Till Midnight On Voting Day
-

 National News2 years ago
J&K: 4 Jawans Killed, 28 Injured After Bus Carrying BSF Personnel For Poll Duty Falls Into Gorge In Budgam; Terrifying Visuals Surface
-

 Crime2 years ago
Baba Siddique Murder: Mumbai Police Unable To Get Lawrence Bishnoi Custody Due To Home Ministry Order, Says Report