Business
India Set To Lead The World In 6G, Says Telecom Minister Jyotiraditya Scindia

In a bold declaration at the inaugural address of the Indian Mobile Congress 2024 (IMC) on Tuesday, Union Telecom Minister Jyotiraditya M. Scindia has said that India will lead the world in the adoption of 6G.
In his address at the event, Scindia emphasized that India is now prepared to lead the world in the development of 6G technology.
India’s Technological Rise: From Following to Leading
“It is our belief and commitment that India, which followed the world in 4G and marched with it in 5G, will lead the world in 6G,” Scindia stated.
The minister highlighted India’s remarkable achievements in the telecommunications sector over the last ten years, the country has become a global leader in innovation and technology.
“It’s a fundamental change in approach towards technology development,” he said, attributing this transformation to Prime Minister Narendra Modi’s leadership.
Telecom Sector Growth Under PM Modi’s Leadership
“Prime Minister who has always put people at the heart of progress Sabka Sath, Sabka Vikas Sabka Vishvas aur Sabka Prayas combined with his second motto, One Earth, One Family and One Future. It is combination of these two mottos that leads India under PM Narendra Modi leadership one of the leading sectors in the committee of Nations,” Scindia said.
Scindia underscored government’s initiatives to bridge the digital divide, particularly through the BharatNet program, the world’s largest rural broadband connectivity initiative to connect every panchayat of the nation. Over the past three years, the government has invested more than USD 10 billion and laid 7 lakh kilometres of fiber across rural India.
Digital Payments and UPI: Pillars of India’s Digital Economy
He cited staggering growth in mobile and broadband connectivity, with mobile connections rising from 94 million to 1.16 billion, and broadband users growing from 60 million to 924 million in just a decade. India’s optical fibre cable (OFC) networks has expanded from 11 million kilometers to 41 million kilometres over the last ten years, he added.
The minister further said that this growth is accompanied by the success of India’s digital payment systems, the 4G stack, and the Unified Payments Interface (UPI), which serve as pillars of India’s digital economy are expected to contribute significantly to the global digital infrastructure.
Scindia further noted that the government’s efforts to ensure that policy frameworks keep pace with the rapidly evolving digital landscape. “The recent changes to the Telecommunications act 2023 is a case in point. It has been drawing light upon hither to undressed areas such as a high potential sector of satellite communications, addressing the challenges of the digital leader. The most important being cyber security. The telecom sector much like other growth critical sectors in India is aggressive, is ambitioushe said.
“The telecom sector much like other growth critical sectors in India is aggressive, is ambitious and its outlook in our Journey from Amritkal to Shatabdikal is to lead the world,” Scindia said. By mid-next year, India will have achieved 100 per cent saturation of 4G across the entire country, covering even the most remote villages, the minister said.
He emphasised PM Modi’s vision of India as a first mover in 6G technology, underscoring the nation’s resolve to lead the world in future telecom innovations.
“The attitude put forward by the prime minister of not just embracing, but raising ourselves to becoming the first mover in the 6G technology,” he added.


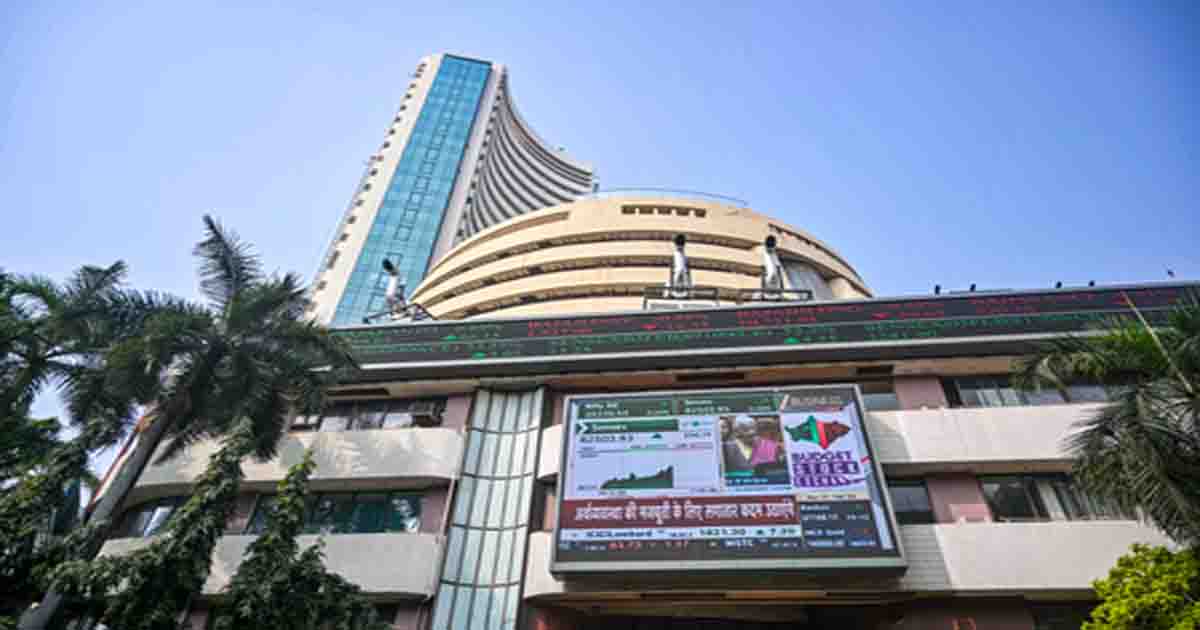
Mumbai, Sep 30: Domestic equity benchmarks opened flat on Wednesday tracking mixed global cues as investors remained cautious after foreign investors extended their selling streak to a fourth straight session.
Nifty opened at 22,665, down about 50 points or 0.23 per cent. Sensex began trading at 72,441.15, lower by 87.92 points or 0.12 per cent.
In early trade, the Nifty MidSmall IT & Telecom index was top sectoral gainer which rose more than 1 per cent.
Meanwhile, Nifty PSU Bank, Nifty Chemicals, Nifty Oil & Gas, Nifty Cement and Nifty Media also jumped up to 1 per cent.
In contrast, metal stocks were among the laggards with Nifty Metal falling 0.42 per cent. Healthcare and pharmaceutical indices were also marginally lower.
Market experts said elevated US bond yields were contributing to foreign investor selling, while the recent correction had created attractive valuations in parts of the Indian market.
“From the Indian investors’ perspective, this sharp correction in the market presents an opportunity. Largecaps with good growth prospects have reached attractive valuations,” they said.
Experts also noted that a correction in crude oil prices could trigger a market rally with largecap market leaders potentially leading such a move.
Technical analysts said the market could attempt to stabilise after its recent decline, with buying emerging around key technical levels.
Nifty had formed a hammer candle in the previous session, indicating buying interest at lower levels, while strength in select heavyweight stocks helped limit the decline.
The near-term structure has improved towards sideways to mildly bullish following the reversal from 22,600.
Immediate support is seen at 22,650-22,700, while resistance is placed at 22,950-23,000, according to the experts.
On Tuesday, foreign institutional investors (FIIs) extended their selling streak to a fourth consecutive session, offloading equities worth nearly Rs 10,000 crore, according to provisional data.
Domestic institutional investors (DIIs) provided support, buying equities worth nearly Rs 7,000 crore.
In addition, Asian markets were broadly positive in early hours despite a mildly weaker Wall Street session, while investors remained focused on upcoming US economic data and global market trends for further direction.
Mumbai, Sep 29: Gold and silver prices traded lower on Tuesday with precious metals declining up to 1 per cent amid elevated US yields and uncertainty over the US-Iran standoff which weighed on bullion sentiment.
On the Multi Commodity Exchange (MCX), gold futures (December) were trading at Rs 1,48,410 per 10 grams, down Rs 487 or 0.33 per cent.
The yellow metal declined as much as 0.50 per cent or Rs 747 to hit an intraday low of Rs 1,48,150 by 10:34 am. It touched an intraday high of Rs 1,49,034, up 0.09 per cent or Rs 137.
On the other hand, silver futures (December) fell as much as 1.29 per cent or Rs 2,942 to hit an intraday low of Rs 2,24,500 per kg.
At the last count, the white metal was trading at Rs 2,25,338, down Rs 2,104 or 0.93 per cent. It touched an intraday high of Rs 2,26,359, down 0.47 per cent or Rs 1,083.
The selling pressure in precious metals came amid elevated tensions between the US and Iran over the Strait of Hormuz which kept energy prices higher.
Spot gold was also trading lower after falling 4 per cent in the previous session to a seven-week low.
Iranian officials reportedly have privately expressed pessimism about reaching an agreement with Washington to end hostilities before the US midterm elections in November.
The developments came after US President Donald Trump rejected Iran’s latest proposal to reopen the critical waterway within seven days.
The uncertainty has kept energy prices elevated while higher US yields have added pressure on non-yielding assets such as gold and silver.
According to commodity experts, immediate resistance for gold is placed at Rs 1,50,000-1,50,700, followed by Rs 1,52,000-1,52,600, while support is seen at Rs 1,48,000-1,47,300, followed by Rs 1,46,000-1,45,300.
However, the near-term bias remained cautious, with a sustained move above Rs 1,50,000 needed to confirm a recovery. A decisive break below Rs 1,48,000 could trigger another decline.
For silver, the experts said the metal opened with a gap-down near Rs 2,26,000 and remained below the Rs 2,27,000-2,28,000 zone, which has turned into resistance following Monday’s steep decline.
Immediate resistance for silver is seen at Rs 2,27,000-2,28,000, followed by Rs 2,32,000-2,33,000. Support is placed at Rs 2,24,000-2,23,000, followed by Rs 2,20,000-2,19,000.
The bias for silver remained cautious to negative, with a sustained move above Rs 2,28,000 needed to stabilise the setup. A decisive break below Rs 2,24,000 could expose the metal to the Rs 2,20,000 region.
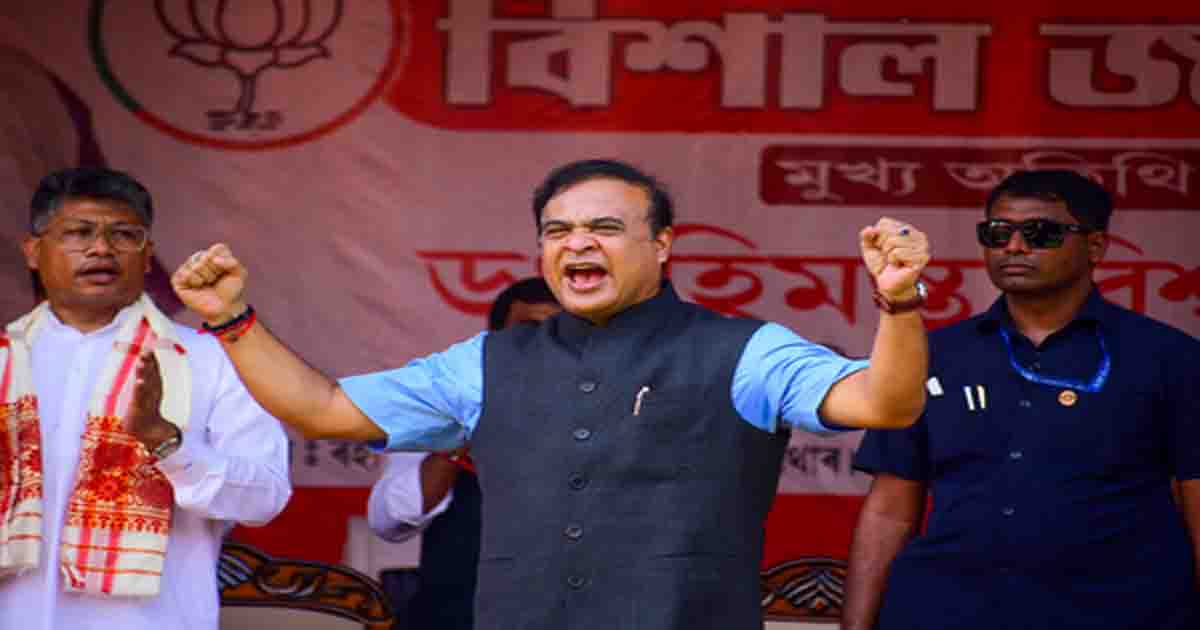
Guwahati, Sep 29: Assam Chief Minister Himanta Biswa Sarma on Tuesday highlighted the growing investment and employment opportunities in the state, citing a Rs 778 crore investment and the expansion of local value chains from agricultural produce to consumer products.
Taking to social media platform X, CM Sarma said the growth of investment in Assam was creating more opportunities for local employment and enabling products originating in the state to reach markets beyond its borders.
“It grows with opportunity ₹778 Cr investment, more local employment opportunities,” CM Sarma said in his post. Highlighting the connection between agriculture and industry, the Chief Minister said the journey of a potato grown in Assam’s fields to a packet of Lay’s available on consumers’ shelves represented the kind of economic opportunity the state was seeking to create.
“From a potato growing in our fields to a packet of Lay’s on your shelf. That’s what opportunity looks like – Made in Assam, reaching beyond Assam,” he said.
The post underlined the state government’s emphasis on strengthening local production and creating an ecosystem in which agricultural output can feed into large-scale processing and manufacturing.
The Rs 778 crore investment highlighted by CM Sarma is also significant in the context of Assam’s efforts to attract private investment and expand employment opportunities outside traditional sectors.
The government has been promoting the state as an emerging investment destination, with a focus on manufacturing, food processing, infrastructure and other industries.
The Chief Minister’s remarks also pointed to the potential of linking Assam’s farmers with organised food-processing and consumer-product supply chains. Such linkages can create additional avenues for value addition within the state while enabling locally produced agricultural commodities to access wider markets.
The reference to Lay’s reflects the broader idea of converting locally grown agricultural produce into branded consumer products, thereby creating economic activity at multiple stages, from farming and procurement to processing, packaging, logistics and retail.
CM Sarma’s post comes amid the state government’s continued efforts to project Assam as a destination for investment and industrial development. The government has repeatedly stressed the need to generate more local employment while ensuring that the benefits of industrial growth reach communities and producers within the state.
The Chief Minister said the larger objective was to ensure that opportunities created in Assam were not confined to the state but enabled locally produced goods to reach consumers across the country and beyond.

Bihar Mahagathbandhan echo in Oppn’s UP seat-sharing debates?

Israel probes Flydubai cockpit incident after hijack alert (Ld)

Youth-led research to transform Maharashtra into a global innovation hub: CM Fadnavis

US-led coalition concludes anti-IS operation in Iraq: Pentagon

Three men arrested in Madhya Pradesh for circulating video of tourist in Ajmer

Gift to President Putin part of PM Modi bid to globally display India’s heritage

PM Modi’s warm camaraderie with Putin, Xi on full display at BRICS Summit

7.8 pc GDP growth reflects country’s progress: Maha CM Fadnavis, Dy CM Shinde

BMC takes action against Mumbai Central Orchid City Mall; mall shut down.

Nepal PM calls for global response to rising Himalayan climate risks
-

 Crime4 years ago
Class 10 student jumps to death in Jaipur
-

 Maharashtra2 years ago
Mumbai Local Train Update: Central Railway’s New Timetable Comes Into Effect; Check Full List Of Revised Timings & Stations
-

 Maharashtra2 years ago
Mumbai To Go Toll-Free Tonight! Maharashtra Govt Announces Complete Toll Waiver For Light Motor Vehicles At All 5 Entry Points Of City
-

 Maharashtra2 years ago
False photo of Imtiaz Jaleel’s rally, exposing the fooling conspiracy
-

 National News2 years ago
Ministry of Railways rolls out Special Drive 4.0 with focus on digitisation, cleanliness, inclusiveness and grievance redressal
-

 Maharashtra2 years ago
Maharashtra Elections 2024: Mumbai Metro & BEST Services Extended Till Midnight On Voting Day
-

 National News2 years ago
J&K: 4 Jawans Killed, 28 Injured After Bus Carrying BSF Personnel For Poll Duty Falls Into Gorge In Budgam; Terrifying Visuals Surface
-

 Crime2 years ago
Baba Siddique Murder: Mumbai Police Unable To Get Lawrence Bishnoi Custody Due To Home Ministry Order, Says Report