Business
India-Indonesia Economic and Financial Dialogue launched at G20 Finance Ministers’ meet
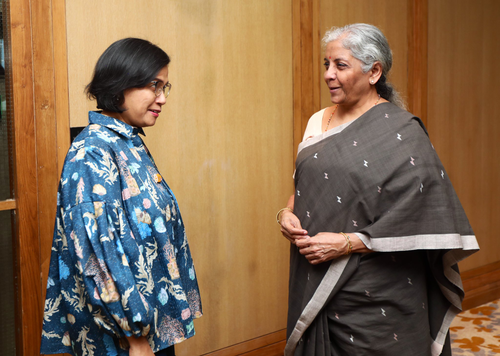
Finance Minister Nirmala Sitharaman and her Indonesian counterpart Mulyani Indrawati on Sunday announced the launch of the “India–Indonesia Economic and Financial Dialogue” (EFD Dialogue).
The platform, unveiled during the G20 Finance Ministers and Central Bank Governors (FMCBG) meeting at Gandhinagar, seeks to strengthen cooperation between the two nations and foster a shared understanding on global issues.
“The evolution of India’s ‘Look East Policy’ in 1991, followed by the ‘Act East Policy’, has facilitated a rapid development in our bilateral relations, particularly in the commercial and cultural fields,” Sitharaman said.
“Indonesia has emerged as India’s largest trading partner in the ASEAN region, with our trade seeing an eightfold increase since 2005, reaching an impressive $38 billion in 2022-23,” she added.
The EFD Dialogue is poised to enhance collaboration on bilateral and international economic and financial matters by bringing together economic policymakers and financial regulators from both countries.
Areas of cooperation inter-alia, include macroeconomic challenges and global economic prospects, bilateral investment relations, and cooperation in G20 and ASEAN matters.
Recognising the potential of the digital economy, the two Finance Ministers also noted the potential of collaboration in the field of fintech for financial inclusion. Both concluded with a shared optimism that the EFD Dialogue will not only deepen the bilateral relationship between India and Indonesia, but also contribute to the broader economic and financial stability of Southeast Asia and the world.


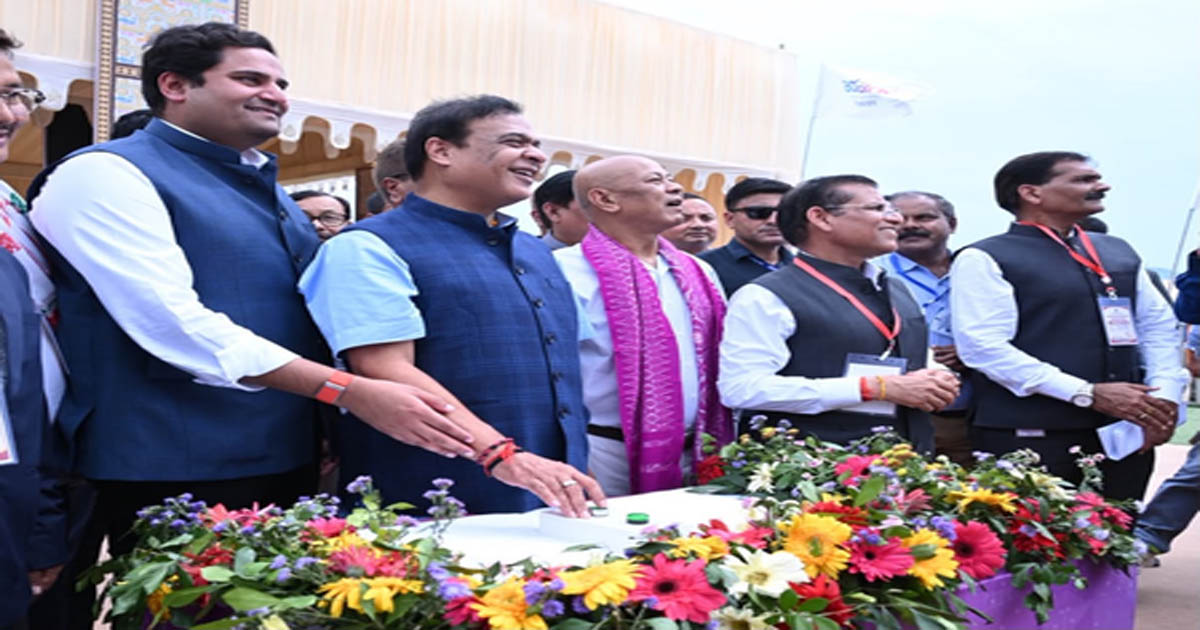
Guwahati, Sep 20: Assam Chief Minister Himanta Biswa Sarma on Sunday laid the foundation stone for Adani Power Limited’s 3,200 MW ultra-supercritical thermal power plant at Chapar in Dhubri district, marking one of the largest private investments in the state’s history.
The project, which entails an investment of around Rs 48,000 crore, is expected to significantly boost Assam’s power generation capacity while creating large-scale employment opportunities.
According to the company, the plant is likely to generate up to 20,000 jobs during the construction phase and around 5,000 permanent and indirect jobs once it becomes operational.
The foundation stone ceremony was attended by senior state government officials, industry representatives, community leaders and Adani Group Director Jeet Adani.
The Chapar thermal power project forms a major component of the Adani Group’s broader Rs 63,000-crore investment plan in Assam’s power sector.
The plant is scheduled to be commissioned in phases beginning in December 2030 and will comprise four units of 800 MW each. It will use ultra-supercritical technology designed to improve efficiency while incorporating modern environmental safeguards.
In his address at the event, Chief Minister Sarma said Assam is rapidly emerging as an energy hub for the Northeast and that several large energy projects are currently under development in the state. He described the Chapar project as a major outcome of the investment commitments made during the Advantage Assam Investor Summit 2.0.
“With an investment of nearly Rs 48,000 crore, this project will constitute one of the largest single investments ever made in Assam,” he stated.
Jeet Adani said the thermal power project marks the beginning of a new chapter in Assam’s development journey. “The project will also create jobs and open up opportunities for local contractors, suppliers and businesses. We are proud to invest in Assam and be part of the state’s economic growth,” he noted.
Highlighting the Group’s wider plans in the state, Jeet Adani said investments exceeding Rs 80,000 crore across power, aviation and cement sectors are already translating into projects on the ground.
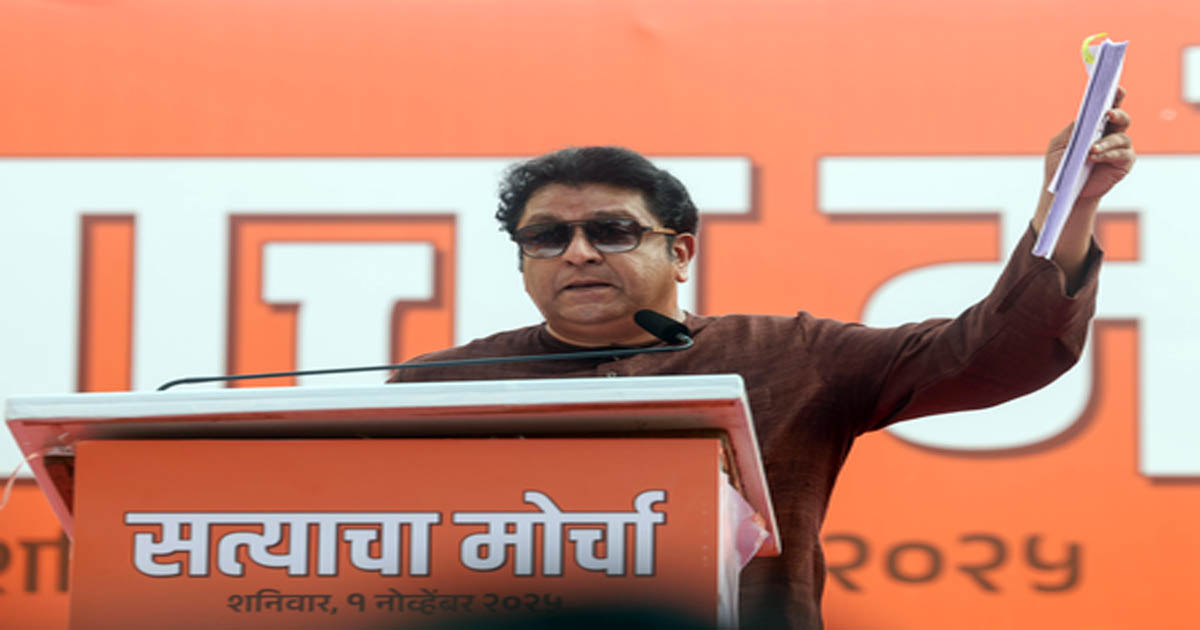
Mumbai, Sep 19: In a sharp political offensive against the Central government’s decision to introduce a 0.4 per cent Merchant Discount Rate (MDR) on select Unified Payments Interface (UPI) transactions above Rs 2,000, Maharashtra Navnirman Sena (MNS) Chief Raj Thackeray on Saturday alleged that the administration has ensnared the nation in a carefully laid “digital trap”.
In a detailed statement on social media platform X, the MNS Chief accused the ruling MahaYuti coalition-led Maharashtra government of lulling Indian citizens into a false sense of security with free digital transactions, only to quietly impose transaction fees and taxes once people became dependent on the platform.
Tracing the trajectory of digital payments from the 2016 Demonetisation move to the nationwide push for UPI adoption, Raj Thackeray said that the trajectory was planned to make citizens reliant on digital architecture before levying charges.
“First came Demonetisation; then the UPI system was introduced with great fanfare to showcase the push for digital transactions. They trumpeted its success, basked in self-praise, got people habituated to it, and then suddenly announced that fees would apply. In short, they lulled citizens into a false sense of security and quietly ensnared them in a digital trap,” he remarked.
He said that he had consistently warned the public against assuming that zero-fee digital services would remain permanent, saying that the government’s process of “coming knocking at your door” to collect revenues has now officially begun.
He questioned why permanent budgetary provisions for long-term maintenance and cybersecurity were not established during the initial investment phase if the intent was genuinely to simplify transactions rather than monetise them later.
Rejecting the Union government’s claim that the 0.4 per cent MDR burden falls solely on merchants, Raj Thackeray asserted that the Union government possesses zero monitoring mechanisms to prevent small and large businesses from passing the extra operational cost onto consumers.
He sharply criticised the levy of 18 per cent Goods and Services Tax (GST) on top of the MDR, accusing the Finance Ministry of attempting to “dip into citizens’ pockets wherever possible”.
Raising questions around international policy influences, Raj Thackeray cited Opposition’s allegations regarding US pressure and asked whether foreign card corporations and global payment networks influenced the policy decision.
Releasing a official government tweet screenshot from August 21, 2022 — which explicitly promised that UPI services would remain completely free — the MNS Chief called the recent policy shift evidence of “unclear and non-transparent intentions”.
He formally registered his party’s protest against the implementation of the Merchant Discount Rate.
Calling upon the trading community, small business owners, and retail associations to take a unified stand, Raj Thackeray urged merchants across Maharashtra and the nation to vehemently oppose paying the new transaction levies.
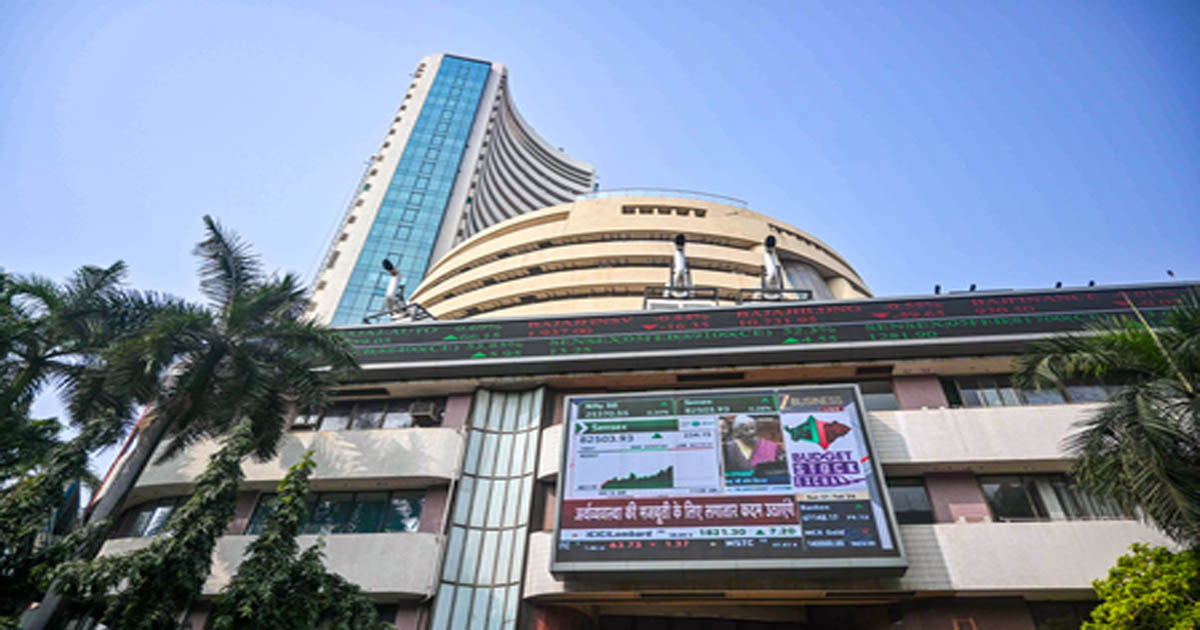
Mumbai, Sep 19: The Indian equity benchmarks posted notable losses for the sixth consecutive week as foreign institutional investor (FII) selling continued and concerns about a prolonged high‑rate environment kept investors cautious.
Nifty declined 0.22 per cent during the week and added 0.33 per cent on the last trading day to reach 23,346. At close, Sensex was down 19 points, or 0.03 per cent, at 74,294. It lost 0.65 per cent during the week.
After a weak start, Indian equities staged a partial recovery later, supported by a retreat in crude oil prices from recent highs.
“With the US and Japanese policy decisions broadly in line with expectations, easing energy inflation concerns helped temper the inflation premium embedded in sovereign yields, leading to a moderation in yields in the latter part of the week and some relief for equity valuations,” an analyst said.
However, the accompanying policy guidance continued to signal a broader tightening bias across major economies, making a prolonged high-rate environment likely.
Against this backdrop, persistent FII selling sustained pressure on the rupee and capped the market rebound, leaving domestic equities lower for the week, he added.
Mid and small-cap stocks outperformed large caps as investors rotated toward domestically oriented businesses with stronger earnings visibility, healthier order books and sound balance sheets.
Sectorally, healthcare and FMCG attracted buying on their defensive earnings profiles and domestic demand linkage.
Realty and metals remained among the stronger sectors on Friday, while IT continued to face pressure, with the Nifty IT index declining around 1 per cent.
Mid and small-cap IT stocks and consumer durables declined this week on concerns over global technology spending and discretionary demand in a higher-for-longer interest rate environment and persistent pricing pressure, respectively.
Meanwhile, the 23,000–23,100 zone remains the immediate support area for Nifty, while 23,400–23,600 region remains the immediate resistance zone.
Market participants forecast that domestic credit growth and PMI readings will provide a gauge of underlying activity in the week ahead.
US initial jobless claims and commentary from Federal Reserve officials will shape expectations on the rate trajectory and global liquidity conditions.

Fake social media account, Chat GPT used in Ketan Agarwal murder

Kriti Sanon crosses pottery art off her bucket list: Make today your ‘Day One’

47.3 kg heroin seized in Punjab, four held

‘Should become stand-up comedian’, BJP’s swipe at Rahul Gandhi over mimicry of Prime Minister

Delhi Police trace minor girl after 8 years, recover her from Bihar

Four more Indian nationals rescued in Nepal, 120 cross safely from China: MEA

Gift to President Putin part of PM Modi bid to globally display India’s heritage

Nepal floods: First batch of 106 stranded Maharashtra tourists reaches India; 84 more expected today (Ld)

Maharashtra: 17-year-old boy dies by suicide on Raksha Bandhan after emotional social media posts

PM Modi’s warm camaraderie with Putin, Xi on full display at BRICS Summit
-

 Crime4 years ago
Class 10 student jumps to death in Jaipur
-

 Maharashtra2 years ago
Mumbai Local Train Update: Central Railway’s New Timetable Comes Into Effect; Check Full List Of Revised Timings & Stations
-

 Maharashtra2 years ago
Mumbai To Go Toll-Free Tonight! Maharashtra Govt Announces Complete Toll Waiver For Light Motor Vehicles At All 5 Entry Points Of City
-

 Maharashtra2 years ago
False photo of Imtiaz Jaleel’s rally, exposing the fooling conspiracy
-

 National News2 years ago
Ministry of Railways rolls out Special Drive 4.0 with focus on digitisation, cleanliness, inclusiveness and grievance redressal
-

 Maharashtra2 years ago
Maharashtra Elections 2024: Mumbai Metro & BEST Services Extended Till Midnight On Voting Day
-

 National News2 years ago
J&K: 4 Jawans Killed, 28 Injured After Bus Carrying BSF Personnel For Poll Duty Falls Into Gorge In Budgam; Terrifying Visuals Surface
-

 Crime2 years ago
Baba Siddique Murder: Mumbai Police Unable To Get Lawrence Bishnoi Custody Due To Home Ministry Order, Says Report