Business
Goa’s economy can’t revive with mining ban in force
With an alarming decline in Goas economic growth, the state government can no longer afford to sit on the issue of mining ban, a survey revealed.
According to the Economic Survey released by the Directorate of Planning, Statistics and Evaluation, Goa’s economy grew by a mere 1.6 per cent in 2020-21.
The coastal state’s economy is heavily dependent on manufacturing, agriculture, tourism, and mining. While the first two sectors showed a clear decline during the assessment period, the inflow of both national and foreign tourists was curtailed due to the Covid-19 pandemic.
The survey observes that during the pandemic period, the tourism-related businesses came down to almost zero. On the other hand, mining operations have stayed suspended in Goa for more than four years.
“The major chunk of mining related businesses has not been able to switch over or diversify their line in view of bleak changes of buyers for their assets riddled with debts. Alternate business for existing mining assets in other states is not easy to get as there are a lot of challenges posed from local people of respective states,” said Ralph De Sousa, President, Goa Chamber of Commerce & Industry (GCCI).
“And for assets like river barges it is more challenging as operations are typical to Goa Logistic system. Also, overall, there is no alternative to the mining business to replace the employment that is lost due to abrupt stoppage of mining operation 4 years ago. There is a hope given that mining is going to start soon so disposing the debt ridden asset gets tricky.
“The financial situation worsens with every passing day with the Goa mining ban continuing with no firm solution but hope of a major decision by the Government to restart mining. The state’s businesspersons are witnessing worsening CIBIL rating and at the same time financial institutions are facing rising NPAs.
“The immediate resumption of Goa mining industry can provide relief to the stressed situation in the state,” he added.
Goa’s consistently rising debt is an alarming concern over the last 10 years. Depending solely on loans and advances would over a period come to haunt the borrower as interest element too augments.
Goa’s main economic pillar, mining, continues to lie in suspension for several years which causes not just economic concerns but also causes hardships to those dependent on it. Ease of doing business has been affected and further casts apathy on the industrial sector on how operations, infrastructure, markets, foreign exchange, value addition built up from scratch, entirely by the industry be allowed to deteriorate with time.
The local industry as well as other Apex chambers have repeatedly raised concerns and the desired solutions expected to be taken from the Government.
“Keeping in mind sustainability, mining needs to resume earliest,” said Glenn Kalavampara, Secretary, Goa Mineral Ore Exporters Association (GMOEA).
According to the Economic Survey, Goa’s primary sector accounted for 5.24 per cent of the gross state domestic product GSDP in 2020-21.
Even the secondary sector, which contributed 55 per cent to the state economy, saw a decline, and only the tertiary or services sector was seen bucking the trend with 39.72 per cent contribution.
The state’s economic activity at constant prices for 2020-21 is estimated at Rs 53,959.86 crore, as against Rs 53,099.57 crore in 2019-20.


The ED attached immovable and movable properties worth Rs 53.95 crore in a bank fraud by a private company that resulted in a loss of over Rs 2,200 crore to a consortium of banks led by Indian Overseas Bank and 16 other banks, an official said on Monday.
The Directorate of Enforcement (ED), Mumbai Zone-I, provisionally attached the assets of Parekh Aluminex Limited (PAL) under the provisions of the Prevention of Money Laundering Act. (MLA), 2002.
Till date, the ED has attached total assets of Rs 546 crore in this case, the statement said.
The ED investigation was initiated on the basis of an FIR registered by CBI, EOW Mumbai and EOB Mumbai against Parekh Aluminex Limited, and others for offences under Sections 420 and 120-BIPC, 1860 and Sections 13(1)d) and 13(2) of the Prevention of Corruption Act, 1988.
Investigation has revealed that PAL fraudulently obtained loan from a consortium of banks by submitting inflated stock and debtor statements and later loan accounts of PAL were declared NPA for an amount of Rs 2,296 crore, the ED said.
The ED’s Investigation revealed that JK Shah Group assisted in the diversion of the Proceeds of Crime amounting to Rs 110.54 crore through various entities and persons.
One of the beneficiaries of the Proceeds of Crime received and enjoyed Rs 70.25 crore, forming part of the total Proceeds of Crime of Rs 2,296.58 crore, the ED said.
The ED had already attached assets worth Rs 493 crore in this case. A prosecution complaint (charge sheet) has also been filed before the Special Court (PMLA), Mumbai, which has taken cognisance of the offence, said the statement.
The conspirators inflicted a wrongful loss on a consortium of banks led by Indian Overseas Bank and 16 other banks, and the ED is examining the incriminating documents recovered during search operations to identify other players in the bank fraud, said the statement.
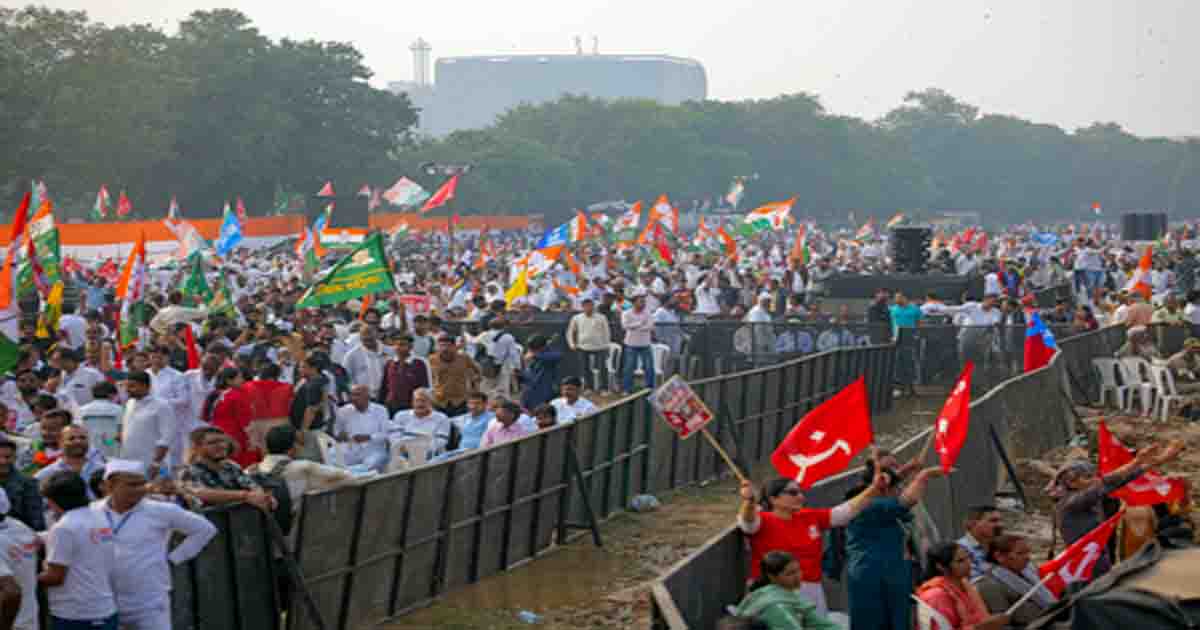
The Delhi Vyapar Mahasangh has expressed concern over the impact of the INDIA Bloc’s rally held at Ramlila Maidan on November 1, saying the political event affected business activities, customers’ movement and the livelihoods of traders and workers in the national Capital, particularly ahead of the festive season.
In a statement titled, ‘What Did We Lose, What Did We Gain?’, the traders’ body said that while the rally may have provided political parties with an opportunity to express their views and demonstrate their strength, it left Delhi’s business community with several economic questions and concerns.
“November 1 may have been an opportunity for political parties to put forward their views and demonstrate their strength, but for Delhi’s business community, the day left behind several economic questions and concerns,” the Mahasangh said.
It pointed out that Delhi’s wholesale markets are not merely centres of local trade but also serve as an important foundation for the purchases, supply chains and livelihoods of millions of small traders across the country.
The organisation said that disruption to market activities, customer movement and the supply of goods just ahead of a major festive occasion like Diwali was a matter of concern.
Listing the losses suffered by the trading community, it said business activities and customer footfall were affected on Sunday.
Small traders arriving from other states also lost valuable time and purchasing opportunities.
It added that the daily earnings of shopkeepers, employees, labourers, transporters and families dependent on them were adversely affected.
The traders’ body further claimed that the normal commercial activities and business image of Delhi’s major markets had suffered a setback, while concerns had increased over the possibility of customers shifting towards online shopping and other commercial centres.
However, the Mahasangh also acknowledged certain positive aspects of the rally, saying it brought the problems and concerns of Delhi’s trading community onto a wider public platform.
It said the event once again highlighted the important role played by Delhi’s wholesale markets in the country’s economy and supply chain. It also underlined the need for better coordination between business interests, public convenience and traffic management while planning major events in the future.
“Delhi Vyapar Mahasangh (Regd.) respects democratic rights and peaceful protests. Every political party has the right to express its views, but equal responsibility towards trade, employment, ordinary citizens and the country’s economic activities is equally necessary,” the statement said.
“Political events last for a limited period, but the economic losses suffered by businesses and the impact on customers’ trust can be felt for a long time,” it added.
The organisation urged authorities and political parties to give priority to Delhi’s business calendar, festive season, market accessibility, supply of goods and public convenience while deciding the dates and venues of large-scale events.
“Politics has its place, and trade and employment have theirs. A balance between the two is the hallmark of a strong, responsible and healthy democratic system,” it said.
Indian equity benchmarks opened strong on Monday, surging about 1 per cent each despite mixed global cues amid buying in energy, auto and information technology (IT) sector stocks.
At open, Sensex was up 718.71 points or 0.97 per cent at 75,178.24, while Nifty was up 169.20 points or 0.73 per cent at 23,222.30.
Sectorally, energy sector shares led gain as Nifty Oil & Gas surged more than 2 per cent.
Meanwhile, Nifty Auto rose 0.77 per cent and Nifty IT gained 0.51 per cent.
On the losing side, Nifty Realty declined 0.74 per cent and Nifty Media was down 0.06 per cent.
There are clear indications of a turnaround in the Indian market assisted by positive external and domestic cues, market experts said.
“Externally, the slight cooling of Brent crude prices from last week’s high of $118 to $110 now is a relief. Equally important is the decline in the US 10-year bond yield to 4.93 per cent,” they said.
“Perhaps more important than these external tailwinds is the sharp weakening of the AI trade, which pulled down the Nasdaq by 2.8 per cent last Friday. The weakening trend in AI trade is beneficial for India which is widely regarded as a counter-AI play,” the experts added.
Fundamental domestic cues are also supportive, according to them. The 17.94 per cent credit growth and robust GST collections in October reflect a resilient economy gathering momentum.
“Another strong positive which can drive the market up is the rising expectations surrounding a thorough rejig of the LTCG tax in the coming Budget, most likely its abolition. The market, it appears, has started discounting this. In brief, for now, it is an advantage for bulls,” according to analysts.
For Nifty, RSI improved to 53.50, above its average of 45.97, while PCR at 1.24 indicated a positive derivatives setup. Immediate support is placed at 22,900-23,000, while resistance is seen at 23,200-23,250. A sustained move above the 50-day EMA would further strengthen the recovery.
Asian shares traded lower while crude oil witnessed weakness. International benchmark Brent crude declined 3 per cent to $109.97 per barrel, while US West Texas Intermediate (WTI) slipped about 3 per cent to $100.81.
In the US, Wall Street ended in negative territory on Friday, with Nasdaq posting its steepest one-day fall since June 5 as disappointing Intel and Amazon results intensified concerns over heavy AI spending.

DHFL loan fraud: ED attaches properties worth Rs 40 crore in Delhi, Maharashtra

Licensed gun used in cheetah killing recovered; two brothers arrested: MP govt

Delhi-NCR pollution: GRAP stage II restrictions enforced as AQI crosses 300 ahead of Diwali

Mumbai: 70 to 80 guests of the wedding feast in Nahor fell ill with food poisoning, police continue investigation, FDA collects samples

Congress trying to protect 3 crore Bangladeshi infiltrators in voter list: HM Shah

Rahul, Cong ecosystem want to force regime change: BJP after Neha Bora praises B’desh Gen-Z protest

Attack on democratic rights: INDIA Bloc leaders on detentions of anti-ECI protestors

BJP pays tribute to ex-President Abdul Kalam, recalls his enduring influence on generations of India’s youth

INDIA bloc begins protest march against ECI

Online betting: ED conducts searches at 20 premises in Mumbai, Pune, Hyderabad
-

 Crime4 years ago
Class 10 student jumps to death in Jaipur
-

 Maharashtra2 years ago
Mumbai Local Train Update: Central Railway’s New Timetable Comes Into Effect; Check Full List Of Revised Timings & Stations
-

 Maharashtra2 years ago
Mumbai To Go Toll-Free Tonight! Maharashtra Govt Announces Complete Toll Waiver For Light Motor Vehicles At All 5 Entry Points Of City
-

 Maharashtra2 years ago
False photo of Imtiaz Jaleel’s rally, exposing the fooling conspiracy
-

 National News2 years ago
Ministry of Railways rolls out Special Drive 4.0 with focus on digitisation, cleanliness, inclusiveness and grievance redressal
-

 Maharashtra2 years ago
Maharashtra Elections 2024: Mumbai Metro & BEST Services Extended Till Midnight On Voting Day
-

 National News2 years ago
J&K: 4 Jawans Killed, 28 Injured After Bus Carrying BSF Personnel For Poll Duty Falls Into Gorge In Budgam; Terrifying Visuals Surface
-

 Crime2 years ago
Baba Siddique Murder: Mumbai Police Unable To Get Lawrence Bishnoi Custody Due To Home Ministry Order, Says Report