Business
Apple to invest Rs 100 crore in India’s renewable energy infrastructure
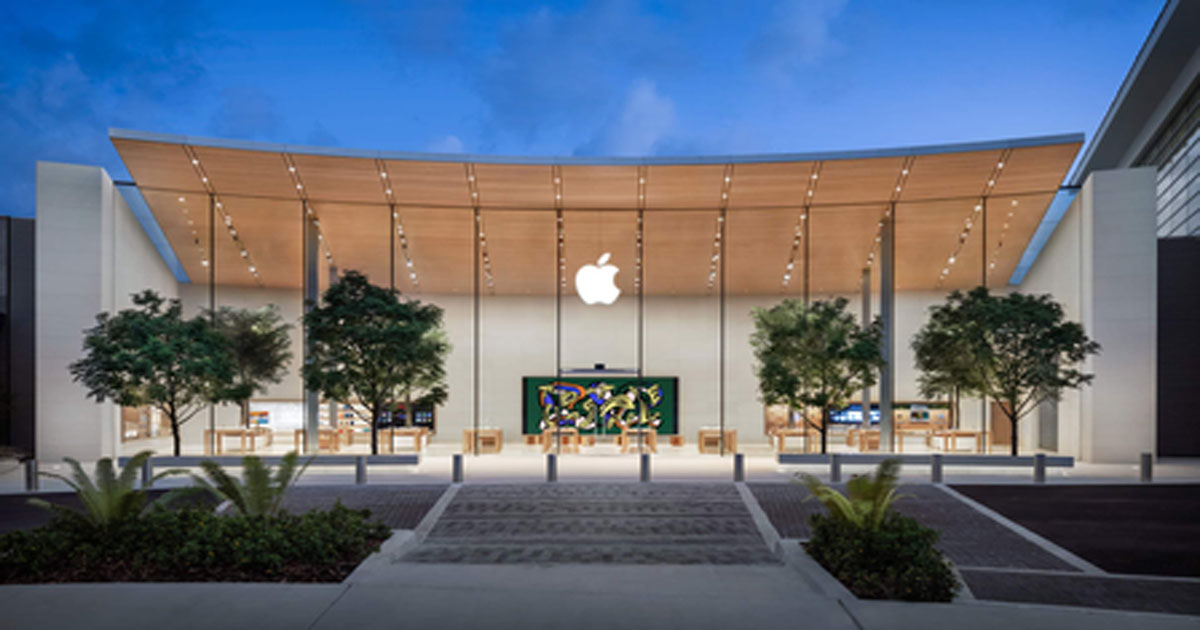
New Delhi, May 7: US tech giant Apple has announced an investment of Rs 100 crore to support the development of renewable energy infrastructure in India as part of its broader sustainability and carbon neutrality goals.
The company said the investment will be made in collaboration with CleanMax, one of India’s leading renewable energy developers, to help build more than 150 megawatts of new renewable energy capacity across the country.
According to the iPhone maker, the planned capacity would be enough to power nearly 1.5 lakh Indian households annually and may be expanded further in the coming years.
The initiative is aimed at strengthening renewable energy adoption across Apple’s supply chain operations in India and supports the company’s target of becoming carbon neutral across its entire footprint by 2030.
“At Apple, our commitment to the environment is also a driving force for innovation across the company and around the world,” said Sarah Chandler, Apple’s Vice President of Environment and Supply Chain Innovation.
“We are proud to expand our efforts to invest in India’s clean energy economy and protect the country’s precious natural resources,” she added.
Moreover, the US-headquartered firm had earlier partnered with CleanMax on rooftop solar projects to power its offices and retail stores in India with 100 per cent renewable energy.
Apart from renewable energy investments, it also announced new partnerships in India focused on reducing plastic pollution and promoting green entrepreneurship.
The company said it is working with WWF-India to support recycling and waste management initiatives to improve material recovery and reducing plastic leakage into ecosystems.
The iPhone maker is also partnering with Acumen to provide grants and mentorship support to early-stage green enterprises working in areas such as waste management, regenerative agriculture, and circular economy solutions.


IndusInd Bank has dismissed former managing director and chief executive Sumant Kathpalia from the lender’s employment with immediate effect, following an internal disciplinary inquiry and decided to invoke malus and clawback provisions against him, according to an exchange filing by the bank.
Malus and clawback provisions are executive compensation mechanisms that enable a company to reduce, cancel, or recover performance-based pay (such as bonuses or stock awards).
The board, acting as the disciplinary authority, took the decision at a meeting on November 20 after considering a report submitted by an enquiry officer, a former Bombay High Court judge.
“Sumant Kathpalia had on April 29, 2025, submitted his resignation from the services of the Bank with effect from the close of working hours on April 29, 2025. At its meeting held on April 29, 2025, the Board took note of the aforesaid resignation and made the requisite disclosures in accordance with applicable regulatory requirements,” the filing said.
The lender said the malus and clawback provisions would apply from March 24, 2020, when Kathpalia was first appointed managing director and chief executive.
The bank said it had informed Kathpalia at the time of his resignation that he would remain in its employment until further notice. It subsequently initiated disciplinary proceedings under its internal code of conduct and placed him under suspension from June 18, 2025, pending completion of the proceedings.
Kathpalia’s resignation in April 2025 followed the discovery of accounting discrepancies in the bank’s derivatives portfolio, with an independent review estimating losses of nearly Rs 1,960 crore on the bank’s profit and loss account.
He submitted resignation, acknowledging “moral responsibility” for acts of commission and omission brought to his notice.
In Q1 FY27, the lender’s net interest income (NII) rose 1 per cent year-on-year to Rs 4,685 crore, while its gross non-performing asset (GNPA) ratio improved to 3.25 per cent. Gross slippages also declined to Rs 1,660 crore from Rs 2,567 crore a year ago.
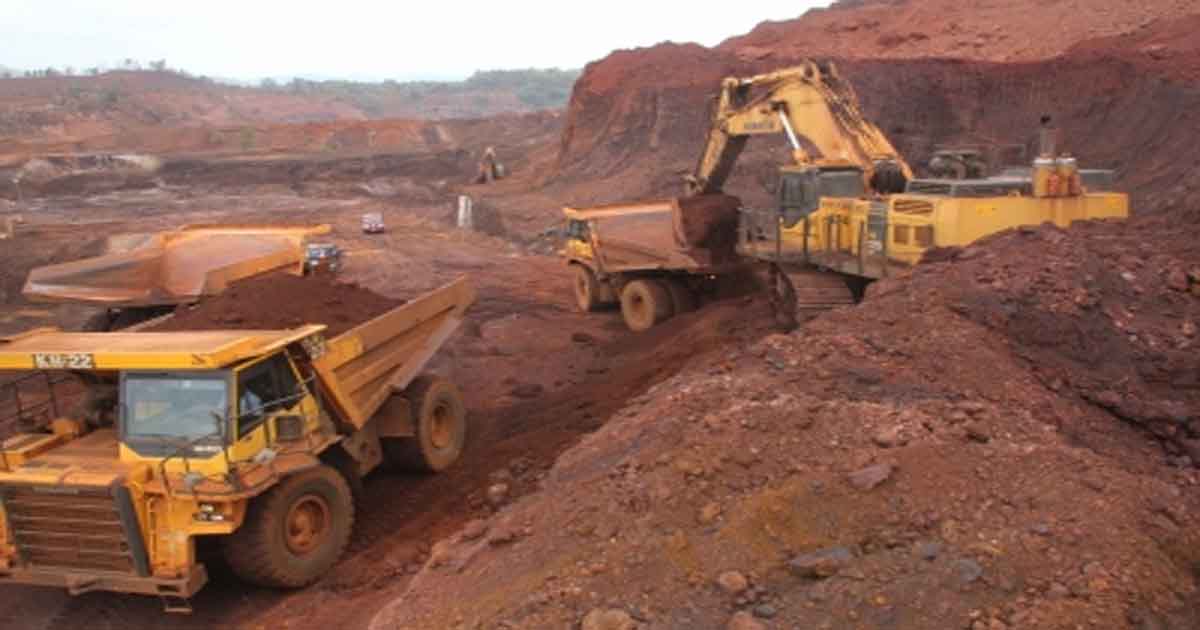
The growth rate of India’s core sector industries surged to 10.9 per cent in October this year, compared to the same month of the previous year, driven by the strong performance of the iron ore, coal, electricity, cement and steel sectors, according to figures released by the Ministry of Commerce and Industry on Friday.
The production of iron ore surged by as much as 26.4 per cent, while coal production went up by 23.1 per cent, and electricity generation grew by 21.6 per cent during October.
The cement sector clocked a robust growth of 15.4 per cent while steel production was up 7.3 per cent during the month, as demand stayed buoyant due to large government investments in big-ticket infrastructure projects such as highways, ports and railways.
The output of refinery products increased by 7.3 per cent during the month as demand for petroleum goods rose due to the higher level of economic activity. However, fertilisers, natural gas, and crude oil witnessed negative growth in October.
The final index for the month of September 2026 has been revised to 8.2 per cent, according to an official statement.
The cumulative growth rate of the index of core industries (ICI) during April-October 2026 works out to 6 per cent compared to the correspond figure of 2.3 per cent in the same period of the previous year.
The Office of Economic Adviser, Department for Promotion of Industry and Internal Trade (DPIIT) released the revised series of Index of Core Industries (ICI) with Base Year 2022-23 for the first time in July this year. The new series has replaced the earlier series of ICI with Base Year 2011- 12.
Owing to intensive use of iron ore in the production process, and its contribution to industrial development, it has been included in the list of core industries as a new item in the revised series of the index of core industries (ICI). Accordingly, the number of core industries increased from eight to nine in the new series.
Chief Minister Devendra Fadnavis said on Friday said that long-term planning, proper land management, timely execution of infrastructure projects, and boosting agricultural productivity are vital to Maharashtra’s all-round development.
He added that the state government is actively implementing a range of development initiatives to achieve these goals.
He made the remarks during a review meeting on Maharashtra’s development projects at his official residence, held with NITI Aayog Vice Chairman Ashok Kumar Lahiri.
Thanking NITI Aayog, the Chief Minister noted that the think tank has consistently provided guidance and practical advice to the state, expressing hope for continued support going forward. He reiterated that the administration is working in mission mode to complete development works at a set pace.
During the meeting, special emphasis was placed on long-term planning for land acquisition. Lahiri urged authorities to resolve pending issues related to land acquisition, infrastructure, and agriculture on priority.
Observing that land development and sound management can generate substantial revenue, Lahiri emphasised acquiring land needed for future development projects in advance and managing it effectively.
Land available at lower costs today can become far more valuable in the future, he said, calling for an ambitious land acquisition policy framed with future generations in mind.
He also expressed satisfaction with the progress of the state government’s flagship Vadhavan Port project.
Earlier, CM Fadnavis presented the state’s long-term development roadmap—anchored around the goal of making Maharashtra a $5-trillion economy by 2047, aligned with Viksit Bharat 2047.
He further stated that the government has laid focus on developing Mumbai Metropolitan Region (MMR) into a major economic engine, with NITI Aayog partnering on the city-region growth strategy to scale MMR’s economy from $140 billion toward $300 billion by 2030 and $1 trillion long-term.
A special development plan under post-Naxal development initiatives is being implemented to turn Gadchiroli into India’s first major integrated steel hub, alongside investments in infrastructure, education, healthcare, and employment.

6.7-magnitude earthquake hits Peru, tremors felt in Lima

Fire breaks out at warehouse in Delhi Burari, 10 fire tenders rushed to spot

‘No love equals a mother love’: CM Yogi bids tearful farewell to his ma at ancestral village

Ravi Kishan speaks fluent Marathi with Madhuri Dixit, reveals he is the only one who dubbed Spider-Man in Bhojpuri

Rajasthan Panchayat Elections: Re-polling on November 22 as EVMs at 28 booths fail to open

Congress trying to protect 3 crore Bangladeshi infiltrators in voter list: HM Shah

Red Fort car blast probe exposes blueprint for spread of terror modules across India

Trump flags Iran targets as talks continue

‘Conspiracy, not accident’: NCP on Ajit Pawar death

BJP, Shiv Sena slam Mallikarjun Kharge for terming Diwali ‘Khushiyon ka Eid’
-

 Crime4 years ago
Class 10 student jumps to death in Jaipur
-

 Maharashtra2 years ago
Mumbai Local Train Update: Central Railway’s New Timetable Comes Into Effect; Check Full List Of Revised Timings & Stations
-

 Maharashtra2 years ago
Mumbai To Go Toll-Free Tonight! Maharashtra Govt Announces Complete Toll Waiver For Light Motor Vehicles At All 5 Entry Points Of City
-

 Maharashtra2 years ago
False photo of Imtiaz Jaleel’s rally, exposing the fooling conspiracy
-

 National News2 years ago
Ministry of Railways rolls out Special Drive 4.0 with focus on digitisation, cleanliness, inclusiveness and grievance redressal
-

 Maharashtra2 years ago
Maharashtra Elections 2024: Mumbai Metro & BEST Services Extended Till Midnight On Voting Day
-

 National News2 years ago
J&K: 4 Jawans Killed, 28 Injured After Bus Carrying BSF Personnel For Poll Duty Falls Into Gorge In Budgam; Terrifying Visuals Surface
-

 Crime2 years ago
Baba Siddique Murder: Mumbai Police Unable To Get Lawrence Bishnoi Custody Due To Home Ministry Order, Says Report