Business
Global cues, domestic data plunge India’s equities; Sensex down over 1,600 pts
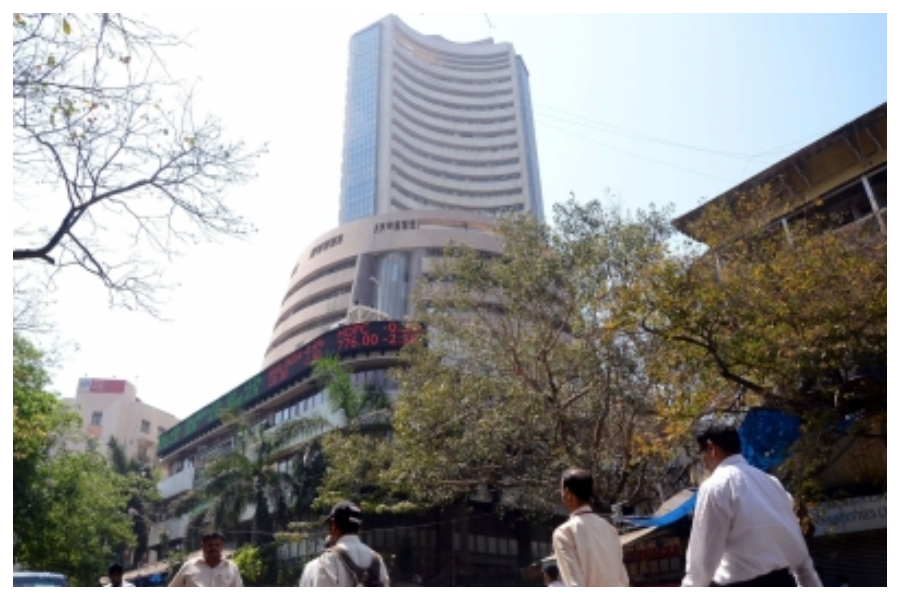
Global cues, such as heightened tensions between Russia and Ukraine, as well as the subdued industrial production data, plunged India’s key indices — S&P BSE Sensex and NSE Nifty50 — during late afternoon session on Monday.
Besides, high crude oil prices along with selling pressure from FIIs dragged the two indices lower.
Consequently, global stocks slid on Monday and commodities, including crude oil, surged as geopolitical risks over Ukraine rippled through global markets.
On the domestic front, volumes on the NSE were a little higher than the recent average.
Amongst sectors, realty, metals, banks and auto indices have lost the most.
At 2.45 p.m., Sensex traded at 56,493.85 points, down 2.85 per cent or 1,659.07 points from the previous close.
Nifty traded at 16,875.40 points, down 2.87 per cent or 499.35 points from the previous close.
“Nifty fell sharply for the second consecutive session on Feb 14, opening with a large down gap, following weak global cues,” said Deepak Jasani, Head of Retail Research, HDFC Securities.
“Nifty remains under pressure due to rising crude oil prices, the Russia Ukraine conflict and subdued Corporate results.”
Gaurav Garg, Head of Research, CapitalVia Global Research, said: “Investors around the world worried about increasing tensions between Russia and the West over Ukraine. The news that India’s industrial production fell to a 10-month low of 0.4 per cent in December 2021, owing to a contraction in manufacturing, kept the atmosphere on the streets cautious.
“Data from depositories showed that foreign portfolio investors (FPIs) withdrew a net Rs 14,935 crore from the Indian market in the first half of February, causing some alarm. On the global front, Asian market were in red as the rift between Russian and Ukraine has gone further with the increase in number of Russian troops at the Ukraine borders.”


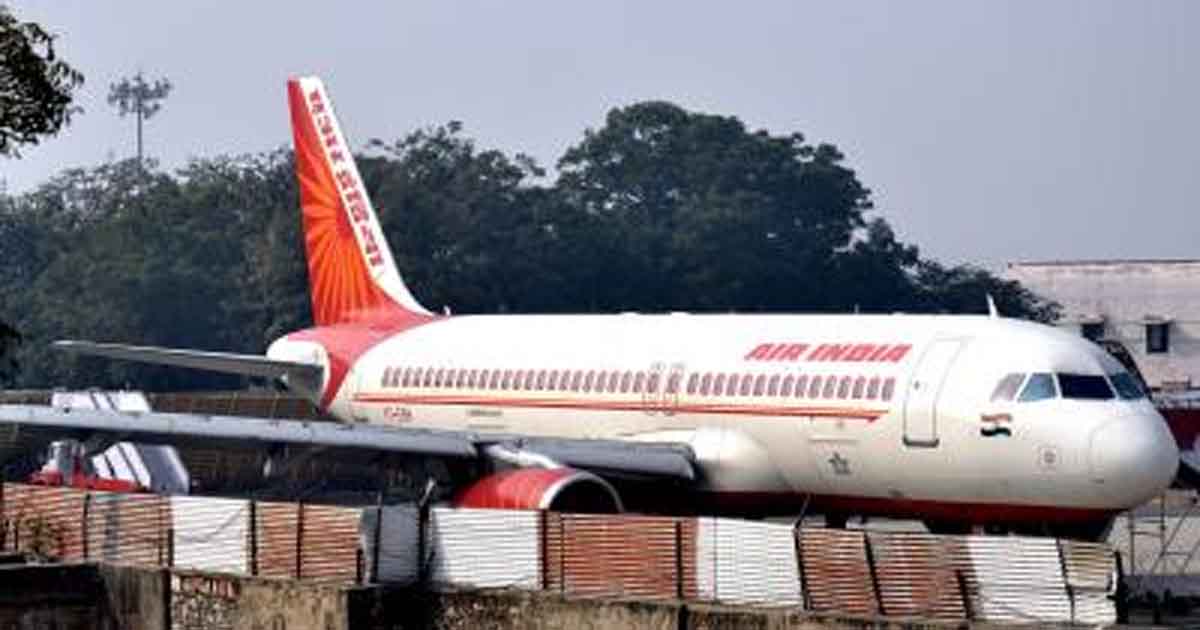
New Delhi : Air India on Saturday advised passengers to check the latest status of their flights and plan their journey to the airport accordingly, amid massive disruption at the US airports. The Federal Aviation Administration (FAA) lifted a nationwide ground stop that had halted departures at US airports after a communications failure, though airlines warned that disruption and cancellations could continue.
“A nationwide ground stop is currently in effect across the US due to communication outages affecting air traffic operations. As a result, departures from airports across US are impacted, with possible consequential disruptions to Air India flights to and from the US,” Air India said in a statement posted on X. “Our teams continue to closely monitor the situation and will share updates as available,” it added. The cancellation of US flights happened after a communications problem affected air traffic operations. The notice announcing the cancellation did not specify the cause of the failure or say that airline schedules had returned to normal.
Earlier, the FAA’s Air Traffic Control System Command Center said the ground stop remained in effect across a large portion of the country, although some coastal facilities had been able to release international departures. In an update, American Airlines said some flights from certain airports were beginning to receive clearance to depart. At that point, most departures remained paused, and the airline expected further disruption, including unavoidable cancellations. American advised customers to check their flight status and review its travel alert for options. Its warning was issued before the FAA’s cancellation advisory. Homeland Security Secretary Markwayne Mullin told reporters earlier that officials had acted as a precaution following a telecommunications outage affecting the FAA. “There is no indication as of yet that this was a nefarious attack,” he said at the time. That preliminary assessment did not rule out a cyberattack.
Washington : The FBI has warned that cybercriminals are using an artificial intelligence-assisted security testing tool to accelerate attacks on organisations around the world, with some intrusions reaching privileged access in less than three hours. In an alert issued on Friday (local time), the bureau said malicious actors had used the open-source framework, known as ARTEX, since at least August to target organisations across sectors including finance, government, technology, defence, energy and health care. The FBI said the tool can automate several stages of an intrusion, from identifying potential targets to preparing or carrying out data theft. That speed can leave defenders less time to detect and respond to an attack, it said.
The alert said some intrusions progressed from initial targeting to privileged access in under three hours. According to the alert, the framework was originally intended for authorised security testing. Its developer removed the original online repository in October following reports of malicious use, but copies and variants remained available, the FBI said. The bureau said the tool could lower the technical barriers for conducting complex operations and allow attackers to pursue multiple targets at the same time. Organisations’ internet-facing applications, cloud infrastructure and systems connected to suppliers or partners were among the areas of concern identified in the alert.
The FBI cited financially motivated attacks on South Korean financial institutions that it said resulted in personal information being taken from approximately 67,000 people. It also described a separate supply-chain compromise affecting users of a cloud backup service, which it said enabled access to more than 2,250 downstream customer environments. The bureau encouraged organisations to review their exposure to the internet, strengthen identity and access controls, monitor unusual activity and protect credentials. It also urged organisations that identify suspicious activity to contact the FBI or report it through the Internet Crime Complaint Center.
Business
India’s forex reserves climb $2.49 billion to $719.5 billion, gold holdings surge to $104.8 billion

India’s foreign exchange reserves rose by $2.49 billion to reach $719.547 billion in the week ended November 6, according to data released by the Reserve Bank of India (RBI) on Friday.
This increase follows consecutive weeks of decline, during which the reserves had slipped from $722.3 billion in the week ended October 17 to $717.057 billion by October 30.
The uptick in reserves was primarily driven by a sharp rise in gold holdings, which surged by $2.205 billion to $104.796 billion during the week, the RBI data showed.
Foreign currency assets, which form the largest component of India’s forex reserves, also rose by $232 million to $591.350 billion.
These assets are influenced by changes in the value of non-US currencies such as the euro, pound, and yen that are held in the reserves.
India’s Special Drawing Rights (SDRs) with the International Monetary Fund climbed by $52 million to $18.610 billion, while the country’s reserve position with the IMF increased by $1 million to $4.791 billion.
In rupee terms, the country’s total foreign exchange reserves stood at Rs 67,58,986 crore as of November 6.
Notably, the weekly increase in dollar terms came even as the reserves declined by Rs 49,742 crore in rupee terms, as per the data.
India’s forex reserves had previously touched an all-time high of $785.7 billion in the week ended September 4, following significant foreign currency inflows through a special concessional swap scheme for diaspora deposits.
Meanwhile, earlier this month, the central bank eased the foreign exchange reporting requirements for small exporters and importers of services.
Under the amended Foreign Exchange Management (Export and Import of Goods and Services) Regulations, 2026, individual service exporters will be deemed to have submitted the Export Declaration Form (EDF) once they provide the required payment-related information to their authorised dealer bank for crediting the proceeds to their accounts.
For exporters other than resident individuals, the same treatment will apply if the inward remittance for the service is not more than Rs 10 lakh or its equivalent in foreign currency.

BB 20: Yung DSA opens up on growing up amid parents’ financial struggles

Woman, two children die after jumping into well in MP’s Ratlam

Woman, lover conspire to kill husband for Rs 40,000 in Patna : three held

‘PM doesn’t do it’: Sam Pitroda on Rahul Gandhi’s phone tap claim

No merger, no NDA : Supriya Sule

Attack on democratic rights: INDIA Bloc leaders on detentions of anti-ECI protestors

Congress trying to protect 3 crore Bangladeshi infiltrators in voter list: HM Shah

Online betting: ED conducts searches at 20 premises in Mumbai, Pune, Hyderabad

Red Fort car blast probe exposes blueprint for spread of terror modules across India

Tiger Shroff attack: Bihar family denies accused is their son
-

 Crime4 years ago
Class 10 student jumps to death in Jaipur
-

 Maharashtra2 years ago
Mumbai Local Train Update: Central Railway’s New Timetable Comes Into Effect; Check Full List Of Revised Timings & Stations
-

 Maharashtra2 years ago
Mumbai To Go Toll-Free Tonight! Maharashtra Govt Announces Complete Toll Waiver For Light Motor Vehicles At All 5 Entry Points Of City
-

 Maharashtra2 years ago
False photo of Imtiaz Jaleel’s rally, exposing the fooling conspiracy
-

 National News2 years ago
Ministry of Railways rolls out Special Drive 4.0 with focus on digitisation, cleanliness, inclusiveness and grievance redressal
-

 Maharashtra2 years ago
Maharashtra Elections 2024: Mumbai Metro & BEST Services Extended Till Midnight On Voting Day
-

 National News2 years ago
J&K: 4 Jawans Killed, 28 Injured After Bus Carrying BSF Personnel For Poll Duty Falls Into Gorge In Budgam; Terrifying Visuals Surface
-

 Crime2 years ago
Baba Siddique Murder: Mumbai Police Unable To Get Lawrence Bishnoi Custody Due To Home Ministry Order, Says Report