Business
CPI inflation likely peaked out; expected to moderate in February
India’s consumer price indexed inflation is expected to moderate in February 2022 from the levels in January, said Motilal Oswal Financial Services.
Notably, high commodities cost especially of transport fuel prices triggered a wider inflationary trend in January 2022.
As a result, India’s main inflation gauge — Consumer Price Index (CPI) — which denotes retail inflation surged on a sequential as well as year-on-year basis.
The index rose to 6.01 per cent last month from 5.66 per cent in December 2021 and 4.06 per cent recorded for January 2021.
Accordingly, the retail inflation rate crossed the target range of the Reserve Bank of India.
The central bank has a CPI target range of 2-to-6 per cent.
Besides, the rate of rise in the Consumer Food Price Index, which measures the changes in retail prices of food products, increased to 5.43 per cent last month from 4.05 per cent in December 2021.
“CPI is likely to have peaked out and may moderate to 5.7 per cent YoY in February 2022. Moreover, growth is a bigger concern in India right now rather than inflation,” said Motilal Oswal Financial Services.
“In fact, we expect real GDP to grow 5-5.5 per cent YoY versus the market consensus of 6 per cent. Accordingly, we believe monetary policy normalisation would be gradual in India.”
Furthermore, food inflation came in at a 14-month high of 5.4 per cent YoY in January 2022 versus 4 per cent YoY in December 2021 and 1.9 per cent YoY in January 2021.
“Within food, vegetables were the major cause of upward movement in prices; excluding vegetables, CPI came in at a nine month low of 6.1 per cent YoY in January 2022.”
“Other items such as cereals and products, pulses and products, eggs, meat and fish, milk and milk products, and spices – which constitute 25 per cent weight in the CPI index – also contributed to the higher inflation.”

Business
Delhi protests put business worth Rs 400 crore at daily risk, exposure may reach Rs 4,000 crore in 10 days: CAIT

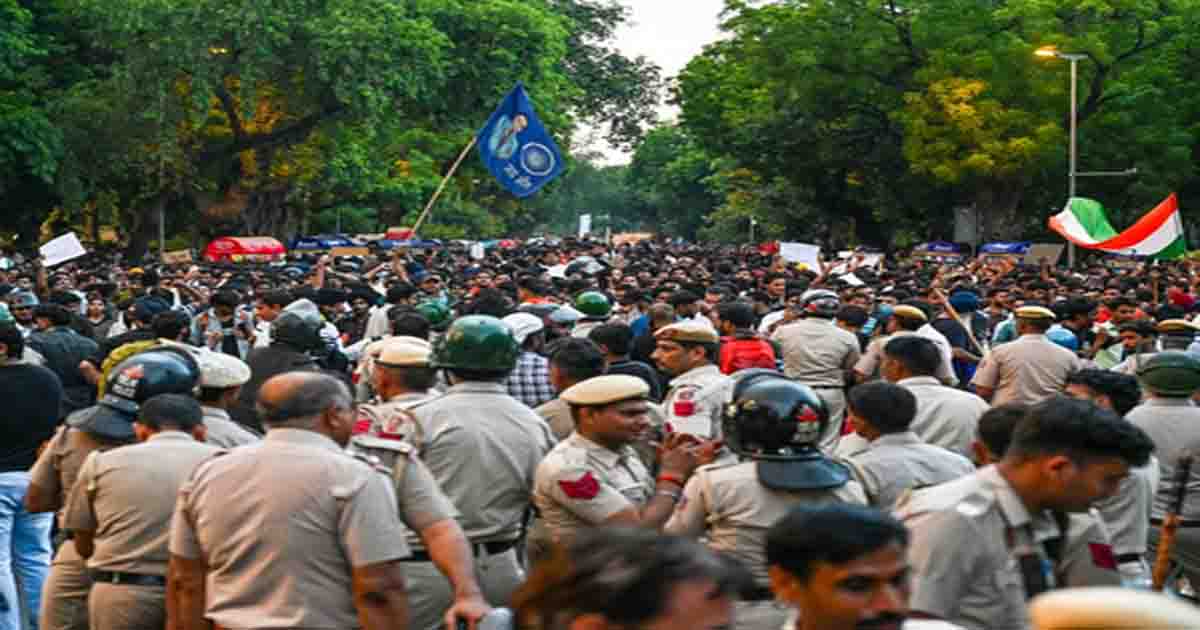
Protests in Delhi could put business transactions worth over Rs 400 crore at risk every day, with the potential exposure reaching Rs 4,000 crore over ten days if disruptions persist, Confederation of All India Traders (CAIT) Secretary General and Chandni Chowk MP Praveen Khandelwal said on Sunday.
Expressing concern over the economic impact of prolonged protests, Khandelwal said disruptions to traffic, transportation, customer movement and market accessibility could significantly affect the capital’s commercial activities, particularly during the crucial festive and wedding season.
He clarified that the figures represent indicative estimates of business activity at risk and not verified actual losses.
According to Khandelwal, Delhi’s estimated average daily business turnover stands at approximately Rs 2,200 crore. Even a 10 per cent decline in business activity could affect transactions worth Rs 220 crore daily, while a 15 per cent decline could put Rs 330 crore at risk. If the disruption reduces business activity by 20 per cent, the amount at risk could rise to Rs 440 crore per day.
Based on these estimates, the cumulative exposure could approach Rs 4,000 crore over ten days if disruptions continue at the higher end of the projected range.
Khandelwal emphasised that while the Constitution guarantees citizens the right to freedom of speech and peaceful assembly, traders must also be able to conduct their businesses and earn their livelihoods without avoidable disruptions.
“Delhi is not merely the national capital; it is one of the country’s most important centres of wholesale distribution, retail trade and commercial activity. Its markets connect manufacturers, distributors, retailers and consumers across India. Any prolonged disruption in Delhi therefore has a cascading impact on supply chains, business transactions and livelihoods far beyond the city,” Khandelwal said.
“The right to protest and the right to trade are both integral to a functioning democracy. Protecting one should not mean disregarding the other. The larger public interest demands a responsible approach in which democratic expression, the rule of law, economic activity and the livelihood of millions of people are all duly respected,” Khandelwal noted.
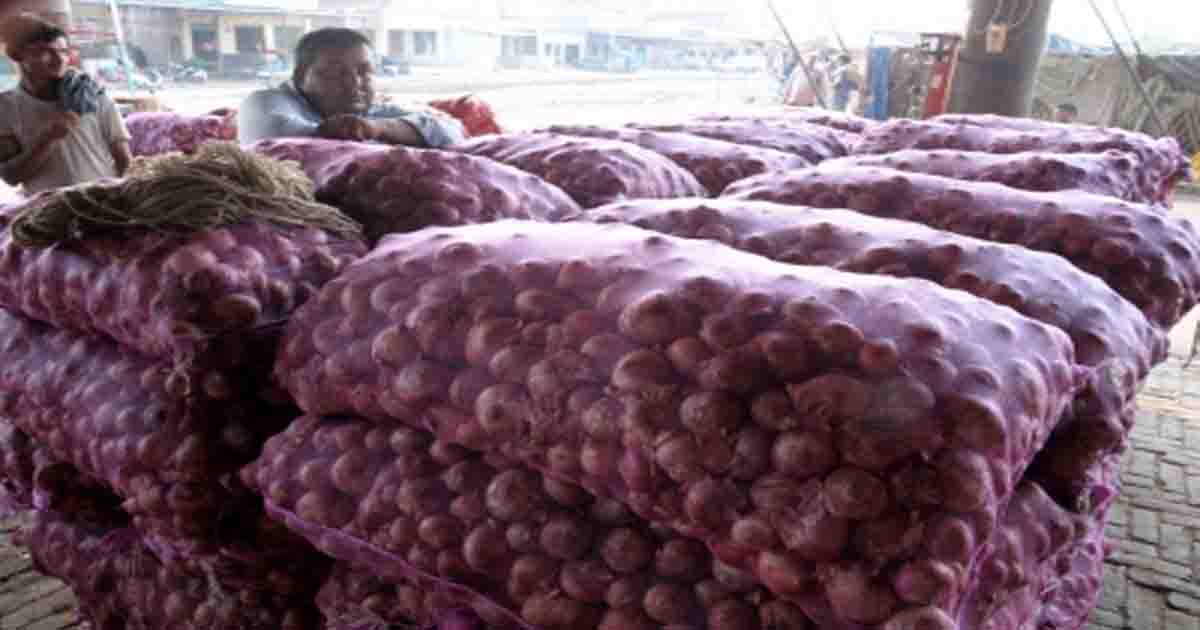
Salespersons at ration shops run by cooperative societies will receive an incentive of Rs 2 for every kilogram of onions sold under an initiative aimed at controlling retail prices and ensuring access to quality produce at reasonable rates.
The incentive was announced in a procedural order issued by Registrar of Cooperative Societies, Latha. It recognises the additional responsibilities undertaken by salespersons handling onion distribution alongside their regular ration shop duties.
According to the order, onions were procured in three phases from the National Agricultural Cooperative Marketing Federation of India (NAFED) and the National Cooperative Consumers’ Federation of India (NCCF). The procurement was undertaken to help check rising onion prices in the open market. The onions are being sold to the public through ration shops operated by cooperative societies.
The arrangement is intended to make quality onions available at fair prices while using the existing cooperative distribution network to reach consumers.
Under the order, the incentive payable to each salesperson will depend on the quantity of onions sold. The prescribed rate is Rs 2 per kilogram, linking payment directly to the volume handled through sales at the participating shops.
The Registrar’s order lists several additional tasks associated with the initiative. These include receiving onion consignments, storing the produce, sorting it, weighing quantities for customers, conducting sales and maintaining the related sales accounts. These responsibilities involve work beyond the routine distribution of ration commodities.
The incentive is intended to encourage salespersons to undertake the additional duties required to carry out onion sales through cooperative outlets. The amount due to eligible salespersons will be credited directly to their bank accounts through the Electronic Clearing Service (ECS), according to the order.
Payments will therefore be made through bank transfers based on the quantity sold. The measure combines consumer relief with an incentive for the staff responsible for implementing the sales programme.
While the procurement and distribution arrangement seeks to contain the impact of higher market prices, the additional payment acknowledges the work involved at the retail level. The order specifies a uniform incentive rate for onion sales conducted through the participating cooperative ration shops.
Foreign portfolio investors (FPIs) net sold about Rs 8,990 crore in the Indian markets last week, with a welcome, but modest, Rs 1,166 crore of buying on the last trading day.
On the provisional exchange data, FPIs sold Rs 1,708 crore on Monday, Rs 1,305 crore on Tuesday, Rs 1,857 crore on Wednesday and a hefty Rs 5,285 crore on Thursday.
However, the Friday’s buying also snapped a 15-session selling streak that had started on September 24. Over that stretch, FPIs had sold roughly Rs 84,000 crore on provisional numbers.
“October’s settled equity outflow has now reached about Rs 52,100 crore, already well above September’s Rs 35,861 crore, with two weeks of the month still to go. Calendar-2026 FPI equity outflows are now well over the rs 3 lakh crore mark,” said Dheeraj Gaur, Chief Investment Strategy Officer, Choice Wealth.
The primary-market cushion has also become thinner. September had provided a much needed offset, with strong foreign participation in primary issues.
Comparatively, October so far, has been much quieter, said the analyst.
“There is, however, one striking disconnect: FPIs are selling, but Indian equities are not behaving like a market under foreign-investor stress,” analysts noted.
The Nifty gained 2.8 per cent over the week to 23,146, while the Sensex rose 3.1 per cent. Nifty IT was the standout, jumping 11.7 per cent on optimism around AI-related revenues and technology earnings.
Domestic institutions once again played the shock absorber, buying heavily even as foreign investors continued to reduce exposure.
The IMF’s upward revision of India’s GDP growth forecasts for FY27 and FY28 reinforced confidence in the resilience of the domestic economy.
However, elevated crude level, rising retail and wholesale inflation, mixed global cues and persistent foreign fund outflows remained key concerns, according to market watchers.
Overall, optimism around domestic growth helped markets advance despite mounting inflationary pressures and global uncertainties. IT emerged as the standout performer on robust earnings and upbeat management commentary.

HM Amit Shah to visit Punjab on October 20

Prabhas’ ‘Spirit’ gets a new release date, to lock horns with Ranbir Kapoor’s ‘Ramayana part 2’

Delhi protests put business worth Rs 400 crore at daily risk, exposure may reach Rs 4,000 crore in 10 days: CAIT

Extremely heartbreaking: Rahul Gandhi on MP road accident

Couple killed, 3 minor daughters critical as speeding car hits bike in MP’s Pandhurna

Rahul, Cong ecosystem want to force regime change: BJP after Neha Bora praises B’desh Gen-Z protest

BJP pays tribute to ex-President Abdul Kalam, recalls his enduring influence on generations of India’s youth

Attack on democratic rights: INDIA Bloc leaders on detentions of anti-ECI protestors

INDIA bloc begins protest march against ECI

Maha Congress stages agitation against Gyanesh Kumar
-

 Crime4 years ago
Class 10 student jumps to death in Jaipur
-

 Maharashtra2 years ago
Mumbai Local Train Update: Central Railway’s New Timetable Comes Into Effect; Check Full List Of Revised Timings & Stations
-

 Maharashtra2 years ago
Mumbai To Go Toll-Free Tonight! Maharashtra Govt Announces Complete Toll Waiver For Light Motor Vehicles At All 5 Entry Points Of City
-

 Maharashtra2 years ago
False photo of Imtiaz Jaleel’s rally, exposing the fooling conspiracy
-

 National News2 years ago
Ministry of Railways rolls out Special Drive 4.0 with focus on digitisation, cleanliness, inclusiveness and grievance redressal
-

 Maharashtra2 years ago
Maharashtra Elections 2024: Mumbai Metro & BEST Services Extended Till Midnight On Voting Day
-

 National News2 years ago
J&K: 4 Jawans Killed, 28 Injured After Bus Carrying BSF Personnel For Poll Duty Falls Into Gorge In Budgam; Terrifying Visuals Surface
-

 Crime2 years ago
Baba Siddique Murder: Mumbai Police Unable To Get Lawrence Bishnoi Custody Due To Home Ministry Order, Says Report