Business
India’s Nov exports rise over 26%, imports over 57%

India’s merchandise exports in November rose to $29.88 billion, higher by 26.49 per cent on a year-on-year basis, preliminary data showed on Wednesday.
Exports in November 2020 stood at $23.62 billion.
According to the data furnished by the Ministry of Commerce and Industry, last month’s exports rose by 15.93 per cent over November 2019.
“Value of non-petroleum exports in November 2021 was $26.06 billion, registering a positive growth of 18.1 per cent over non-petroleum exports of $22.06 billion in November 2020 and a positive growth of 18.69 per cent over non-petroleum exports of $21.95 billion in November 2019.”
The value of non-petroleum and non-gems and jewellery exports rose to $23.66 billion, registering a positive growth of 22.16 per cent over November 2020.
As per the data, India’s merchandise imports last month increased by 57.18 per cent to $53.15 billion over $33.81 billion in November 2020 and 37.96 per cent over $38.52 billion reported for the corresponding month of 2019.
“Value of non-petroleum imports was $38.47 billion in November 2021 with a positive growth of 39.9 per cent over non-petroleum imports of $27.5 billion in November 2020 and a positive growth of 40.12 per cent over non-petroleum imports of $27.45 billion in November 2019.”
“Value of non-oil, non-GJ (gold, silver & Precious metals) imports was $32.02 billion in November 2021 with a positive growth of 41.53 per cent over non-oil and non-GJ imports of $22.63 billion in November 2020 and a positive growth of 42.72 per cent over non-oil and non-GJ imports of $22.44 billion in November 2019.”
Consequently, India’s trade deficit last month widened by 128.30 per cent YoY to $23.27 billion from $10.19 billion while it increased by 82.48 per cent when compared to $12.75 billion reported for November 2019.


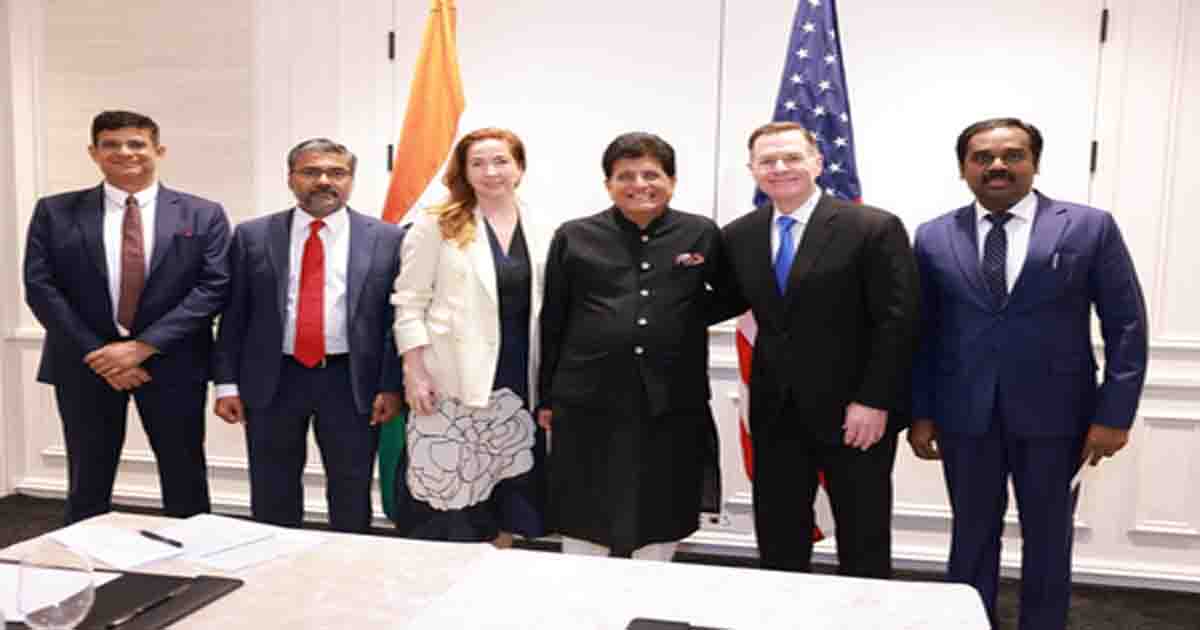
New Delhi, Oct 3: Commerce and Industry Minister Piyush Goyal on Saturday said he highlighted India’s growing strengths as a global hub for talent, innovation and business services, and the potential for deeper India-US business partnerships.
During his US visit, the minister met several global leaders and CEOs.
“Met Greg Case, CEO of Aon, and discussed the company’s operations in India and the opportunities for further expansion,” Goyal posted on social media platform X.
He also met Paul Grewal, Chief Legal and Global Affairs Officer at Cognition, and exchanged views on leveraging Cognition’s pioneering AI solutions and deepening its presence in India.
“Highlighted how India’s rich engineering ecosystem and dynamic startup culture provide a strong launchpad for building and deploying next-generation technologies for the world,” said Goyal.
During an engaging interaction with the Institute of Chartered Accountants of India (ICAI) leadership and members from Chicago, Michigan, and Ohio Chapters, the minister discussed the expanding opportunities in the India-US economic partnership and “highlighted how India’s economic momentum, marked by record FDI inflows and strong GDP growth, reflects PM Narendra Modi’s vision of a confident, self-reliant and globally competitive India”.
“Chartered Accountants have a pivotal role in strengthening this partnership by helping businesses navigate cross-border taxation, regulatory compliance and financial governance, while making Indian enterprises investment-ready for global capital,” the minister noted.
Goyal also delivered the keynote address at the USIBC Roundtable in Chicago.
“Discussed venture investment, commercialisation, and corporate partnerships to help Indian and US startups scale across markets. Explored opportunities to deepen India–US innovation linkages and foster the next generation of high-growth enterprises,” Goyal said.
He met Juan Ricardo Luciano, Chair of the Board and CEO of Archer Daniels Midland (ADM).
They discussed avenues to expand ADM’s presence and investment opportunities in India.
“With our rapidly expanding food processing sector, modernising agricultural value chains, and massive consumer base, India offers tremendous potential for sustainable growth and long-term collaboration,” said Goyal.
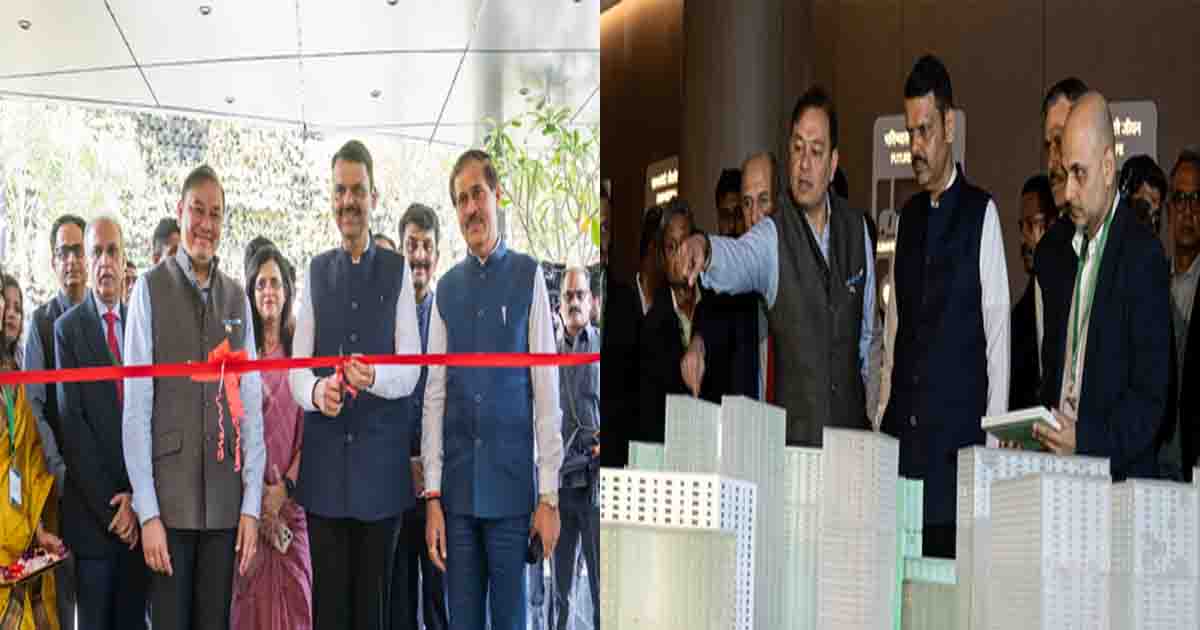
Mumbai, Oct 2: Maharashtra Chief Minister Devendra Fadnavis on Friday said that the ‘Dharavi Experience Centre’ will not merely showcase blueprints of the redevelopment project but allow the area’s residents to directly experience their future homes, neighbourhoods, and workplaces.
In an interaction with the media, he stated that this initiative will help curb rumours, misconceptions, and incomplete information, creating an atmosphere of trust around the redevelopment.
CM Fadnavis inaugurated the state-of-the-art ‘Dharavi Experience Centre’, which offers physical and digital previews of the Dharavi Redevelopment Project plan, rehabilitated homes, industrial spaces, and upcoming social infrastructure, built near the BKC in the PMGP Colony’s H Block.
The event was attended by Adani Group Managing Director Pranav Adani, BMC Commissioner Ashwini Bhide, Mumbai Slum Rehabilitation Authority (SRA) CEO Dr Mahendra Kalyankar, Dharavi Redevelopment Project CEO and SRA Secretary Vipin Paliwal, Adani Navbharat Developers Private Ltd (the Special Purpose Vehicle executing the redevelopment project) CEO Anil Sardana, among others.
After inspecting the centre, Fadnavis said: “Dharavi is not just a slum; it is a major economic engine. A significant economy thrives here through Kumbharwada’s pottery industry, leather business, food processing, plastic recycling, and various micro, small, and medium enterprises. The redevelopment plan respects these industries and focuses on providing them with better, well-planned workspaces. This is an effort toward comprehensive urban transformation while preserving Dharavi’s existing social, cultural, and economic identity.”
He added that this serves as an ideal example of the urban transformation taking place across the country under the leadership of Prime Minister Narendra Modi.
The Chief Minister noted that the ‘Dharavi Experience Centre’ will provide real-time information to everyone on how the Dharavi redevelopment project will look, what Dharavi is today, and how its structure will evolve in the future. This centre will play a crucial role in addressing the questions and confusion among Dharavi residents regarding their future post-redevelopment. He expressed confidence that by offering information on homes, roads, open grounds, social amenities, and employment opportunities all under one roof, the centre will be valuable for citizens, stakeholders, and urban planning researchers across the country.
The Dharavi Experience Centre highlights the journey from Dharavi’s present to its future transformation through modern audio-visual and digital technology. During his visit, CM Fadnavis also launched a special song titled “Dharavi Ka Kal”, sung by renowned singer Shankar Mahadevan, portraying the changing face of Dharavi, and released the book “Mere Sapno Ki Dharavi”.
Mumbai, Oct 2: Indian equity markets extended their losing streak to an eighth consecutive week on Thursday as benchmarks fell about 3 per cent each amid persistent foreign fund outflows, elevated US bond yields and geopolitical concerns.
Nifty 50 closed at 22,421.95, a decline of 3.1 per cent against the previous Friday’s closing of 23,140.5.
Similarly, Sensex declined 2.7 per cent to 71,909.7 compared with 73,895.7 a week earlier.
Broader markets also declined with midcap and smallcap indices falling 3.5 per cent and 3.3 per cent, respectively.
Sector-wise, BSE IT index was the only gainer, rising 0.2 per cent over the week.
In contrast, auto sector was the worst-performing sector, falling 5.5 per cent followed by consumer durables, down 5.3 per cent. FMCG and metal indices declined 4.2 per cent each, while energy, healthcare and realty indices fell between 3.3 per cent and 3.6 per cent. While banking, capital goods and power indices declined 2.4 per cent, 2.4 per cent and 2.6 per cent, respectively.
The latest decline marks the longest weekly losing streak for the benchmark indices in nearly 25 years.
Moreover, foreign institutional investors (FIIs) continued to sell Indian equities, while domestic institutional investors (DIIs) provided some support, cushioning the decline.
According to market experts, investor sentiment remained weak due to persistent geopolitical tensions, elevated crude prices, foreign fund selling and concerns over monetary policy.
Crude oil prices remained above $100 a barrel amid continued geopolitical tensions, while the US 10-year Treasury yield remained elevated, adding to pressure on emerging-market assets.
They further noted that the southwest monsoon ended with a 13 per cent rainfall deficit, raising concerns over agricultural output and food inflation.
The recent increase in minimum support prices for key rabi crops has also added to expectations of a cautious monetary policy stance, according to the experts.
Moreover, the Reserve Bank of India’s Monetary Policy Committee is scheduled to meet next week, with the policy decision due on October 7.
In addition, the coming week will also mark the start of the second-quarter earnings season.
The near-term market outlook could remain sensitive to global yields, crude oil prices, foreign fund flows and geopolitical developments, while the upcoming earnings season will provide further direction to equities, according to analysts.

Deported narco-trafficking kingpin Navpreet Singh sent to 10-day police custody

Kasturba Marg Police recover 100 stolen mobile phones, return them to their original owners

Iran to pursue US seizure of commercial ship during truce in international courts: official

SP changes 2 MLC candidates in UP; fields Akash Agrawal, Sanjay Tripathi

Capt Smit Machchhar under excellent medical care, recovering well: Indian Embassy in UAE

Gift to President Putin part of PM Modi bid to globally display India’s heritage

PM Modi’s warm camaraderie with Putin, Xi on full display at BRICS Summit

Corporators of all parties in trouble! Corporators of all major parties including Shiv Sena (UBT), BJP and Congress are facing legal challenges.

Complaint against Netflix & Mukesh Chhabra for inappropriate language on ‘India’s Got Latent 2’

Maha Congress stages agitation against Gyanesh Kumar
-

 Crime4 years ago
Class 10 student jumps to death in Jaipur
-

 Maharashtra2 years ago
Mumbai Local Train Update: Central Railway’s New Timetable Comes Into Effect; Check Full List Of Revised Timings & Stations
-

 Maharashtra2 years ago
Mumbai To Go Toll-Free Tonight! Maharashtra Govt Announces Complete Toll Waiver For Light Motor Vehicles At All 5 Entry Points Of City
-

 Maharashtra2 years ago
False photo of Imtiaz Jaleel’s rally, exposing the fooling conspiracy
-

 National News2 years ago
Ministry of Railways rolls out Special Drive 4.0 with focus on digitisation, cleanliness, inclusiveness and grievance redressal
-

 Maharashtra2 years ago
Maharashtra Elections 2024: Mumbai Metro & BEST Services Extended Till Midnight On Voting Day
-

 National News2 years ago
J&K: 4 Jawans Killed, 28 Injured After Bus Carrying BSF Personnel For Poll Duty Falls Into Gorge In Budgam; Terrifying Visuals Surface
-

 Crime2 years ago
Baba Siddique Murder: Mumbai Police Unable To Get Lawrence Bishnoi Custody Due To Home Ministry Order, Says Report