Business
RBI to cut policy repo rate by 25 bp on Dec 5: HSBC
New Delhi, Dec 1: Since inflation is set to remain well below target for the foreseeable future, HSBC Global Investment Research on Monday projected that the RBI will cut rates by 25 bp during its monetary policy committee (MPC) meeting on December 5 — taking the policy repo rate to 5.25 per cent.
Growth has been strong so far, benefitting from the front loading of government spending and GST-cut led retail spending.
However, the November Flash manufacturing PMI (56.6) indicated that GST-led boost may have peaked with the overall new orders coming in soft, said the report.
“Growth is strong for now, but could soften in the March 2026 quarter as the fiscal impulse becomes contractionary and exports slow. We expect the RBI to ease policy rates in the upcoming December policy meeting,” the report mentioned.
The July-September quarter GDP growth came in at 8.2 per cent YoY, higher than 7.8 per cent in the previous quarter and higher than “our above-consensus forecast of 7.5 per cent”. While GVA growth came in at 8.1 per cent, nominal GDP grew 8.7 per cent.
The GDP momentum was clearly higher than our above-consensus forecast. There are some good reasons for the strength, said the report.
One, GST rate cuts were implemented on the September 22, but the announcement was made on August 15.
“We think that production picked up in anticipation of a rise in consumer demand. Two, our recent work indicates that lower income states are starting to rise, even growing faster than the higher income states,” the HSBC report mentioned.
This, too, could possibly explain the strength in India’s growth momentum. After all, national GDP is the sum of state Gross State Domestic Products (GSDP).
According to the report, India’s growth has held up decently despite the 50 per cent reciprocal tariff on India’s exports by the US since August.


As long as Brent crude remains above $100 a barrel, there will be pressures on the economy and the foreign portfolio investors (FPIs) are likely to sell the dip, analysts said on Sunday.
The total FPI selling in October stands at Rs 53,337 crore so far, and the net FPI investment through the IPO market during this period stands at Rs 5,281 crore.
“The total FPI selling through the exchanges for this year stood at Rs 3,69,164 crore,” said Dr VK Vijayakumar, Chief Investment Strategist, Geojit Investments Ltd.
On the flows front, FIIs remained net sellers for the 10th straight week. For the week ended October 23, FIIs significantly reduced their selling and even turned buyers on two days.
The moderation in US bond yields with the 10-year yield declining from 5.36 per cent to around 5 per cent, appreciation in the rupee to 94.94 to the dollar and the low valuations, particularly of the large-caps, contributed to the moderation in FII selling.
Going ahead, the steady moderation in FII selling offers some comfort, though elevated crude and sharp broader-market weakness keep the downside risk alive.
A significant market trend during the week was the sharp correction in the mid-and small-caps.
The Nifty Mid-cap 100 plunged 5.6 per cent and the Nifty Small-cap 100 crashed 7.3 per cent during the week while the Nifty 50 was relatively resilient with a cut of only 2.35 per cent.
Forced liquidation in the margin-funded long positions in the broader market is rumoured to have triggered the crash in the broader market, said analysts.
The resilience of the large-caps is mainly due to the accumulation of the fairly valued large-caps by the DIIs which are flush with funds.
The high crude prices is acting as a strong headwind for the economy and market, said analysts.
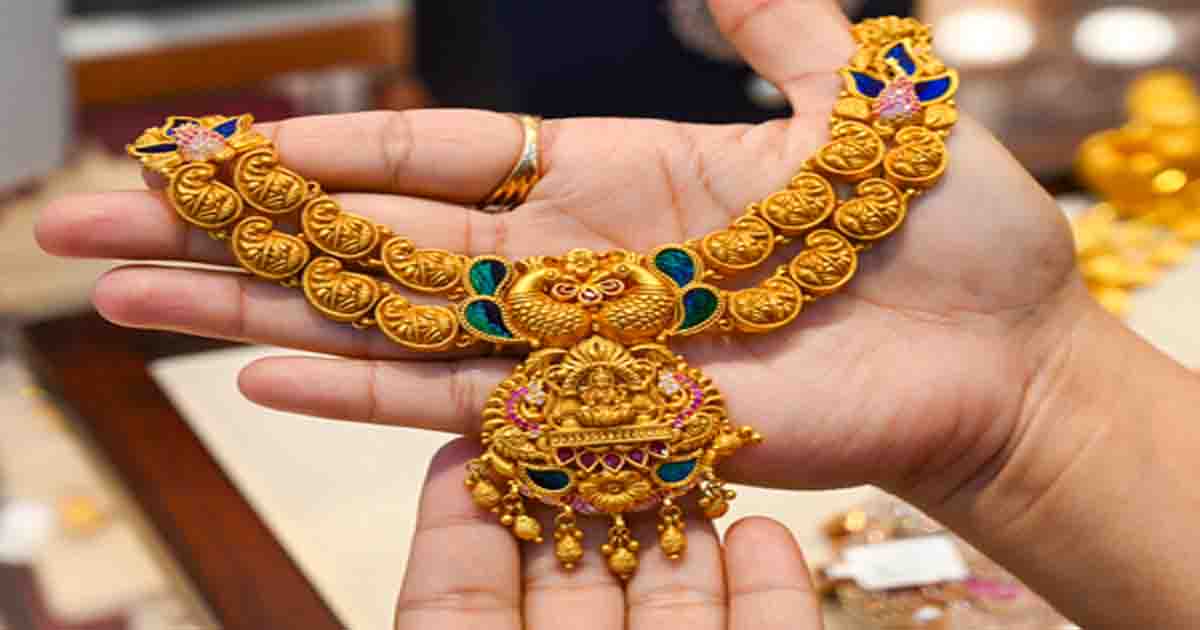
Gold prices dipped 3.28 per cent on a weekly basis, while silver prices declined 7.83 per cent this week, as rising crude oil prices heightened inflation fears.
The rising inflation concerns reinforced expectations that global interest rates will stay higher for longer, prompting a wave of selling across precious‑metals markets.
On Friday, MCX gold futures expiring December declined 0.81 per cent while MCX silver futures for December shed 1.75 per cent. Gold futures stood at Rs 1,42,150, while silver futures stood at Rs 1,96,100 per kg.
Gold saw its steepest weekly decline since June and slipped below the psychologically important $4,000 per ounce level for the first time since mid-July, analysts said.
The selloff in silver intensified over weakness in US technology stocks, particularly AI-linked companies, which triggered margin calls and forced investors to liquidate precious-metal holdings.
Meanwhile, crude oil surged to multi-month highs following renewed attacks on Saudi energy infrastructure and shipping routes, while the Indian rupee surrendered its early-week gains amid rising oil prices and renewed dollar demand.
However, lower prices encouraged physical gold purchases in India during the Dussehra festival, providing some underlying demand support, while Chinese jewellery demand remained subdued.
Market participants forecast that precious metals could remain under pressure if elevated energy prices reinforce inflation concerns and expectations of tighter monetary policy. However, physical demand and any moderation in bond yields could offer support following the recent correction, they said.
Markets largely expect the US Fed to keep interest rates unchanged at the October 27–28 policy meeting, but expectations of another rate hike in December remain elevated, with traders pricing approximately a 78 per cent probability.
Investors are also awaiting the US Personal Consumption Expenditures report next week for additional guidance on inflation and future interest-rate decisions.
Immediate resistance for Comex Gold is placed at $4,070–$4,100 zone, while support lies at $3,970–$4,000 zone, analysts said.
For MCX Gold, immediate resistance is placed at Rs 1,43,000–Rs 1,43,700 zone, while the support lies at Rs 1,40,000–Rs 1,41,000, they added.
The Directorate of Enforcement (ED), Hyderabad Zonal Office, on Friday conducted search operations at seven premises across Hyderabad, Secunderabad and Medchal-Malkajgiri in Telangana under the Prevention of Money Laundering Act (PMLA), an official statement said on Saturday.
The raids targeted the registered office of M/s Kanakadhara Ventures Pvt. Ltd. (KVPL), the residences of its directors, and premises linked to entities and individuals alleged to have acted as conduits for the diversion of bank funds.
The searches form part of an ongoing investigation into the alleged “misutilisation” and diversion of credit facilities sanctioned to KVPL and its directors, the ED statement said.
The ED case stems from an FIR dated December 8, 2022, registered by the Central Bureau of Investigation, Bank Securities and Fraud Branch (BS&FB), Bangalore, on a complaint from Punjab National Bank.
The FIR alleges offences under Sections 120-B, 420, 468 and 471 of the Indian Penal Code, and provisions of the Prevention of Corruption Act, 1988.
According to the agency, a consortium of banks led by Punjab National Bank — comprising IDBI Bank, Union Bank of India, Andhra Bank (now UBI) and Bank of Baroda — suffered a loss of Rs 326.49 crore.
ED investigations revealed that Bank Guarantee and Letter of Credit facilities granted to KVPL were misused. Funds were allegedly diverted through related and conduit entities on the strength of fabricated steel purchase invoices and transport documents.
The company is also accused of operating bank accounts outside the consortium arrangement without the knowledge of the lending banks, the statement said.
During the searches, officials seized incriminating documents, digital devices and other records related to the diversion and layering of funds. Unaccounted cash amounting to Rs 15 lakh was also recovered.
Multiple immovable properties and investments linked to the case have been identified.
ED said further investigation is underway.
The coordinated action underscores the agency’s continued focus on tracing the proceeds of bank frauds and cracking down on complex money-laundering networks involving corporate entities.

Drug dealer arrested in Mumbai with 1.5 kg of charas (cannabis resin)

Lawrence Bishnoi gang shooters had practised shooting in the Aarey Colony forest before opening fire at Tiger Shroff’s residence.

PM Modi witnesses IAF’s air show, inaugurates garment facility in Varanasi

Major action by Mumbai ANC: Drug peddlers arrested.

Delhi Police bust Jamtara-based cyber fraud syndicate, 2 held for credit card fraud

Rahul, Cong ecosystem want to force regime change: BJP after Neha Bora praises B’desh Gen-Z protest

Attack on democratic rights: INDIA Bloc leaders on detentions of anti-ECI protestors

BJP pays tribute to ex-President Abdul Kalam, recalls his enduring influence on generations of India’s youth

INDIA bloc begins protest march against ECI

Maha Congress stages agitation against Gyanesh Kumar
-

 Crime4 years ago
Class 10 student jumps to death in Jaipur
-

 Maharashtra2 years ago
Mumbai Local Train Update: Central Railway’s New Timetable Comes Into Effect; Check Full List Of Revised Timings & Stations
-

 Maharashtra2 years ago
Mumbai To Go Toll-Free Tonight! Maharashtra Govt Announces Complete Toll Waiver For Light Motor Vehicles At All 5 Entry Points Of City
-

 Maharashtra2 years ago
False photo of Imtiaz Jaleel’s rally, exposing the fooling conspiracy
-

 National News2 years ago
Ministry of Railways rolls out Special Drive 4.0 with focus on digitisation, cleanliness, inclusiveness and grievance redressal
-

 Maharashtra2 years ago
Maharashtra Elections 2024: Mumbai Metro & BEST Services Extended Till Midnight On Voting Day
-

 National News2 years ago
J&K: 4 Jawans Killed, 28 Injured After Bus Carrying BSF Personnel For Poll Duty Falls Into Gorge In Budgam; Terrifying Visuals Surface
-

 Crime2 years ago
Baba Siddique Murder: Mumbai Police Unable To Get Lawrence Bishnoi Custody Due To Home Ministry Order, Says Report