Business
Maharashtra forms Kelkar panel to tackle fiscal stress, boost revenues
Mumbai, Sep 17: In a major push to reinforce Maharashtra’s fiscal health and support its long-term growth roadmap, Maharashtra Chief Minister Devendra Fadnavis announced the constitution of the Maharashtra Sustainable Public Finance Committee.
Headed by renowned economist and former Union Finance Secretary Dr Vijay Kelkar, the high-level panel, which was announced late Wednesday evening, is tasked with recommending measures to ensure sustainable growth in tax and non-tax revenues.
The decision forms an integral part of the state’s ‘Viksit Maharashtra @ 2047’ vision document, which outlines a strategic roadmap to scale the state’s economy to $1 trillion by 2030 and $5 trillion by 2047—coinciding with the centenary of India’s Independence.
The panel has been tasked with making recommendations to modernise the tax system, plug revenue leakages, and rationalise tax rates, fees, and exemptions; identify untapped revenue streams and maximise returns from public assets and state enterprises; streamline public spending while balancing expanding committed expenditures such as salaries, pensions, interest payments, and welfare schemes; and devise a fiscally responsible roadmap to reduce reliance on borrowings for infrastructure projects and budget deficits.
The Kelkar Committee comprises Prof Karthik Muralidharan (founder-director, CEGIS), Dr Nitin Kareer (former Chief Secretary, Maharashtra), T Rabi Sankar (former Deputy Governor, Reserve Bank of India) and Dr Ashima Goyal (President, The Indian Econometric Society).
The formation of the panel comes at a critical juncture for Maharashtra. While the state actively pursues an investment-led growth strategy across core sectors—including infrastructure, human resource development, water security, urban management, and energy transition—it faces growing fiscal constraints.
Maharashtra government’s Vision document has suggested restructuring the government expenditure policy to align with long-term capital formation, identifying alternative financing models and private capital inflows.
Fiscal deficit targets are capped within standard Fiscal Responsibility and Budget Management (FRBM) boundaries, targeting 2.8 per cent to 3.0 per cent of Gross State Domestic Product (GSDP) while keeping the revenue deficit under 0.7 per cent of GSDP, and implementation is tracked quarterly via a dedicated Vision Management Unit chaired by the chief minister.
Adhering to the targets set under the FRBM Act has proved challenging due to rising welfare commitments and debt servicing costs. Consequently, the government has frequently resorted to market borrowings to fund capital projects and offset short-term liquidity shortfalls.
The newly appointed Kelkar Committee is expected to deliver structural fiscal remedies to reverse this trend and secure long-term financial sustainability for the state.


Maharashtra Chief Minister Devendra Fadnavis on Thursday directed the transport department to build a state-of-the-art digital platform to provide real-time information on aggregator companies’ vehicles, drivers, and working hours, aiming to make app-based passenger transport services in the state safer, more transparent, and well-organised.
He instructed that this platform should integrate Artificial Intelligence (AI)-based analytics to maintain effective control over vehicle operations, driver dispatch, parking management, and passenger services.
CM Fadnavis gave these instructions during a meeting concerning the Maharashtra Aggregator Rules-2026. The review covered the growing number of vehicles in the aggregator sector, the challenges faced by independent taxi drivers, passenger safety, and transparency in ride allocation on digital platforms. Transport Minister Pratap Sarnaik, Additional Chief Secretary (Transport) Sanjay Sethi, Transport Commissioner Rajesh Narvekar, and other transport department officials were present.
The Chief Minister directed that complete digital details must be available for every vehicle operated by aggregator companies. This includes registration, assigned parking locations, driver profile, driving license, police verification, and other required documents.
Additionally, the system must maintain real-time logs indicating which driver is operating which vehicle across various shifts throughout the day. In the event of an incident, a robust mechanism should ensure that details regarding the vehicle and driver are immediately accessible.
By leveraging artificial intelligence on this platform, the system will analyse vehicle operations, driver shifts, and other critical parameters. This will allow regulatory authorities to monitor compliance with rules and enable prompt action whenever necessary, he said.
CM Fadnavis highlighted the need to verify whether independent taxi drivers and large fleet management companies receive equal opportunities when rides are allocated on app-based transport platforms.
He noted that it is essential to audit the criteria and reasons based on which specific vehicles are assigned rides on digital platforms. He directed officials to utilise technology to detect any bias or unfair discrimination in ride allocation algorithms.
The Chief Minister stressed that while passengers must receive safe and reliable service, local drivers must also get equal employment opportunities.
To achieve this, priority must be given to effective enforcement of rules, transparent ride allocation, and technical oversight of aggregator operations.
In light of the expansion of the state’s aggregator sector and growing passenger needs, he directed the Transport Department to develop an efficient, technology-driven regulatory framework that balances the interests of independent taxi drivers, passenger safety, and overall traffic discipline.
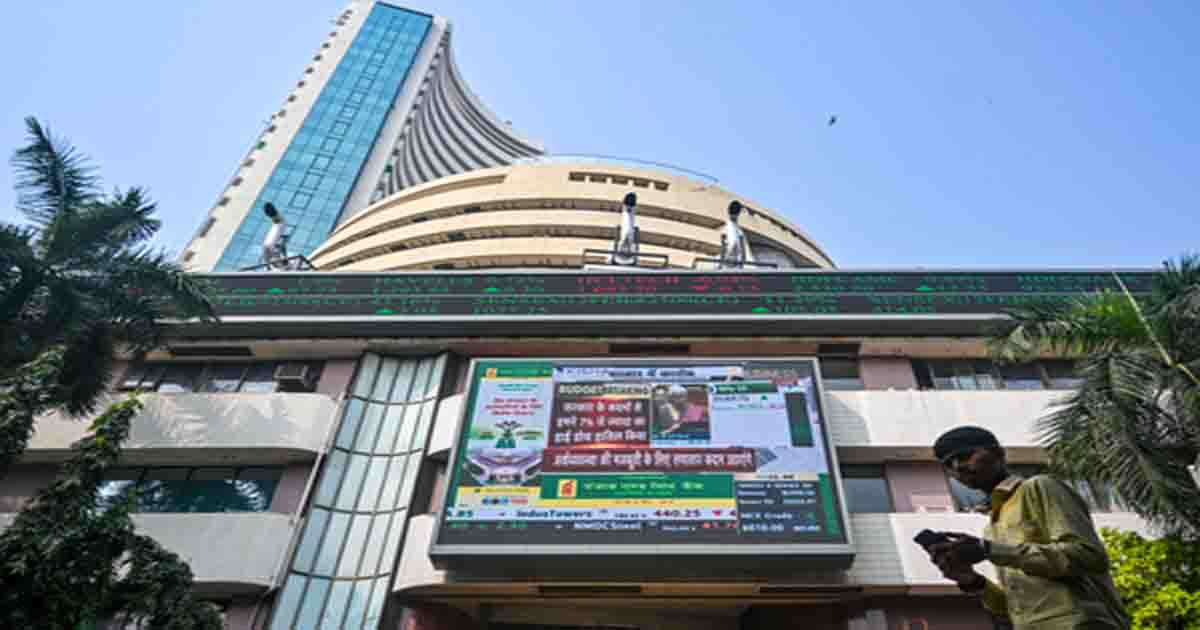
The Indian equity markets opened with mild gains early on Thursday despite mixed global cues and elevated crude prices.
As of 9.25 am, Sensex added 168 points, or 0.23 per cent, to reach 73,414 and Nifty gained 45 points, or 0.20 per cent, to reach 22,744.
Main broad-cap indices performed in line with the benchmark indices, as the Nifty Midcap 100 gained 0.25 per cent, and the Nifty Smallcap 100 added 0.13 per cent.
Sectoral indices on NSE traded mixed with gains led by Nifty IT, up 0.80 per cent and pharma, up 0.30 per cent. Nifty private bank and media were among top losers, down 0.18 per cent and 0.16 per cent, respectively.
The opening gain of benchmarks may remain selective unless the Nifty decisively crosses 22,800, as the Federal Reserve’s policy message, elevated crude and high US bond yields continue to restrict broader risk-taking, an analyst said.
Brent crude remains elevated near $114.50 a barrel amid persistent geopolitical uncertainty, keeping energy costs high and leaving oil-sensitive sectors exposed to sustained cost pressures.
The Federal Reserve kept its policy rate unchanged, but two members voted for an increase, and markets raised expectations of another hike in December. The US 10-year Treasury yield consequently moved to around 5.02 per cent, indicating that the policy pause has not materially loosened global financial conditions.
Unless yields stabilise below recent levels, dollar assets may continue competing with emerging markets for capital and limit the durability of foreign inflows into India, market participants said.
In the previous session, Nifty closed at 22,698, down 0.22 per cent, after a recovery was capped by profit booking. Immediate support is placed at 22,600–22,650, while resistance is seen at 22,850–22,900.
In the previous session, Bank Nifty closed at 54,267, up 0.54 per cent. Immediate support is placed at 53,800–54,000, while resistance is seen at 54,600–54,800.
In Asian markets, China’s Shanghai index declined 0.82 per cent, and Shenzhen dipped 2.48 per cent, Japan’s Nikkei added 0.28 per cent, and Hong Kong’s Hang Seng Index advanced 0.06 per cent. South Korea’s Kospi lost 2.72 per cent.
The US markets ended in green overnight as Nasdaq added 0.27 per cent, S&P 500 gained 0.28 per cent, and the Dow Jones inched up 0.19 per cent.
On October 28, foreign institutional investors (FIIs) net bought equities worth Rs 872 crore, while domestic institutional investors (DIIs) bought equities worth Rs 643 crore.
Prime Minister Narendra Modi will inaugurate Bharat Renewable Energy Summit & Expo (BRESE) 2026 on 2nd November, which will bring together participants from over 130 countries, including global leaders, investors, industry and innovators, at Bharat Mandapam here.
Australia, Denmark, the European Union, France, Germany, Netherlands, Norway, Sweden and the United Kingdom will participate as country partners.
Secretary, Ministry of New and Renewable Energy, Santosh Sarangi, on Wednesday said, “India’s clean energy transition is entering a decisive phase. With 308 GW of installed non-fossil fuel capacity, we are firmly on course to reach our 500 GW target by 2030. Realising this ambition will require approximately USD 220 billion in investment between 2027 and 2030, alongside accelerated deployment of energy storage, stronger transmission networks and expanded domestic manufacturing capabilities.”
He told journalists that the Bharat Renewable Energy Summit & Expo 2026 will provide a vital platform to connect global capital, technology and industry expertise with India’s growing clean energy opportunities, translating investment potential into projects, partnerships and progress.
The four-day event, themed ‘Invest. Innovate. Inspire’, will be organised alongside the 9th Session of the International Solar Alliance (ISA) Assembly and the 4th International Conference on Green Hydrogen (ICGH).
The three events will provide a common platform for discussions on renewable energy investment, international cooperation, emerging technologies and clean energy deployment.
Delegations from several countries are also expected to attend the Summit to explore cooperation opportunities in renewable energy financing, green hydrogen, energy storage, clean energy manufacturing, and technology development.
Thirteen States and Union Territories will participate in the Summit, including Andhra Pradesh, Assam, Bihar, Chhattisgarh, Delhi, Gujarat, Karnataka, Madhya Pradesh, Maharashtra, Odisha, Rajasthan, Uttar Pradesh and West Bengal, showcasing their renewable energy potential, investment opportunities and manufacturing capabilities. Other participating states will also highlight opportunities for renewable energy development and investment.
India ranks third globally in renewable energy and solar installed capacity and fourth in wind power capacity, as it advances towards its target of 500 GW by 2030. India invested USD 63.7 billion in its renewable energy sector during July 2024–June 2026, as per BloombergNEF.
Building on this momentum, the Summit will bring together global policymakers, investors, industry leaders and innovators to strengthen international cooperation, mobilise investment and accelerate renewable energy deployment, particularly across emerging economies and the Global South.
The four-day conference will feature high-level plenaries, ministerial discussions, CEO roundtables, and country and state sessions focused on financing, policy, technology, and skilling.
Discussions will cover clean energy investment, emerging technologies, manufacturing, energy storage, and workforce development, with an emphasis on technology exchange, scalable solutions, and greater participation and leadership by women in the global energy transition.

Pradeep Purnekar murder case: Aaditya Thackeray accuses Eknath Shinde of protecting ‘conspirators’

Delhi Police register FIR against unknown persons in Jamia vandalism case

CBI conducts searches in SBI fraud case against Aaj Ka Anand Papers Pvt Ltd

MLC poll result calls for self-introspection: Maha Dy CM Pawar

Internal conflict escalates within Mahayuti following Maharashtra Legislative Council election results

Rahul, Cong ecosystem want to force regime change: BJP after Neha Bora praises B’desh Gen-Z protest

Attack on democratic rights: INDIA Bloc leaders on detentions of anti-ECI protestors

BJP pays tribute to ex-President Abdul Kalam, recalls his enduring influence on generations of India’s youth

INDIA bloc begins protest march against ECI

Gujarat govt to honour Flydubai captain Smit Machchhar with ‘Vishisht Gujarat Garima Award’, Rs 25 lakh reward
-

 Crime4 years ago
Class 10 student jumps to death in Jaipur
-

 Maharashtra2 years ago
Mumbai Local Train Update: Central Railway’s New Timetable Comes Into Effect; Check Full List Of Revised Timings & Stations
-

 Maharashtra2 years ago
Mumbai To Go Toll-Free Tonight! Maharashtra Govt Announces Complete Toll Waiver For Light Motor Vehicles At All 5 Entry Points Of City
-

 Maharashtra2 years ago
False photo of Imtiaz Jaleel’s rally, exposing the fooling conspiracy
-

 National News2 years ago
Ministry of Railways rolls out Special Drive 4.0 with focus on digitisation, cleanliness, inclusiveness and grievance redressal
-

 Maharashtra2 years ago
Maharashtra Elections 2024: Mumbai Metro & BEST Services Extended Till Midnight On Voting Day
-

 National News2 years ago
J&K: 4 Jawans Killed, 28 Injured After Bus Carrying BSF Personnel For Poll Duty Falls Into Gorge In Budgam; Terrifying Visuals Surface
-

 Crime2 years ago
Baba Siddique Murder: Mumbai Police Unable To Get Lawrence Bishnoi Custody Due To Home Ministry Order, Says Report