Business
India Lost ₹22,842 Crore To Cybercriminals & Fraudsters In 2024: DataLEADS
India lost Rs 22,842 crore to cybercriminals and fraudsters in 2024, DataLEADS, a Delhi-based media and tech company, said in its report on widespread digital financial frauds in the country. The amount stolen by digital criminals and fraudsters last year was nearly three times more than the Rs 7,465 crore in 2023 and almost 10 times more than the Rs 2,306 in 2022, DataLEADS said in ‘Contours of Cybercrime: Persistent and Emerging Risk of Online Financial Frauds and Deepfakes in India.
Prediction For Cyber-Crime Frauds
The Indian Cybercrime Coordination Centre, I4C, a federal agency that liaises between state and central law enforcement, predicts Indians will lose over Rs 1.2 lakh crore this year. The number of cybercrime complaints has spiked similarly; nearly twenty lakh were reported in 2024, up from around 15.6 lakh the year before and ten times more than were logged in 2019.
The surge in the number of cybercrime complaints and the volume of money lost points to one inescapable conclusion – India’s digital crooks are getting smarter and more efficient, and, in a country with a staggering nearly 290 lakh unemployed people, their ranks are increasing.
Bank-related frauds have increased dramatically; the Reserve Bank of India reported a nearly eightfold jump in the first half of FY 2025/26 compared to the same period last year. And the amount of money lost was staggering – Rs 2,623 crore to Rs 21,367 crore. Private sector banks accounted for nearly 60 per cent of all such incidents. But it was customers in public sector banks who were worst-hit; they lost Rs 25,667 crore in all.
Why have these numbers jumped so much over the past three years?
Because of the increased use of digital payment modes – i.e., smartphone-enabled services like Paytm and PhonePe – and the sharing and processing of financial details online – via (what many believe are encrypted and fail-safe) messaging platforms like WhatsApp and Telegram.
Federal data says there were over 190 lakh UPI, or unified payment interface, transactions in June 2025 alone, and these were worth a combined Rs 24.03 lakh crore. Digital payments’ value has grown from roughly Rs 162 crore in 2013 to Rs 18,120.82 crore in January 2025, and India accounts for nearly half of all such payments worldwide.
COVID-19
Much of this increase can be attributed to the pandemic and the subsequent lockdowns.
During COVID-19, the government pushed for a switch to UPI apps like Paytm to ensure social distancing and minimise contact with currency notes, via which the virus could be transmitted.
Digital Payment Tools In Rural Areas
The government also reasoned that digital payment tools would ensure greater penetration of financial services, particularly in rural areas. By 2019, India already had 440 million smartphone users and data rates were among the cheapest in the world – 1 GB cost Rs 200, or less than $3.
Insurance sector scams were also common. These included life, health, vehicle, and general, and are becoming an increasingly lucrative option for cybercriminals, particularly as insurance companies urge customers to opt for app-based services.


The Ministry of Electronics and Information Technology (MeitY) has asked technology giant firm Meta to review the content recommendation and ranking systems that power Facebook and Instagram, stepping up regulatory scrutiny of how social media algorithms amplify information in India, according to multiple reports.
In an advisory issued to the company, the ministry had asked Meta to ensure that its recommendation systems do not lead to the disproportionate exposure of users to a single or limited set of narratives and instead provide greater access to diverse, relevant and credible information, according to them.
The ministry also directed Meta to strengthen mechanisms for rapidly identifying, reviewing and escalating content that gains significant reach through recommendation systems when such material has the potential to contribute to public confusion, violence or disruption of public order.
Apart from that, the US-based company has been asked to implement the measures immediately and inform the government of the action taken.
The advisory specifically highlights photographs, videos and graphics related to ongoing public events where the authenticity, timing, location or surrounding circumstances may be unclear.
It calls for additional context where old or unrelated visuals are presented as current, where footage has been selectively edited or where unverified claims are made regarding emergencies, police action or other official measures.
Additionally, this marks the latest escalation in the government’s scrutiny of Meta’s moderation and recommendation systems.
Earlier in August, government officials questioned Meta executives over content recommendation algorithms, deepfakes, synthetic media and safeguards against unlawful content.
Meta has separately tightened content and advertising safeguards following concerns related to child sexual exploitation material.
The company said earlier this month it deployed new AI-driven advertising review systems and removed 5.3 million pieces of child sexual exploitation content in India during January-June 2026, with more than 98% detected proactively.
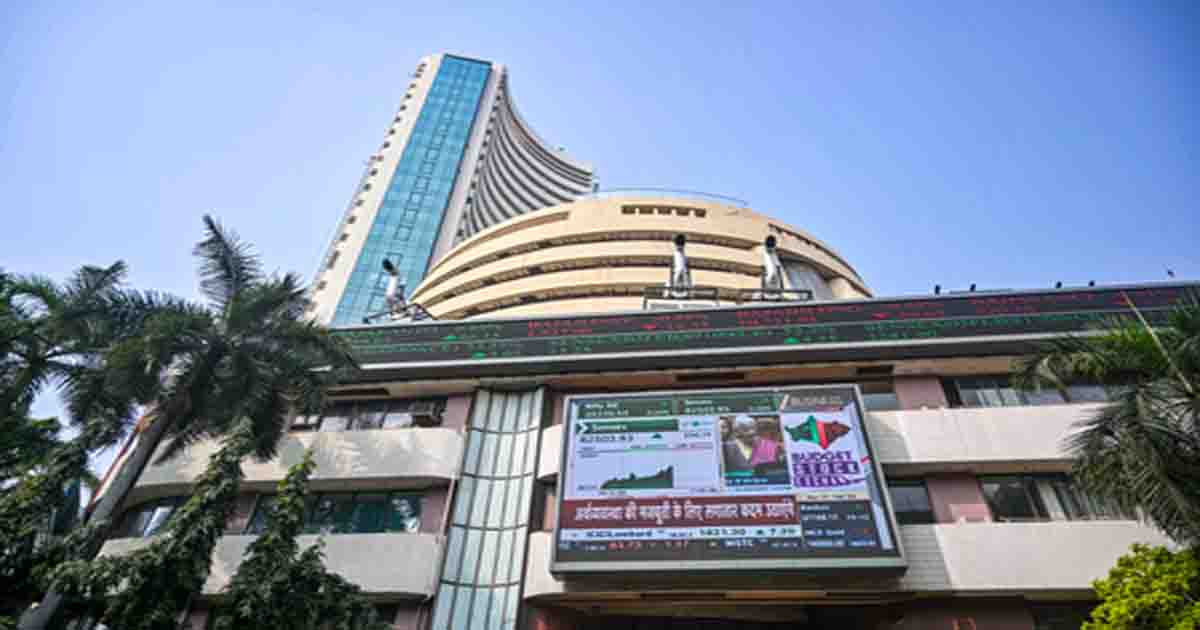
Domestic equity benchmarks opened on a flat note on Monday tracking mixed global cues and momentum from last week’s gains.
Sensex opened at 74,849.30, up 120.03 points or 0.16 per cent, while Nifty began trading at 23,150.85, up 4.70 points or 0.02 per cent.
Sectorally, Nifty PSU Bank led gains and rose over 1 per cent, followed by Nifty Oil & Gas which surged 0.6 per cent.
In contrast, Nifty Private Bank, Nifty IT and Nifty Chemicals dropped up to 1 per cent.
Market experts said momentum from Nifty’s 2.8 per cent surge last week and good results from banking majors after better-than-expected IT earnings could keep the market resilient.
“However, escalation of tensions in Hormuz and consequent surge in Brent crude to $109 will act as a strong headwind,” according to them.
They further said that attractive large-cap valuations and rupee appreciation turned FII stance slightly positive, though unlikely to sustain at high crude prices. Large-caps outperforming mid and small-caps is likely to continue, with stock-specific action on Q2 results.
For Nifty, immediate support is placed at 22,950–23,000, while resistance is seen at 23,250–23,300, the experts said and added that RSI strengthened to 52.81 above its average of 34.70, while PCR stood at 1.08.
In the previous session on October 16, FIIs turned net buyers after 15 straight sessions of selling, buying equities worth about Rs 1,166 crore, while DIIs ended their 45-session buying streak with net sales of around Rs 3,661 crore.
On commodities, Brent crude traded nearly 2 per cent lower at around $107.76 per barrel, while US WTI declined about 1 per cent to $100.43.
In Asia, markets were mixed. Japan’s Nikkei traded 0.84 per cent lower, while Hong Kong’s Hang Seng and South Korea’s KOSPI rose up to 0.83 per cent. Indonesia’s Jakarta Composite fell over 5 per cent.
India’s strong economic growth trajectory and the implementation of the India-EFTA Trade and Economic Partnership Agreement (TEPA) are creating significant opportunities for Norwegian investors, particularly in manufacturing, renewable energy, infrastructure, financial services and the digital economy, according to industry insights.
With GDP growth projected to remain around 6.5 per cent annually through 2030, India is widely expected to become the world’s third-largest economy by the end of the decade, according to EY India report.
Analysts attribute this outlook to strong domestic consumption, rising investments, ongoing infrastructure development and reforms aimed at improving the ease of doing business.
The India-EFTA TEPA, which came into effect in October 2025, is being viewed as a major milestone in India-Norway economic relations.
The agreement seeks to promote trade liberalisation, facilitate investment flows and deepen cooperation in areas such as innovation, sustainability and advanced technologies.
The pact includes investment commitments of $100 billion over 15 years and is expected to support the creation of one million direct jobs in India, aligning with the country’s broader goals of expanding manufacturing capacity and strengthening its position in global value chains.
Industry experts believe the agreement creates a strong framework for Norwegian companies to expand their presence in India by combining Norway’s expertise in technology, sustainability and capital-intensive industries with India’s large market and growth ambitions.
Several sectors have been identified as priority areas for collaboration, including manufacturing, renewable energy, oil and gas, maritime services, seafood processing, information and communication technology (ICT), fintech and financial services. These industries are expected to benefit from increasing bilateral cooperation under the TEPA framework.
The rapid expansion of India’s digital economy and digital payments ecosystem is also creating opportunities for Norwegian companies seeking exposure to one of the world’s largest and fastest-growing consumer markets.
At the same time, India’s policy measures aimed at attracting foreign investment are expected to provide a supportive environment for long-term investors, as per the report.

Bihar MLC election: Three FIRs filed against Anant Singh, Jan Suraaj candidate Anuj Singh

‘Owaisi, BJP are twins’: Congress MP accuses AIMIM chief of splitting Oppn votes

Odisha: Jharsuguda police arrest wanted criminal after exchange of fire

‘Should face same punishment as adults’: Abu Azmi demands lowering of age of juvenile offenders to 14

Tiger Shroff firing case: 3 suspects held in Rajasthan’s Kota planned to flee to Nepal, say police

Rahul, Cong ecosystem want to force regime change: BJP after Neha Bora praises B’desh Gen-Z protest

BJP pays tribute to ex-President Abdul Kalam, recalls his enduring influence on generations of India’s youth

Attack on democratic rights: INDIA Bloc leaders on detentions of anti-ECI protestors

INDIA bloc begins protest march against ECI

Maha Congress stages agitation against Gyanesh Kumar
-

 Crime4 years ago
Class 10 student jumps to death in Jaipur
-

 Maharashtra2 years ago
Mumbai Local Train Update: Central Railway’s New Timetable Comes Into Effect; Check Full List Of Revised Timings & Stations
-

 Maharashtra2 years ago
Mumbai To Go Toll-Free Tonight! Maharashtra Govt Announces Complete Toll Waiver For Light Motor Vehicles At All 5 Entry Points Of City
-

 Maharashtra2 years ago
False photo of Imtiaz Jaleel’s rally, exposing the fooling conspiracy
-

 National News2 years ago
Ministry of Railways rolls out Special Drive 4.0 with focus on digitisation, cleanliness, inclusiveness and grievance redressal
-

 Maharashtra2 years ago
Maharashtra Elections 2024: Mumbai Metro & BEST Services Extended Till Midnight On Voting Day
-

 National News2 years ago
J&K: 4 Jawans Killed, 28 Injured After Bus Carrying BSF Personnel For Poll Duty Falls Into Gorge In Budgam; Terrifying Visuals Surface
-

 Crime2 years ago
Baba Siddique Murder: Mumbai Police Unable To Get Lawrence Bishnoi Custody Due To Home Ministry Order, Says Report