Business
Govt drive returns Rs 2,000 crore unclaimed savings to rightful owners
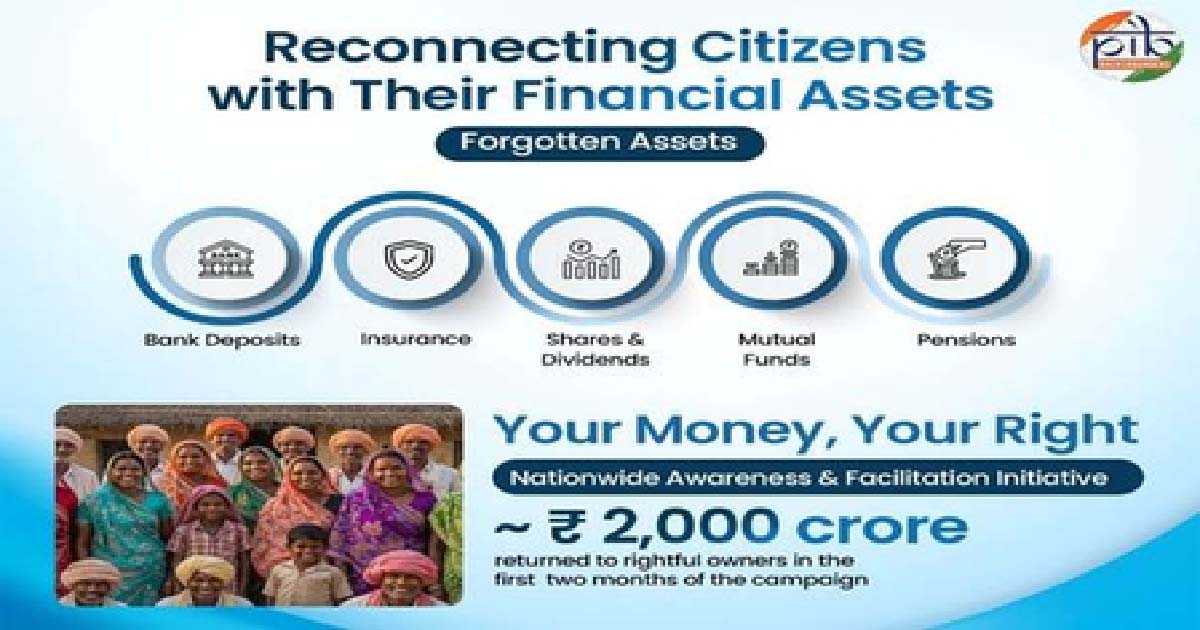
New Delhi, Dec 26: The government has succeeded in returning to the rightful owners a total amount of nearly Rs 2,000 crore that was stuck as “unclaimed savings” across banks, insurance, mutual funds, dividends, shares, and retirement benefits held within the regulated financial system, according to an official statement issued on Friday.
The funds have been restored through the Centre’s “Your Money, Your Right” nationwide awareness and facilitation initiative, launched in October 2025 to help citizens identify and reclaim unclaimed financial assets. The initiative is being coordinated by the Finance Ministry’s Department of Financial Services, with financial sector regulators reaching across digital portals with district-level facilitation.
Across generations, Indian families have saved carefully through opening bank accounts, purchasing insurance policies, investing in mutual funds, earning dividends from shares, and setting aside money for retirement. These financial decisions are taken with a hope and responsibility, often to secure children’s education, support healthcare needs, and ensure dignity in old age.
Yet, over time, a significant portion of these hard-earned savings has remained unclaimed. The money has not vanished, nor has it been misused. It lies safely with regulated financial institutions, separated from its rightful owners due to a lack of awareness, outdated records, changes in residence, or missing documentation. In many cases, families are simply unaware that such assets exist.
The volume of unclaimed financial assets in India is significant and spans multiple segments of the formal financial system. Indicative estimates suggest that Indian banks together hold around Rs 78,000 crore in unclaimed deposits. Unclaimed insurance policy proceeds are estimated at nearly Rs 14,000 crore, while unclaimed amounts in mutual funds are about Rs 3,000 crore. In addition, unclaimed dividends account for around Rs 9,000 crore, according to official figures.
Together, these amounts underline the scale of unclaimed savings belonging to citizens that continue to remain unused, despite being securely held within the financial system.
Your Money, Your Right is a nationwide effort to reconnect citizens with these forgotten financial assets and ensure that money that belongs to individuals and families ultimately finds its way back to them.
These unclaimed financial assets arise when money held with financial institutions is not claimed by the account holder or their legal heirs for a prolonged period. Such assets include:
*Bank deposits such as savings accounts, current accounts, fixed deposits, and recurring deposits that have not been operated for ten years or more.
*Insurance policy proceeds that remain unpaid beyond the due date
*Mutual fund redemption proceeds or dividends that could not be credited due to reasons such as a change in bank account, bank account closure, incomplete bank account in records, etc.
*Dividends and shares that remain unclaimed and are transferred to statutory authorities
*Pension and retirement benefits that are not claimed within the normal course
In most cases, assets may become unclaimed because of routine life events such as migration for work, changes in contact details, closure of old bank accounts, or lack of information among family members and legal heirs.
The Government is coordinating with the Reserve Bank of India (RBI), the Insurance Regulatory and Development Authority of India (IRDAI), the Securities and Exchange Board of India (SEBI), the Investor Education and Protection Fund Authority (IEPFA), and the Pension Fund Regulatory and Development Authority (PFRDA) to help citizens identify, access and reclaim financial assets that legally belong to them, using simple processes and transparent systems.


New Delhi, Oct 9: PhonePe and the Digital Publisher Content Grievances Council (DPCGC), a self-regulatory body under the aegis of the Internet and Mobile Association of India (IAMAI), have announced the signing of a Memorandum of Understanding (MoU).
The partnership aims to facilitate seamless SRO certification for all merchants, champion regulatory compliance, and drive merchant education for all merchant partners onboarding on PhonePe’s Payment Gateway.
Under applicable Indian regulations, over-the-top (OTT) or Publishers of Online Curated Content (OCCPs) are legally required to be members of a recognised self-regulatory organisation (SRO) for grievance redressal.
Pioneering a compliance-first approach, PhonePe enforces this regulatory requirement as a mandatory prerequisite during its merchant onboarding process.
DPCGC is a Level II SRO formed under the IT Rules, 2021, which is registered with the Ministry of Information and Broadcasting.
Through the MoU, PhonePe and DPCGC aim to drive merchant education and awareness.
Recognising the limited awareness among OTT/OCCPs regarding SRO compliance, the joint initiative will educate both existing and prospective merchants on regulatory requirements and seamlessly facilitate their SRO certification through DPCGC.
The partnership further strengthens PhonePe’s position as a trusted, robust, and compliant payment partner tailored for the rapidly growing OTT ecosystem.
Dr. Subho Ray, President of IAMAI, said, “DPCGC, established under the IT Rules, is committed to efficiently addressing concerns and grievances related to OTT platforms through self-regulation.
This collaboration between DPCGC and PhonePe will foster greater alignment and adherence to the Code of Ethics, expanding the reach of self-regulation and strengthening its benefits for both the industry and its users.”
Deep Agrawal, Head of Payments at PhonePe, added, “At PhonePe, compliance and trust are at the core of everything we build. The OTT segment has exploded in terms of coverage and penetration over the last couple of years.
Agrawal further stated that our MoU with DPCGC will allow us to educate the OTT platforms to seamlessly drive higher awareness about customer grievance redressal, reinforcing PhonePe as the most trusted & compliant growth partner for India’s booming OTT ecosystem.”
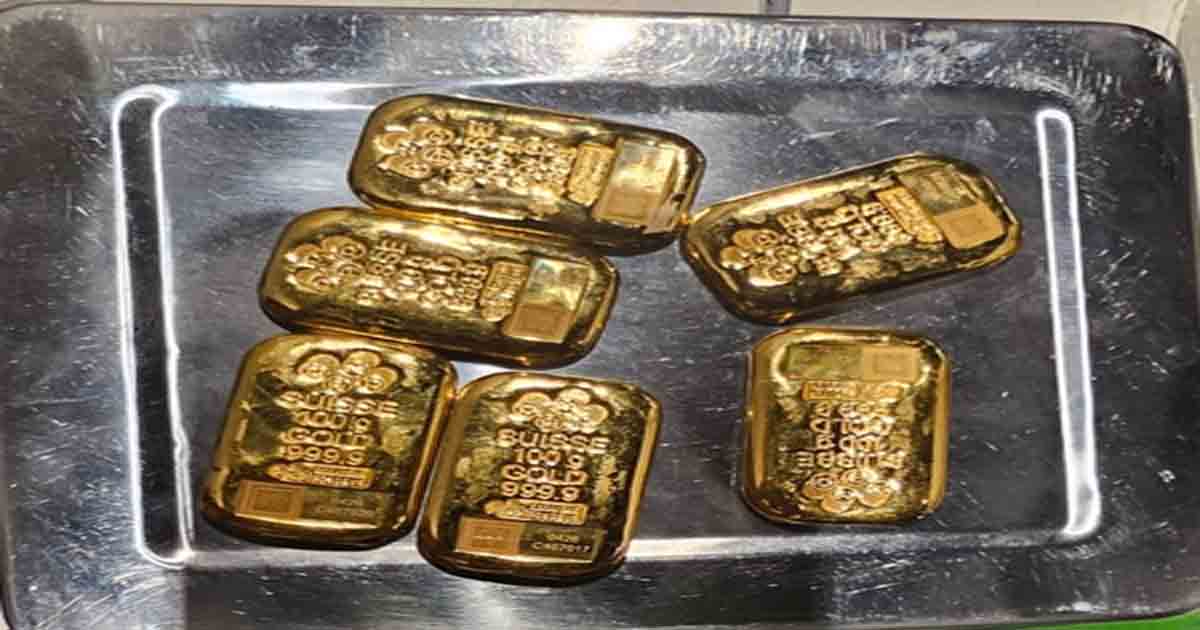
The Directorate of Revenue Intelligence (DRI) has seized 1.3 kg of gold biscuits worth Rs 1.8 crore in a smuggling operation involving luggage trolleys. Two accused transported the gold from Kuala Lumpur, Malaysia, and concealed the biscuits by sticking them to luggage trolleys.
The accused allegedly targeted unsuspecting passengers who picked up these trolleys and crossed customs. They reportedly followed the passengers and later retrieved the gold from the trolleys, using innocent travellers as unwitting carriers without their knowledge.
Acting on intelligence inputs, DRI officials seized the gold. The investigation is expected to focus on the alleged smuggling network and the modus operandi used to transport the gold through unsuspecting passengers.
Earlier, on October 4, the DRI had seized a cumulative 15.59 kg of narcotic drugs, including amphetamine, cocaine and heroin, in three separate intelligence-led operations, the Finance Ministry said. Five people were arrested under the provisions of the Narcotic Drugs and Psychotropic Substances (NDPS) Act, 1985.
In one operation, the DRI, in coordination with the Central Bureau of Narcotics (CBN), had intercepted a car suspected of carrying amphetamine at the Ujjain-Dewas Toll Plaza in Madhya Pradesh.
When signalled to stop, the driver had allegedly broken through the barricade and sped away. The officers pursued the vehicle in a high-speed chase lasting approximately 1.5 hours before intercepting it near Bicholi Mardana in Indore.
A detailed search of the vehicle led to the discovery of the contraband concealed inside the spare tyre mounted on the rear door of the Thar, according to the statement.
Earlier, on October 2, the DRI’s Mumbai Zonal Unit had busted an international syndicate involved in smuggling 8.5 kg of gold worth Rs 12.65 crore into India and trafficking 1,168 carats of diamonds worth Rs 1.09 crore out of the country to Dubai through Chhatrapati Shivaji Maharaj International Airport (CSMIA).
The DRI had arrested eight members of the syndicate for their alleged involvement in trafficking valuables into and out of the country.
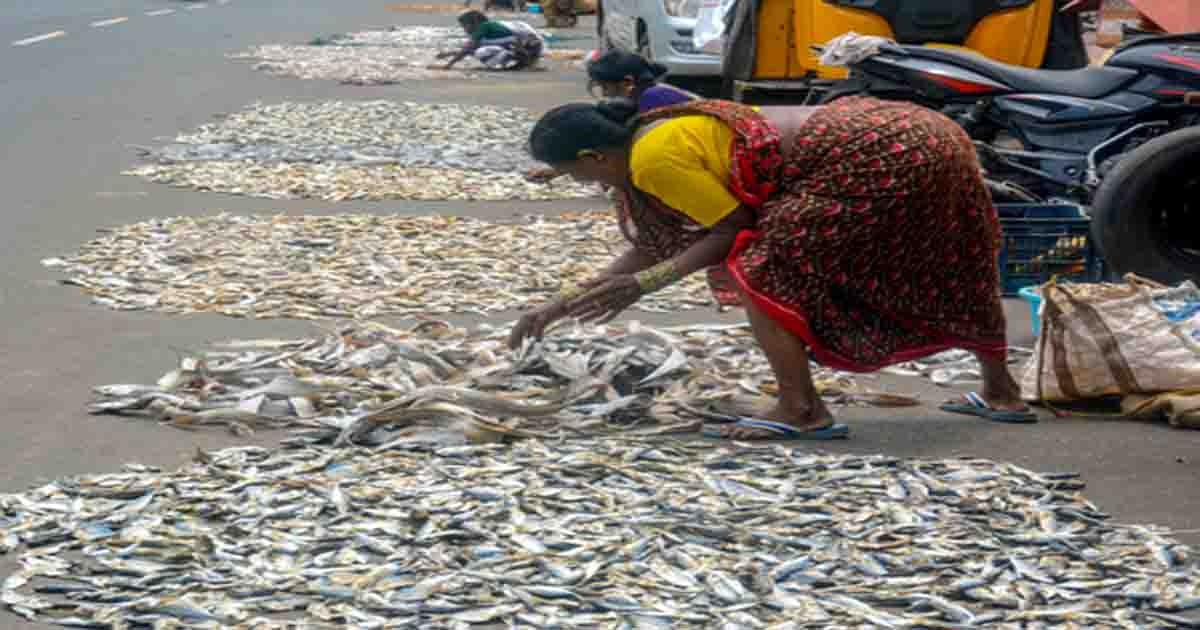
New Delhi, Oct 8: India’s decision to ratify Phase 1 of the World Trade Organization’s Agreement on Fisheries Subsidies is a pragmatic step to curb illegal, unreported and unregulated fishing while preserving its policy space on issues that directly affect small-scale and artisanal fishers, an official statement said on Thursday.
The statement from the Ministry of Fisheries, Animal Husbandry & Dairying said India deposited its Instrument of Acceptance on July 20, 2026, and that the ratified phase targets IUU fishing, overfished stocks and unregulated high‑seas fishing.
“It does not cover the more difficult questions of overcapacity and overfishing, including subsidies for fuel, gear, ice, vessel construction and modernisation,”
“Those issues belong to Phase 2, where India continues to seek fair and differentiated treatment for developing countries,” the statement said citing views of Dr. M. Krishnan, former Principal Scientist & Head, ICAR – CIFE and Dr. P. Krishnan, Director, BOBP-IGO.
India supports measures aimed at the most harmful fishing practices but insists conservation rules must not reduce the development space of coastal communities that depend on marine fisheries for livelihoods.
“For India, the challenge is not whether to support conservation, but how to ensure that conservation does not come at the cost of equity,” the statement, calling the country’s position principled and practical.
India made clear that its ratification of Phase 1 does not weaken its demand for a longer transition period and more flexible treatment in Phase 2. The call for a 25-year transition period for developing countries within their exclusive economic zones remains part of the broader negotiating position.
India also insists that subsidy disciplines should be assessed using a per-fisher benchmark, rather than through comparisons that overlook vast differences in scale, capacity and state support.
Across the Bay of Bengal region, fisheries are a source of food security, employment and social stability for millions of small-scale fishers rather than merely an economic activity.
Hence, any multilateral discipline on subsidies must recognise the realities of artisanal and coastal fisheries in developing countries, where support is often aimed at livelihood protection rather than industrial expansion.

No permission for Jantar Mantar protest, Delhi Police seek closure of 57 metro stations

Week after Supernova suicide, 36-year-old man dies after fall from 12th floor of Greater Noida West society

Puducherry bypolls: AINRC retains Thattanchavady; Cong comes second

PhonePe and DPCGC forge partnership to drive regulatory compliance in the OTT ecosystem

DRI seizes gold worth Rs 1.8 crore hidden in luggage trolley, probe underway

Gift to President Putin part of PM Modi bid to globally display India’s heritage

PM Modi’s warm camaraderie with Putin, Xi on full display at BRICS Summit

Complaint against Netflix & Mukesh Chhabra for inappropriate language on ‘India’s Got Latent 2’

INDIA bloc begins protest march against ECI

Maha Congress stages agitation against Gyanesh Kumar
-

 Crime4 years ago
Class 10 student jumps to death in Jaipur
-

 Maharashtra2 years ago
Mumbai Local Train Update: Central Railway’s New Timetable Comes Into Effect; Check Full List Of Revised Timings & Stations
-

 Maharashtra2 years ago
Mumbai To Go Toll-Free Tonight! Maharashtra Govt Announces Complete Toll Waiver For Light Motor Vehicles At All 5 Entry Points Of City
-

 Maharashtra2 years ago
False photo of Imtiaz Jaleel’s rally, exposing the fooling conspiracy
-

 National News2 years ago
Ministry of Railways rolls out Special Drive 4.0 with focus on digitisation, cleanliness, inclusiveness and grievance redressal
-

 Maharashtra2 years ago
Maharashtra Elections 2024: Mumbai Metro & BEST Services Extended Till Midnight On Voting Day
-

 National News2 years ago
J&K: 4 Jawans Killed, 28 Injured After Bus Carrying BSF Personnel For Poll Duty Falls Into Gorge In Budgam; Terrifying Visuals Surface
-

 Crime2 years ago
Baba Siddique Murder: Mumbai Police Unable To Get Lawrence Bishnoi Custody Due To Home Ministry Order, Says Report