Business
Four Labour Codes are most progressive reforms for workers since Independence: PM Modi
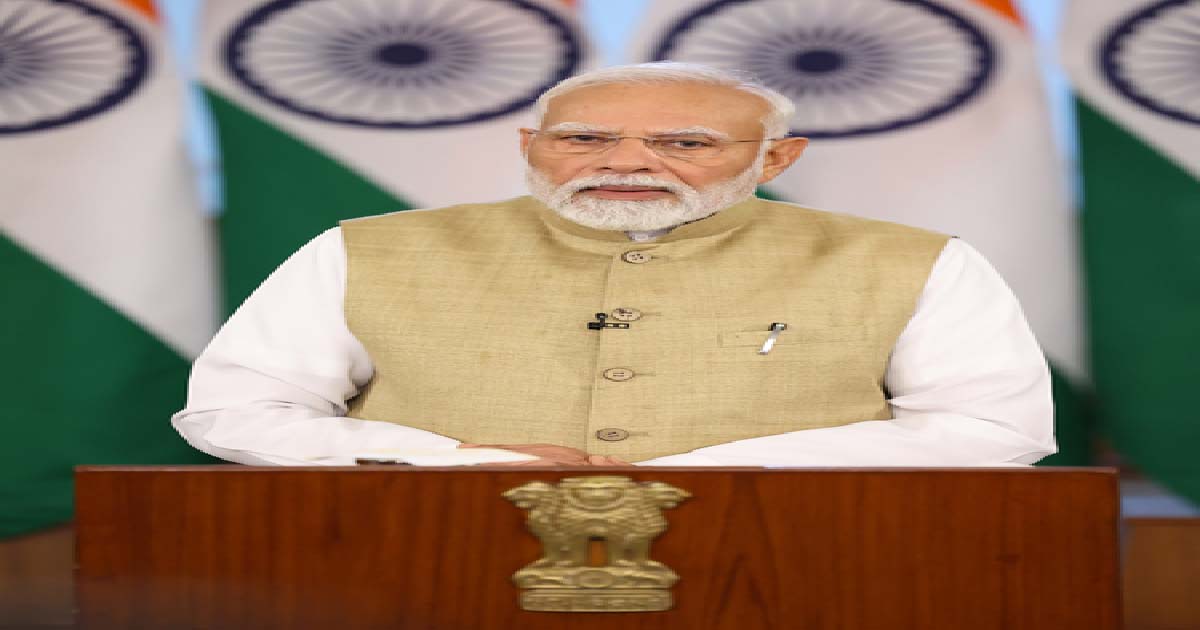
New Delhi, Nov 21: Prime Minister Narendra Modi on Friday said the government has given effect to the Four Labour Codes, which are one of the most comprehensive and progressive labour-oriented reforms since Independence.
“It greatly empowers our workers. It also significantly simplifies compliance and promotes Ease of Doing Business,” the Prime Minister remarked.
He said that these Codes will serve as a strong foundation for universal social security, minimum and timely payment of wages, safe workplaces and remunerative opportunities for our people, especially ‘Nari Shakti and Yuva Shakti’.
“It will build a future-ready ecosystem that protects the rights of workers and strengthens India’s economic growth. These reforms will boost job creation, drive productivity and accelerate our journey towards a Viksit Bharat,” he added.
The four labour codes include the Code on Wages, 2019, the Industrial Relations Code, 2020, the Code on Social Security, 2020 and the Occupational Safety, Health and Working Conditions Code, 2020, with effect from November 21, rationalising 29 existing labour laws.
With the implementation of the Labour Codes, it has now become mandatory for employers to issue appointment letters to all workers, which provides written proof to ensure transparency, job security, and fixed employment. Earlier, no mandatory appointment letters were required.
Under Code on Social Security, 2020, all workers, including gig and platform workers, will get social security coverage. All workers will get PF, ESIC, insurance, and other social security benefits. Earlier, there was only limited security coverage.
Under the Code on Wages, 2019, all workers will receive a statutory right minimum wage payment which wages and timely payment will ensure financial security. Earlier, minimum wages applied only to scheduled industries or employments; large sections of workers remained uncovered.
The Labour codes also ensure that employers must provide all workers above the age of 40 years with a free annual health check-up and promote a timely preventive healthcare culture. Earlier, there was no legal requirement for employers to provide free annual health check-ups to workers.
The codes also make it mandatory for employers to provide timely wages, to ensure financial stability, reducing work stress and boosting the overall morale of the workers. Earlier, there was no mandatory compliance for employers’ payment of wages.
The new law permits women to work at night and in all types of work across all establishments, subject to their consent and required safety measures. Women will also get equal opportunities to earn higher incomes in high-paying job roles. Earlier, women’s employment in night shifts and certain occupations was restricted.
The new codes also extend ESIC coverage and benefits pan-India – voluntary for establishments with fewer than 10 employees, and mandatory for establishments with even one employee engaged in hazardous processes.
Social protection coverage will be expanded to all workers. Earlier, ESIC coverage was limited to notified areas and specific industries; establishments with fewer than 10 employees were generally excluded, and hazardous-process units did not have uniform mandatory ESIC coverage across India.
The codes also ease the compliance burden for workers by providing for single registration, a PAN-India single license and a single return. Earlier, multiple registrations, licenses and returns across various labour laws were required.


Foreign portfolio investors (FPIs) turned net buyers of Indian equities in November, investing Rs 53,739 crore during the first nine days of the month after remaining net sellers for the previous two months, amid improving sentiment towards Indian markets and a global shift away from AI-linked trades.
The latest inflows come after FPIs withdrew Rs 34,843 crore from Indian equities in October and Rs 35,861 crore in September.
Analysts attributed the sharp turnaround to an AI-driven sell-off across major global markets, including the US, South Korea, Taiwan and Japan, which prompted investors to reassess their allocations.
According to analysts, concerns over data centre spending linked to artificial intelligence triggered a correction in AI-focused markets, leading global investors to seek opportunities in sectors and markets less exposed to the AI theme.
India, widely viewed as a non-AI trade, emerged as one of the preferred destinations for foreign investors during this period.
Apart from the change in global investment trends, India’s strong corporate earnings growth and attractive valuations in large-cap stocks also enhanced the market’s appeal.
Analysts noted that foreign investors were particularly active in index heavyweights, with financial services, information technology, automobile and telecom stocks attracting significant inflows.
Data from depositories showed that the Rs 53,739 crore infusion was recorded between November 2 and November 9, covering six trading sessions.
Despite the strong buying in November, cumulative FPI outflows from Indian equities in 2026 remain substantial at Rs 2.41 lakh crore.
In the debt market, foreign investors invested Rs 7,759 crore through the Fully Accessible Route (FAR).
However, they pulled out Rs 591 crore through the Voluntary Retention Route (VRR) and withdrew another Rs 270 crore through the general route.
Market participants believe sustained earnings growth and reasonable valuations in large-cap stocks could continue to support foreign investment flows into Indian equities in the near term, although global macroeconomic developments and investor sentiment towards risk assets will remain key factors to watch.
India’s information technology (IT) services sector delivered Q2 FY27 results that were modestly ahead of subdued expectations, but the broader recovery in demand is increasingly being pushed into FY28 as companies contend with pricing pressure and AI-driven disruption, a report said on Friday.
The report from BNP Paribas India said investors responded positively to better-than-expected earnings after analysing quarterly results from 15 Indian IT services companies, including five large-cap and 10 mid-cap firms.
Shares of the covered companies rose by a median 5 per cent following the results after having declined about 23 per cent year-to-date in 2026.
The market rewarded better-than-feared revenue, margin expansion and strong deal momentum, while penalising margin pressure and weak deal wins. Demand remains steady but narrow, with the financial services vertical as the bright spot.
“While FY27 headline revenue growth guidance cuts seemed modest, the organic cut was sharper, implying that FY27 organic revenue is likely to trail FY26, with acquisitions filling in the gap partly,” the report said.
“AI-led work continues to grow even as clients demand pass-back of the productivity gains, shrinking the legacy books and pushing down pricing pressure. With seasonally weak H2FY27, companies now expect recovery in FY28, supported by large deal ramp-ups,” the report noted.
Collectively, 60 per cent of the firms beat on revenue and 53 per cent beat on EBIT margin expectations, while 27 per cent missed on revenue growth and 40 per cent missed EBIT margin expectations.
Deal Total Contract Value (TCV) inched up modestly annually in Q2FY27, underpinned by strong wins of three companies. Headcount increased slightly sequentially, while attrition and utilisations improved modestly.
Another recent report said that management commentary across nearly all major Indian IT companies during Q1 FY27 earnings season showed that clients demanded measurable outcomes, governance frameworks and stronger data foundations before committing to large-scale AI rollouts.
India, as Chair of the Kimberley Process (KP) for 2026, has flagged key priorities concerning the global diamond industry, including responsible rough diamond sourcing as part of its outreach ahead of the KP Plenary to be held in Delhi from November 30 to December 4, according to a statement issued by the Commerce Ministry on Thursday.
The issue was discussed at a stakeholder consultation in Angola’s Luanda on Tuesday, chaired by Additional Secretary Yashvir Singh on India’s behalf, which brought together the Chairs and Vice-Chairs of KP Working Groups and Committees (KP Working Bodies), the KP Vice-Chair (of Ghana), and the former KP Chair (of the United Arab Emirates). Representatives of observers and partner organisations, including the World Diamond Council and the African Diamond Producers’ Association (ADPA), also participated in the discussion, the statement said.
India has observer status in the ADPA, providing an institutional platform for engagement with African diamond-producing countries. This offers opportunities for cooperation in securing rough diamond supply chains, technical knowledge exchange, value addition, market access and the promotion of ethical and sustainable practices.
The 13th Extraordinary Meeting of the ADPA Council of Ministers, held alongside the 20th anniversary celebrations, approved a Memorandum of Understanding (MoU) between the Gem & Jewellery Export Promotion Council (GJEPC), India, and the ADPA. The MoU seeks to strengthen cooperation between the Indian gem and jewellery industry and African diamond-producing countries, including through capacity building and skills development in diamond sorting, valuation and manufacturing, exchange of technical expertise, and the promotion of trade and investment linkages across the diamond value chain, the statement said.
Yashvir Singh said: “India’s chairship places emphasis on confidence, compliance and credibility. The consultation in Luanda provided an opportunity to engage directly with the leadership of the KP working bodies, the KP Vice-Chair and observers on issues that are important to the future of the Process and the diamond industry. Our endeavour is to build a shared understanding of the issues before the New Delhi Plenary and to advance practical outcomes through constructive dialogue and consensus-based decision-making.”
Discussions covered the sustainability of diamond-producing countries and communities, sustainable funding and continuity of the KP Secretariat, digitalisation of certification and statistical processes, and strengthening compliance with the Kimberley Process Certification Scheme.
Participants also exchanged views on the reform of the conflict diamond definition, responsible sourcing, artisanal and alluvial diamond production, consumer confidence and the importance of effective reporting and peer-review mechanisms.
The ADPA, established in 2006 in Luanda, seeks to enhance cooperation among African diamond-producing nations. It effectively comprises 15 member countries and 8 observers, including two non-African observers, namely Russia and India. Its member countries collectively account for over 60 per cent of global diamond production.

Chetan Hansraj reveals four-hour transformation into Raja Mali in ‘Ramayana: Part 1’

Six coaches of Kolkata–Sairang Express derail in Assam; several injured

Hamas alone responsible for suffering of Gaza people: Israel

Iran rejects France accusation of involvement in cyberattack

US charges 3 in Iran-backed terror plot case

Rahul, Cong ecosystem want to force regime change: BJP after Neha Bora praises B’desh Gen-Z protest

BJP pays tribute to ex-President Abdul Kalam, recalls his enduring influence on generations of India’s youth

Attack on democratic rights: INDIA Bloc leaders on detentions of anti-ECI protestors

Congress trying to protect 3 crore Bangladeshi infiltrators in voter list: HM Shah

Online betting: ED conducts searches at 20 premises in Mumbai, Pune, Hyderabad
-

 Crime4 years ago
Class 10 student jumps to death in Jaipur
-

 Maharashtra2 years ago
Mumbai Local Train Update: Central Railway’s New Timetable Comes Into Effect; Check Full List Of Revised Timings & Stations
-

 Maharashtra2 years ago
Mumbai To Go Toll-Free Tonight! Maharashtra Govt Announces Complete Toll Waiver For Light Motor Vehicles At All 5 Entry Points Of City
-

 Maharashtra2 years ago
False photo of Imtiaz Jaleel’s rally, exposing the fooling conspiracy
-

 National News2 years ago
Ministry of Railways rolls out Special Drive 4.0 with focus on digitisation, cleanliness, inclusiveness and grievance redressal
-

 Maharashtra2 years ago
Maharashtra Elections 2024: Mumbai Metro & BEST Services Extended Till Midnight On Voting Day
-

 National News2 years ago
J&K: 4 Jawans Killed, 28 Injured After Bus Carrying BSF Personnel For Poll Duty Falls Into Gorge In Budgam; Terrifying Visuals Surface
-

 Crime2 years ago
Baba Siddique Murder: Mumbai Police Unable To Get Lawrence Bishnoi Custody Due To Home Ministry Order, Says Report